Costs of Selling a Home in Alberta: Check Your Mortgage Payout Penalty Before You List

General Travis Bannert 25 Oct

Before you list an Edmonton home, get your mortgage payout statement — because the prepayment penalty for breaking your term early is the seller cost most likely to change your plans, and it ranges from a few hundred dollars to well over ten thousand depending on your mortgage type and how rates have moved. Commission and legal fees are predictable; the penalty is personal. Knowing it before you price lets you choose intelligently between selling now, selling at renewal, or porting the mortgage to your next home.

How is the penalty calculated?

On most variable-rate mortgages, the charge is three months’ interest on the balance. On most fixed-rate mortgages, it is the greater of three months’ interest or the interest rate differential (IRD) — a calculation comparing your contract rate to the lender’s current rate for a similar remaining term, applied across your balance and time left. Posted-rate lenders’ IRD math can produce much larger penalties than discount lenders’. I explain the formulas in three months’ interest vs IRD and breaking a mortgage early.

What are your three options once you know the number?

Sell and pay it, when the move matters more than the charge and the net proceeds still work — the real-estate side of that net sheet is in the companion guide to seller costs. Wait for renewal, when the penalty disappears, if your timeline is flexible. Or port the mortgage to the new home, keeping your rate and term and avoiding the penalty where you qualify — the mechanics are in porting your mortgage in Alberta. Each option prices differently once the real penalty is known, which is why estimates from online calculators are not enough: request the lender’s own payout figure, in writing, as of your expected sale window.
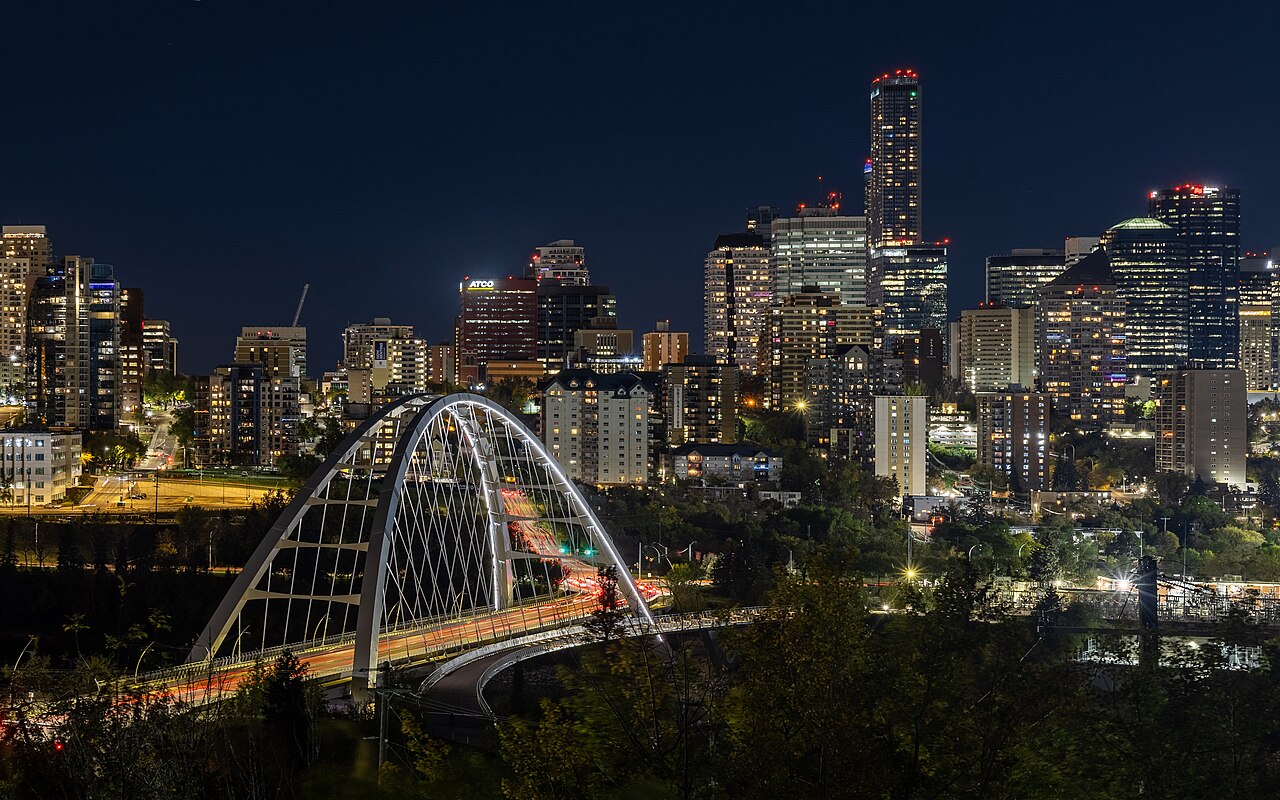
Edmonton sellers checking mortgage payout before listing

Photo via Wikimedia Commons.

When should you check?

At the same time you order your home evaluation — before photos, before pricing, before you fall for the next home. Run the check through a Mortgage Renewal Check if your term is ending, or the Pre-Approval & Refinance Check if you are buying next and porting or blending is on the table.

“We almost listed before Travis checked our penalty. Porting instead saved us a five-figure charge.” — Google review excerpt

Listing this fall? Get your real payout number first. Call (780) 722-5621 — I will try to call you this week, or reply with a good time and we will set a phone appointment to map sell-now, wait, or port on your actual figures.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Renewal vs Refinance vs Switch in Canada: Three Different Mortgage Moves, Explained Plainly

General Travis Bannert 25 Oct

At the end of a term you have three distinct moves, and using the right name matters because each has different costs and paperwork. A renewal continues your mortgage with your current lender on new terms, with no penalty because your term has ended. A switch (transfer) moves the same mortgage balance to a new lender at renewal, usually without a penalty and often with switch costs covered. A refinance replaces your mortgage with a new one — different amount, amortization or structure — and doing it mid-term triggers a prepayment penalty. Choose by what you actually need to change.

When is a simple renewal the right move?

When your balance, amortization and ownership are staying the same and your current lender’s offer is genuinely competitive — which you only know by comparing it. Renewing requires the least paperwork, but signing the first offer without a comparison is how borrowers overpay for five more years. Start the comparison with a Mortgage Renewal Check about four months before your maturity date, while rate holds can protect you.

When does a switch beat a renewal?

When another lender offers a better rate or terms for the same mortgage. A straight switch keeps your balance and remaining amortization, so qualification is lighter than a refinance, though the stress test still applies in most cases. Lenders frequently cover transfer costs such as legal and appraisal on a switch — ask explicitly, because that coverage is what makes the math work. I walk through the sequence in renewing with a new lender, step by step.

Edmonton homeowners comparing mortgage renewal options

Photo via Wikimedia Commons.

When do you actually need a refinance?

When the mortgage itself must change: borrowing additional funds for renovations or debt consolidation, extending amortization to cut payments, adding or removing a borrower, or accessing equity. At renewal, refinancing carries no penalty; mid-term, price the penalty first — on a fixed mortgage it can be the interest rate differential, which can erase the benefit. The Pre-Approval & Refinance Check is where that math gets run on your real numbers before you commit.

“Travis showed us the renewal, switch and refinance numbers side by side. We switched lenders and kept the same payment timeline for less.” — Google review excerpt

Term ending soon and unsure which move is yours? Call (780) 722-5621 — I will try to call you this week, or reply with a good time and we will set a phone appointment to compare all three on your file.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Blend-and-Extend Mortgages in Canada: When Averaging Your Rate Helps and When It Hurts

General Travis Bannert 23 Oct

A blend-and-extend averages your current mortgage rate with today’s rate for a new, longer term — letting you lower a high payment or borrow more without paying a break penalty — at the cost of committing to your current lender for longer, often without testing the wider market. It helps when the blended result beats your alternatives after all costs; it hurts when waiting for renewal would have been free. See the renewal letter trap this option competes with.

How does the blend actually work?

Your lender weights the two rates by balance and remaining time: part of your money keeps something close to your existing rate, and the new money — a longer term, or additional borrowed funds on a blend-and-increase — is priced at current rates. The result is a single new rate somewhere between the two, on a fresh term that restarts your clock. No penalty is charged because you never leave the lender — which is precisely the lender offers it.

When does blending help?

When your current rate is far below today’s rates and you need more money or a longer runway, blending protects part of that cheap rate while you extend. When your current rate is far above today’s, blending down can cut your payment immediately without a penalty — but compare it against breaking and switching, because sometimes paying a modest penalty on a variable mortgage, or waiting a few months to renewal, produces a much lower rate than any blend your current lender will offer.

“Great rates, fast closing, and excellent customer service.” — Madhav Dhakal, Google review

Edmonton homeowner reviewing blend and extend mortgage options

Photo via Wikimedia Commons.

What are the traps?

You are negotiating with one lender who knows leaving costs you a penalty — the first blended offer is rarely the best that lender can do, and it is never compared against the wider market unless you compare it yourself. Blending also restarts a full term, which can strand you if you expect to move. And a blend-and-increase adds debt against your home: the payment math must work at the stress-test qualifying rate, not just at the blended contract rate. The alternative to compare is switching lenders at renewal, step by step.

Run the three-way comparison — blend, break-and-switch, wait for renewal — before you sign anything. A Mortgage Renewal Check covers the renewal-timing version of that math. See also breaking instead of blending: what the penalty would be.

Your lender offered you a blend? Call me at (780) 722-5621 before you accept — I will run it against the break and wait options on your real balance and penalty.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Renewing With a New Lender in Canada: What a Mortgage Switch Involves Step by Step

General Travis Bannert 23 Oct

Switching lenders at renewal means your existing mortgage balance moves to a new lender at the end of your term — no penalty, because you are not breaking anything — in exchange for a better rate, better terms, or both. It involves a fresh application and approval, so it rewards starting three to four months before your renewal date, not the week your current lender’s letter arrives. See why your bank’s first renewal offer is rarely its best.

What is the difference between a switch, a transfer and a refinance?

A switch or transfer keeps the same balance, the same amortization, and the same borrowers on title — you are changing who holds the mortgage, on new terms. A refinance changes the structure: a larger balance, a longer amortization, added borrowers, or cash out. That distinction matters because a straight switch is simpler, often qualifies under insured-switch rules where they apply, and may not require a new appraisal — while a refinance is underwritten as a bigger change and priced accordingly.

What are the steps, in order?

First, a comparison: your current lender’s renewal offer against what other lenders will actually approve, including rate, term, penalty formula, portability and prepayment privileges — not rate alone. Second, an application with income and property documentation, similar to your original purchase file. Third, approval and instructions to a lawyer or title service to discharge the old mortgage and register the new one on your renewal date. Fourth, confirmation after funding that the old balance is discharged and your new payment schedule is correct. Many lenders cover some switch costs, such as appraisal or transfer fees, as part of their offers — confirm what is covered in writing, because “free switch” claims vary.

“The team at NextDoor Mortgages (Mei & Travis) are the absolute best… provided the help I needed in securing my mortgage.” — Yomi Odusanya, Google review

Renewing a mortgage with a new lender in Edmonton

Photo via Wikimedia Commons.

When does switching not make sense?

When your current lender matches the market on a full comparison, when you plan to sell or refinance within the new term and the new lender’s penalty or portability rules are worse, or when your income or credit has changed enough that a new approval is risky — your existing lender’s renewal requires no re-qualification, and that safety has real value on some files. That honest comparison is exactly what a Mortgage Renewal Check is for: we review your lender’s offer against live alternatives and switch only when the full picture — not the headline rate — says so. As the stay-put alternative, see blend-and-extend as the stay-put alternative. And if a move is also on the table, see porting instead of switching, if you’re also moving.

Renewal coming up in the next four months? Call me at (780) 722-5621 and we will time the switch so your current term never needs breaking.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Three Months’ Interest vs IRD: Which Mortgage Penalty Applies to You?

General Travis Bannert 22 Oct

On a closed variable-rate mortgage in Canada, the penalty to break early is typically three months’ interest. On a closed fixed-rate mortgage, the penalty is the greater of three months’ interest or the interest rate differential (IRD). Which one applies to you depends on your mortgage type, how much time is left in your term, and how rates have moved since you signed. See breaking a mortgage early: the full penalty picture.

Which penalty applies to a variable-rate mortgage?

For most closed variable-rate mortgages, the penalty is three months’ interest on the remaining balance at your current rate. There is usually no IRD calculation on a standard variable product, which is one reason some borrowers choose variable when they think a move or refinance during the term is possible.

Open mortgages are different again: they can generally be repaid in full without penalty, in exchange for a higher rate. Check whether your mortgage is open or closed first — that single word changes the answer completely. See open vs closed terms and the privileges that soften penalties.

Which penalty applies to a fixed-rate mortgage?

For a closed fixed-rate mortgage, lenders calculate both numbers and charge the greater one: three months’ interest, or the IRD. Early in a term, or after rates have fallen, the IRD is often the larger figure. Late in a term, three months’ interest frequently wins because there is little time remaining for a differential to accumulate over.

If your term is ending soon, renewal may be cheaper than breaking at all. Compare the penalty against simply waiting, starting with a Mortgage Renewal Check.

How is the IRD calculated, in plain language?

Conceptually, the IRD is the rate differential multiplied by the remaining balance, multiplied by the remaining time in the term:

IRD ≈ (your contract rate − the lender’s comparison rate for the time remaining) × remaining balance × remaining term.

An illustrative example with round numbers only: a 1.00% differential on a $300,000 balance with 2 years remaining gives roughly 1.00% × $300,000 × 2 = $6,000. Three months’ interest on that same balance at a 4.00% contract rate would be roughly $300,000 × 4.00% ÷ 4 = $3,000 — so in this illustration the IRD, at $6,000, would be the penalty. This is arithmetic to explain the concept, not a quote for any real mortgage.

“Mei is very detail-oriented, efficient, and managed to secure me a great rate.” — Kani Lo, Google review

Understanding mortgage penalties in Edmonton — downtown Edmonton skyline

Credit: WinterE229, via Wikimedia Commons (CC0).

Why can the same mortgage produce different IRD figures at different lenders?

Each lender sets its own comparison rate and calculation details. Some use posted rates in the formula, which can make the differential — and therefore the penalty — considerably larger than a calculation based on discounted rates. The exact days remaining, the comparison term chosen, and any prepayments you have made also move the final figure.

Online calculators are estimating with assumed inputs; your lender calculates with its contract wording and its own rate schedule.

How do you get the real number for your mortgage?

Ask your current lender for a payout statement or an exact penalty quote to a specific date, and get it in writing. Note how long the figure is valid, because penalties change as time passes and rates move.

Bring that number to your broker before you list, refinance, or sign a purchase. We can then compare breaking now, using prepayment privileges first, porting the mortgage, or waiting for renewal — all against the real figure, not an estimate. Buyers weighing a move mid-term can also review the First Home Guide for Edmonton for the purchase steps that interact with timing. See porting your mortgage to avoid the penalty entirely.

Not sure which penalty applies to you? Call me at (780) 722-5621 with your lender, balance, and term end date, and we will get the exact figure and run your options side by side, or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

Porting Your Mortgage in Alberta: When Keeping Your Rate and Terms Makes Sense

General Travis Bannert 22 Oct

Porting lets you move your existing mortgage — its rate, remaining term, and balance — from the home you are selling to the home you are buying in Alberta, instead of breaking the mortgage and paying a penalty. It makes the most sense when your current rate is attractive compared to what you could get today and you have significant time left in your term. Your lender still has to approve you, the new property, and the timing.

What does porting a mortgage actually mean?

You sell one home and buy another, and your existing mortgage moves with you to the new property. The rate and the time remaining on your current term carry over for the ported balance.

Your closing dates matter. Most lenders allow only a limited window between the sale of your old home and the purchase of your new one for a port to work, and that window varies by lender and product. Miss the window and the mortgage is treated as broken, with any penalty that applies. See breaking your mortgage early: IRD and posted-rate penalties.

When does porting make the most sense?

Porting is usually strongest in three situations. Your current rate is better than what a new mortgage would offer today. You are well into a term but not close to renewal, so a break penalty could be meaningful. Or you want payment stability and your remaining term still fits your plans.

It is weaker when your renewal is near, when your current rate is not competitive, or when the new purchase requires so much new borrowing that the blended result no longer helps. Run the comparison both ways — port versus a fresh mortgage — before deciding. A Mortgage Renewal Check is a good framework for that math even mid-move. The alternative on timing is switching lenders at renewal instead of porting.

What is a blend-and-port, and how does it work?

If the new home costs more and you need a larger mortgage, many lenders offer a blend-and-port. The existing balance keeps your current rate for its remaining term, the new money is priced at current rates, and the two combine into one blended rate and payment.

Ask for the blended rate, the new term structure, and what happens at renewal in writing, then compare it against a completely new mortgage.

“Great rates, fast closing, and excellent customer service.” — Madhav Dhakal, Google review

Moving home and porting a mortgage in Edmonton — a home in Glenora

Credit: hobvias sudoneighm, via Wikimedia Commons (CC BY 2.0).

What are the qualification traps when the new home costs more?

Porting is a new approval, not a rubber stamp. The lender re-qualifies you on income, debts, and credit, and it appraises and approves the new property as security. A job change, new debt, or a property the lender will not accept can stop a port that looked simple on paper.

The extra borrowing in a blend is qualified as new debt as well. Buyers are often surprised that needing more money is the point where a port gets difficult — the larger the top-up, the more the file looks like a brand-new application, because it largely is.

What should you confirm before you list or offer?

Confirm four things early: that your mortgage is portable, how long your port window is, whether your sale and purchase dates can fit inside it, and what penalty you would pay if the port fails. Get those answers before conditions come off, not after. If the dates do not line up, see bridge financing when the buy and sell dates don’t line up.

If you are also a first-time buyer on the purchase side of a family move, the First Home Guide for Edmonton covers the approval steps that still apply. Planning the port and the purchase together avoids the most common timing surprises.

Thinking of moving and keeping your mortgage? Call me at (780) 722-5621 and we will check your port window, run the blend math, and compare it against starting fresh — before you list.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

Breaking a Mortgage Early: How IRD and Posted-Rate Penalties Work

General Travis Bannert 22 Oct

Breaking a closed fixed-rate mortgage early costs the greater of two numbers: three months’ interest, or the interest rate differential (IRD) — and when rates have fallen since you signed, the IRD is usually the bigger one. Variable-rate closed mortgages typically cost three months’ interest, and open mortgages can be repaid anytime without penalty, which is why they carry a higher rate. Before you list, refinance, or sign anything, get your lender’s exact payout figure — that number, not any estimate, governs. See three months’ interest vs IRD: which one applies to you.

Most borrowers are quoted a penalty only after they have committed to the move. Run the number first, and the decision — sell now or at renewal, refinance or wait — often changes.

How is a fixed-rate mortgage penalty calculated?

For a closed fixed-rate mortgage, the penalty is the greater of:

  • (a) Three months’ interest on your remaining balance at your contract rate, or
  • (b) The interest rate differential (IRD) — roughly, (your contract rate minus the lender’s current rate for your time remaining) × remaining balance × time remaining.

Whichever is larger is what you pay. Early in a term the IRD usually dominates; in the final months, three months’ interest often wins — which is why timing a move near renewal can save real money. If your renewal is close, start with a Mortgage Renewal Check before pricing any break.

Why are big-bank IRD penalties so much larger?

The comparison rate is the trap. Many big banks calculate the IRD using their posted rates rather than discounted rates. At signing you received a discount off the posted rate — and in the penalty calculation, that discount effectively inflates the differential between your contract rate and the comparison rate.

Monoline lenders, which do not publish the same posted-rate structure, typically produce a much smaller differential on an identical balance and timeline. The same homeowner can owe dramatically different penalties depending on which type of lender holds the mortgage — one of the strongest reasons to discuss penalty math before choosing a lender, through a Pre-Approval & Refinance Check, not just when leaving one.

“Great rates, fast closing, and excellent customer service.” — Madhav Dhakal, Google review

Edmonton mortgage penalty planning — skyline from Saskatchewan Drive in fall

What does an IRD penalty look like in real numbers?

Illustration only — arithmetic with round numbers, not a quote. Take a $400,000 balance, a 5.00% contract rate, a 3.50% comparison rate, and 3 years remaining:

  • Differential: 5.00% − 3.50% = 1.50%
  • IRD: 1.50% × $400,000 × 3 years ≈ $18,000
  • Three months’ interest: $400,000 × 5.00% ÷ 4 ≈ $5,000
  • Penalty = the greater of the two ≈ $18,000

Your lender’s calculation uses its own comparison term, exact days remaining, and posted-rate schedule, so your figure will differ — possibly by a lot. Use illustrations to understand the math, never to budget a payout.

How can you reduce or avoid the penalty?

  • Port the mortgage. Buying another home? Porting your rate and term to the new property can avoid the penalty entirely, subject to qualification and timing rules that vary by lender. See porting: the penalty-free way to keep your rate when you move.
  • Use prepayment privileges first. Before a planned sale, use your annual lump-sum and payment-increase privileges — commonly 10–20% per year, but they vary by lender, so confirm yours — to shrink the balance the penalty is calculated on.
  • Time it to renewal. A penalty with months remaining is far smaller than one with years remaining; sometimes a short delay changes the decision.
  • Get the exact payout statement. Only your lender’s figure governs. Ask for it in writing, note how long it is valid, and bring it to your broker before signing anything.

Another way to stay put is blend-and-extend: averaging today’s rate instead of breaking.

Thinking about breaking your mortgage? Call me with your lender’s payout figure and we will run the port, prepay, and wait options side by side. Call (780) 722-5621.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

Breaking a Mortgage Early in Canada: 3 Months’ Interest vs the IRD Penalty

General Travis Bannert 21 Oct

Breaking a mortgage early in Canada costs one of two penalties: on a variable-rate mortgage, typically three months’ interest; on a fixed-rate mortgage, the greater of three months’ interest or the interest rate differential (IRD). The IRD is the one that shocks people, because it can grow into the tens of thousands when rates have fallen since you signed. Before breaking a term for any reason, get your lender’s exact payout figure in writing — estimates, including mine, are a starting point, not the number.

Mortgage penalty math for an Edmonton home move — skyline from Saskatchewan Drive
Photo: Crisco 1492, via Wikimedia Commons (CC BY-SA 4.0).

How does the three months’ interest penalty work?

It is the simpler of the two. On many variable-rate mortgages, the prepayment penalty is three months’ interest on the balance you are paying out. On a $400,000 balance, that is commonly in the few-thousand-dollar range — real money, but often small next to what a move or a much lower rate can save.

That illustration is arithmetic, not a quote: your actual balance, rate and remaining term all feed the real number, which is why the written payout statement matters.

What is the IRD, and why can it be so large?

The interest rate differential compares your contract rate with the lender’s current rate for a term matching what you have left, and multiplies the difference across your balance and remaining time. Sign a five-year fixed at a higher rate, watch market rates drop, then break in year three — the lender’s lost interest is real, and the IRD passes it to you.

Lenders calculate IRD differently — some use posted rates rather than the discounted rate you actually pay, which can inflate the figure sharply. Nothing about the IRD is standardized, so two lenders can produce very different penalties on similar mortgages.

That is also why this decision belongs inside a Mortgage Renewal Check or a Pre-Approval & Refinance Check well before any move: the penalty is a known input to the math, not a surprise to absorb after.

What does an IRD penalty look like in real numbers?

Illustration only — arithmetic with round numbers, not a quote. Take a $400,000 balance, a 5.00% contract rate, a 3.50% comparison rate, and 3 years remaining:

Differential: 5.00% − 3.50% = 1.50%
IRD: 1.50% × $400,000 × 3 years ≈ $18,000
Three months’ interest: $400,000 × 5.00% ÷ 4 ≈ $5,000
Penalty = the greater of the two ≈ $18,000

Your lender’s calculation uses its own comparison term, exact days remaining, and posted-rate schedule, so your figure will differ — possibly by a lot. Use illustrations to understand the math, never to budget a payout.

“Knowledgeable, unbiased and he has access to many different strategies.” — Gerald Paquet, Google review

When does breaking a mortgage still make sense?

More often than the penalty headline suggests. Moving for work or family, separating and restructuring title (see Spousal Buyout Mortgages in Alberta), consolidating expensive debt, or dropping to a much lower rate can all outweigh the cost — what matters is the net picture over the time you will actually hold the new mortgage.

Also check your options before assuming a break: many mortgages are portable to a new property, and some allow a blend-and-extend that averages your old rate with current pricing. Both can avoid or shrink a penalty entirely.

Whatever the reason, the order of operations is fixed: written penalty figure first, full comparison second, decision third. Never sign a new commitment on the strength of an estimate.

How can you reduce the penalty before you break?

Two tactics the fine print allows. Use your prepayment privileges first: before a planned sale, use your annual lump-sum and payment-increase privileges — commonly 10–20% per year, but they vary by lender, so confirm yours — to shrink the balance the penalty is calculated on. And time the break to renewal where you can: a penalty with months remaining is far smaller than one with years remaining, so sometimes a short delay changes the decision.

Thinking about breaking your mortgage for a move, a refinance or a separation? Call me at (780) 722-5621 — I will try to call you this week, and if you reply with a good time, we can run your penalty and your options side by side first.

By Travis Bannert, Realtor and Mortgage Broker
Travis Bannert, Mortgage Broker | Next Door Mortgages, Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

Mortgage Renewal in 2026? Why Your Bank’s First Offer Is Rarely Its Best

General Travis Bannert 20 Oct

If your mortgage term started in 2021, it renews in 2026 — and the renewal letter your bank mails you is an opening offer, not their best one. Signing it without a comparison takes minutes and can cost you for the entire next term. A free renewal check before you sign tells you whether the offer is fair — and if it isn’t, a broker can shop your renewal across dozens of lenders, usually at no cost to you.

Why 2026 renewals deserve a second look: five-year terms taken in 2021 were priced in a very different rate environment. Your payment, your balance, and your options have all changed since then. Lenders know most homeowners sign the first letter out of convenience — which is exactly why that letter is rarely the sharpest rate they can offer.

What to check before you sign:

  • The rate itself — against what other lenders are offering for the same term
  • Prepayment privileges — can you pay extra without penalty if your income rises?
  • Portability — does the mortgage move with you if you sell and buy?
  • Penalties — what does it cost to break this term early if life changes?
  • Term length — does a shorter or longer term fit your actual plans better?

See renewing with a new lender: what a switch involves, step by step. On term length, see blend-and-extend: when averaging your rate helps. On portability, see porting your mortgage if the renewal coincides with a move.

Start early: rate holds run 90 to 120 days, so beginning the conversation about four months before your renewal date protects you if rates move while you decide. There is no downside to checking early — and the check itself is free.

Next Door Mortgages will review your renewal offer honestly: if your bank’s number is genuinely good, we’ll tell you to sign it. If it isn’t, we’ll show you the better option and handle the switch paperwork.

Call Next Door Mortgages at (780) 722-5621, or start with our Mortgage Renewal Check page. For the real estate side, call Travis Bannert at 780-720-8240 or visit bridgerealtygroup.ca.

By Travis Bannert, Realtor and Mortgage Broker