Who Is Exempt From the Mortgage Stress Test? Renewals, Switches and the Exceptions

General Travis Bannert 2 Nov

You are exempt from the mortgage stress test in two main situations: a straight renewal with your existing lender, and — since November 21, 2024 — a straight switch of your mortgage to a new lender at renewal, as long as the loan amount and amortization do not change. In almost every other situation, including a new purchase or a refinance, the stress test still applies in full.

The stress test rule, in brief

For federally regulated lenders, the stress test means you must qualify for your mortgage at a higher rate than the one you will actually pay. Your qualifying rate is the higher of your contract rate plus 2%, or the Bank of Canada benchmark rate.

The lender uses that qualifying rate to test your payments against your income and debts. You still make your real payments at your actual contract rate — the stress test is a qualifying hurdle, not a price.

Exemption 1: A straight renewal with your existing lender

If you simply renew your mortgage with the lender you already have, there is no new mortgage application — and no stress test.

Renewing extends your existing mortgage rather than creating a new approval, so you are not re-qualified. This is why your lender can send a renewal offer without asking for fresh income documents.

There is a catch. Because your lender knows you can renew without qualifying again, its first offer is not always its best. Posted rates are a starting point, and rates are sometimes negotiable — which is exactly why the second exemption matters.

Exemption 2: A straight switch to a new lender at renewal

Effective November 21, 2024, the Office of the Superintendent of Financial Institutions (OSFI) removed the stress test requirement for straight switches of uninsured mortgages to a new lender at renewal. A matching exemption applies to insured mortgages making a straight switch.

A “straight switch” has a precise meaning:

  • You move your existing mortgage to a different lender at renewal.
  • The loan amount stays the same — you do not borrow additional money.
  • The amortization stays the same — you do not extend your repayment timeline.

If those conditions are met, the new lender does not apply the stress test. You still go through an application and must meet the new lender’s own lending criteria — but the higher qualifying rate is not part of the process.

This changed the renewal conversation in Canada. Before the change, an uninsured borrower who could not pass the stress test at a new lender was effectively stuck with their current lender, whatever rate was offered. Now borrowers can genuinely shop at renewal. Travis works with multiple lenders offering different and sometimes more competitive products — contact us and we’ll shop across lenders for you.
Edmonton skyline mortgage stress test exemption renewal switch

Where the stress test still applies

The exemptions are narrow. The test still applies in these common situations:

New purchases. Buying a home requires full qualification under the stress test, alongside the standard minimum down payment rules: 5% on the first $500,000, 10% on the portion from $500,000 to $1,500,000 for an insured mortgage, and 20% down for an uninsured mortgage, with insured purchases capped at $1.5 million.

Refinances. If you borrow more money, access equity, or change your amortization, it is a refinance, not a straight switch, and you must qualify under the stress test.

Home equity lines of credit (HELOCs). A HELOC is new borrowing against your home, not a renewal or a switch, so stress test qualification applies.

The lenders the federal rules do not cover the same way

The stress test described here is a federal requirement for federally regulated lenders. Not every lender in Canada is federally regulated. Some credit unions are provincially regulated and follow their provincial regulator’s rules, which can differ. Private lenders operate under still different standards, often focusing more on the property and your equity than on a standardized qualifying rate.

That does not automatically make those options better. Their rates, fees, terms, and renewal conditions can differ significantly, and a mortgage that is easier to qualify for today can cost more later. The right question is not just “can I avoid the stress test?” but “what does this mortgage cost me over the full term?”

What this means at your renewal

You have three paths: renew with your current lender without a stress test, switch without a stress test if the switch is truly straight, or refinance with a stress test if you change the amount or amortization. Start several months before renewal and compare offers — since November 2024, the stress test is no longer a reason to skip that comparison.

Common questions

Q: If I renew with my current lender, do I ever have to pass the stress test?
A: Not on a straight renewal — there is no new application and no stress test. The test enters the picture only if you refinance or take out new borrowing such as a HELOC.

Q: Can I switch lenders at renewal without the stress test if my mortgage is uninsured?
A: Yes. Since November 21, 2024, OSFI has exempted straight switches of uninsured mortgages from the stress test, provided the amount and amortization stay the same. Insured straight switches have a matching exemption.

Q: What makes a switch “straight” — and what disqualifies it?
A: A straight switch moves your mortgage to a new lender at renewal with the same loan amount and amortization. Borrowing extra or extending the amortization disqualifies it — the transaction is then a refinance requiring stress test qualification.

Q: Does being exempt from the stress test mean automatic approval at a new lender?
A: No. The exemption removes only the higher qualifying rate. The new lender still reviews your application, credit, income, and debts, and you must meet its regular lending criteria.

Q: I want to switch lenders and take out a little extra for renovations. Am I exempt?
A: No. Increasing the loan amount makes it a refinance rather than a straight switch, so you will need to qualify under the stress test at the higher of your contract rate plus 2% or the Bank of Canada benchmark rate.

Q: Do credit unions and private lenders have to apply the stress test?
A: Not always in the same way. Some credit unions are provincially regulated and follow different rules, and private lenders set their own criteria — so compare the full cost, not just the qualifying hurdle.

Talk to a broker before you sign anything

Renewal is one of the few moments when the rules genuinely work in your favour — but only if you compare your options before signing your current lender’s first offer. Start with a mortgage pre-approval and renewal review through Next Door Mortgages, or call Travis Bannert at 780-720-8240 to check whether a straight switch could beat your renewal offer.

By Travis Bannert, Realtor and Mortgage Broker

— Travis Bannert, licensed Mortgage Broker with BFL Dominion Lending Centres
No Land Transfer Tax in Alberta: What Edmonton Buyers Save Before They Even Start

General Travis Bannert 2 Nov

Alberta charges no land transfer tax — no provincial tax, and no municipal tax on top of it. Edmonton buyers pay only comparatively small land titles registration fees, measured in the hundreds of dollars, where buyers in Ontario and British Columbia pay thousands, and often tens of thousands, in transfer taxes on the same home.

If you are moving to Edmonton from another province, this is one of the first pleasant surprises in the numbers. It is not a rebate or a program with eligibility rules — the tax simply does not exist here.

What Alberta buyers pay instead: registration fees

When a property changes hands in Alberta, the transfer is registered through the provincial land titles system. Buyers pay registration fees for the transfer of land and for registering a mortgage.

These fees are real closing costs, itemized by your lawyer, but they are measured in the hundreds of dollars — not a tax bill that rivals your moving costs. When people search for “land transfer tax Alberta” expecting a rate table, the honest answer is that there is no rate, because there is no tax.

How Ontario and BC compare

In Ontario, buyers pay a provincial land transfer tax on every purchase, and Toronto buyers pay a second, municipal tax on top — effectively taxed twice on the same transaction. First-time buyer rebates exist, but they are capped, carry eligibility conditions, and offset only part of the bill on a typical family home.

In British Columbia, buyers pay a provincial property transfer tax, with its own rates and exemptions. Partial relief exists for some first-time buyers and newly built homes, but it is relief from a tax Alberta buyers never face at all.

The result: an out-of-province buyer moving to Edmonton routinely saves five figures in closing taxes on a typical home, compared with buying the same-priced home in Toronto or much of BC.

Edmonton skyline and High Level Bridge

What that saving does to your mortgage file

More of your cash stays available for your down payment. In Canada, minimum down payments are 5% on the first $500,000 of the price, 10% on the portion from $500,000 to $1,500,000 for an insured mortgage, and 20% down for an uninsured mortgage, with insured purchases capped at $1.5 million. Cash preserved at closing can be the difference between meeting a down payment tier and missing it.

A larger down payment means less borrowed. Every dollar added to your down payment is a dollar you do not finance over 25 or 30 years — and 30-year amortizations are available to first-time buyers and on new builds. Less borrowed means smaller payments and less interest.

It can shrink your mortgage insurance premium. If your down payment is less than 20%, your mortgage requires default insurance, and the premium is a percentage of the mortgage amount, stepping down as your down payment share rises. Keeping five figures in your down payment instead of paying it in transfer tax can keep you in a lower premium tier — and even within the same tier, a smaller mortgage means a smaller premium.

Or it becomes your closing-cost and moving cushion. Some buyers are better served holding the savings back as a reserve for legal fees, moving costs, and the first months in a new city. In Alberta, that is your choice. In Ontario or BC, the tax is not optional.

What Alberta buyers do still pay at closing

No land transfer tax does not mean no closing costs. Edmonton buyers should still budget for:

  • Legal fees and disbursements — your lawyer handles the transfer, mortgage registration, and title work.
  • Land titles registration fees — the comparatively small provincial fees described above, generally in the hundreds of dollars.
  • Appraisal — your lender may require one, and the cost may fall to you.
  • Home inspection, title insurance, and property tax and utility adjustments — depending on your purchase.

Why this matters so much for people moving to Alberta

Relocation is a live theme in Edmonton housing. Buyers arrive from Ontario in particular and budget for an Alberta land transfer tax out of habit — only to find there is none.

If that is you, rebuild your numbers from scratch rather than recycling your Ontario budget. Your down payment goes further here and your closing costs are lighter. Posted rates are a starting point, rates are sometimes negotiable, and Travis works with multiple lenders offering different and sometimes more competitive products — contact us and we’ll shop across lenders for your file. And with the Bank of Canada having raised its policy rate to 2.50% on October 28, 2026, and big-bank prime having moved to 4.70% effective October 29, 2026, current numbers matter more than anything quoted before the move.

Common questions

Q: Does Alberta have a land transfer tax in 2026?
A: No. Alberta has no provincial land transfer tax, and its municipalities — including Edmonton — do not charge one either. Buyers pay land titles registration fees instead, generally in the hundreds of dollars.

Q: What do Edmonton buyers pay instead of land transfer tax?
A: Provincial land titles registration fees for the transfer and the mortgage, plus standard closing costs such as legal fees, a possible appraisal, title insurance, and property tax adjustments — small compared with transfer taxes in Ontario and BC.

Q: How much can I save buying in Edmonton instead of Toronto?
A: On a typical home, routinely five figures. Ontario charges a provincial land transfer tax and Toronto adds a second municipal tax on top, while Alberta charges neither.

Q: Does BC charge a transfer tax too?
A: Yes. British Columbia charges a provincial property transfer tax. Some first-time buyers and new-build buyers qualify for exemptions, but the tax applies broadly — unlike Alberta, where no equivalent tax exists.

Q: Can I put what I save on transfer tax toward my down payment?
A: Yes, and many relocating buyers do. Cash not spent on transfer tax stays available for your down payment, reducing what you borrow and potentially keeping you in a lower mortgage insurance premium tier.

Q: Are there any Alberta purchase taxes I should still budget for?
A: There is no land transfer tax, but budget for legal fees, registration fees, a possible appraisal, title insurance, and tax and utility adjustments. GST can also apply to newly built homes — separate from transfer tax, and worth confirming on a new build.

Talk to a broker before you sign anything

If you are buying in Edmonton — especially if you are relocating from a province with land transfer tax — rebuild your budget with a broker before you write an offer. Get started with a mortgage pre-approval through Next Door Mortgages, or call Travis Bannert at 780-720-8240 to see what your down payment can really do here.

By Travis Bannert, Realtor and Mortgage Broker

— Travis Bannert, licensed Mortgage Broker with BFL Dominion Lending Centres
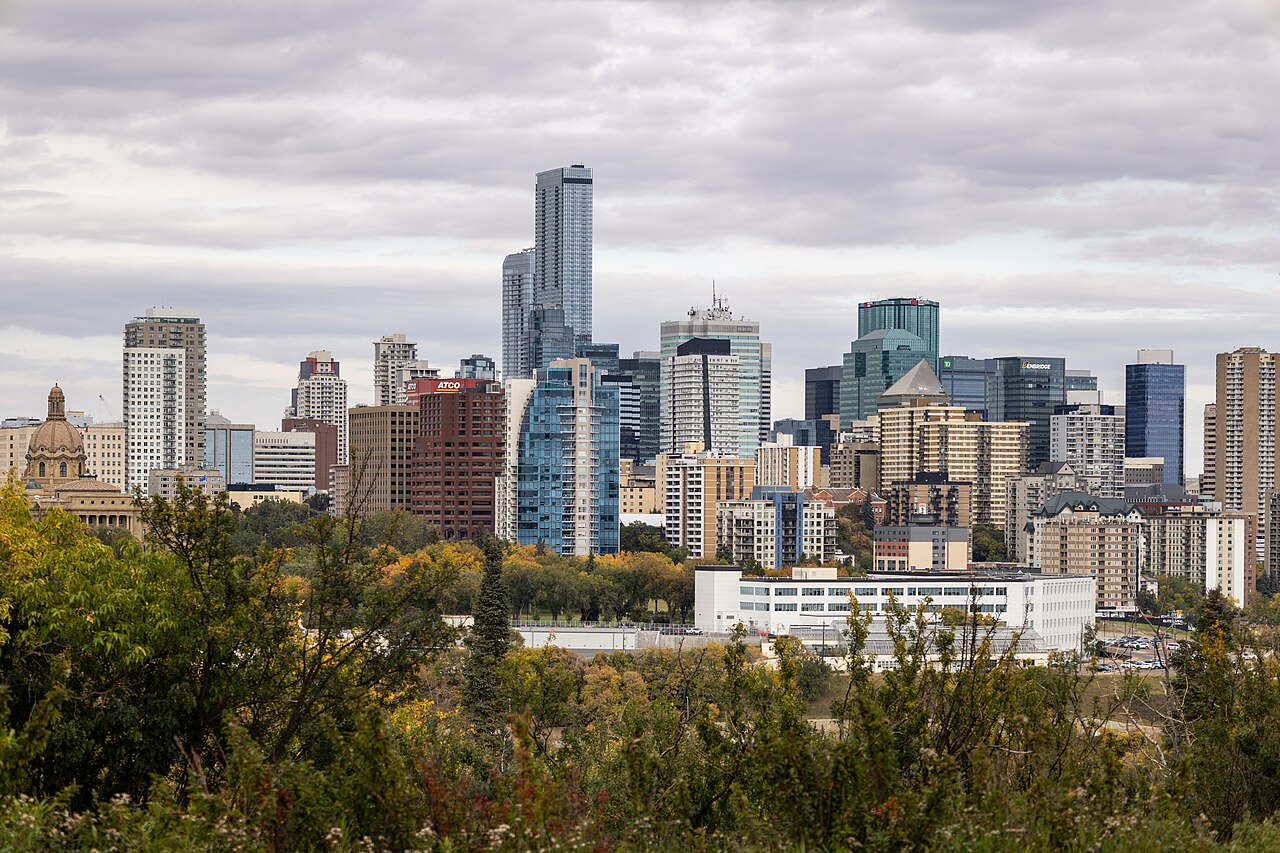
How Much Mortgage Can You Get on a $100,000 Salary in Alberta? Worked Numbers

General Travis Bannert 1 Nov

On a $100,000 salary in Alberta, with 5% down and no other debts, you can typically qualify for an Edmonton home around $375,000 — roughly a $370,000 mortgage once the insurance premium is added and the stress test does its work. Stretch to a 30-year amortization (available to insured first-time buyers and on new builds) and the ceiling rises to about $400,000. Save a 20% down payment and buy uninsured, and you’re shopping near $410,000. Here is every step of that math, so you can see exactly which lever moves your number.

Step 1: Your ratio budgets at $100,000

Lenders cap your housing costs as a percentage of gross income. On $100,000 a year, your gross monthly income is $8,333, which gives you these ceilings:

  • GDS 32% (classic guideline): $2,667/month for all shelter costs
  • GDS 35% (extended, insured files with strong credit): $2,917/month
  • TDS 39% (classic): $3,250/month for shelter plus all other debt payments
  • TDS 44% (extended, insured): $3,667/month

Shelter means the mortgage payment (at the qualifying rate, not your real rate), property tax, heating, and — for condos — half the condo fee.

Step 2: The stress test converts dollars into a payment

Under the federal stress test you qualify at the higher of your contract rate + 2% or the Bank of Canada benchmark (5.25% in recent years). On an example contract rate around 4.50% — an illustration, not a quote — you’d be tested at about 6.50%, which works out to roughly $670/month per $100,000 of mortgage over 25 years, or about $626/month per $100,000 over 30 years. The mechanics are in our mortgage stress test guide.

Edmonton skyline

Step 3: The worked example — $375,000 with 5% down

  • Price: $375,000, 5% down = $18,750
  • Base mortgage: $356,250
  • CMHC premium at 95% loan-to-value (4.00%): $14,250, added to the mortgage
  • Total mortgage tested: $370,500
  • Tested payment at 6.50% over 25 years: about $2,482/month
  • Property tax (Edmonton, this price range): about $281/month
  • Heating: about $150/month
  • Total shelter: about $2,913/month → GDS ≈ 35.0%

That lands exactly on the extended insured ceiling — approvable at a lender using 35/44 ratios with a strong file, and declined by one holding the classic 32% line. This is the first lesson of the $100K band: at this salary, which lender’s ratio set you get is worth tens of thousands of dollars of house.

Swap in the 30-year amortization and the tested payment on a $400,000 purchase ($395,200 total mortgage) falls to about $2,476/month — shelter of about $2,926, again right at 35%. So the longer amortization buys you roughly $25,000 more house, at the cost of more interest over the life of the loan — the trade-offs are itemized in the 25-year vs 30-year amortization guide.

Step 4: The 20%-down version

With 20% down there’s no insurance premium, but uninsured files are usually tested at the classic ratios. On a $410,000 purchase: mortgage $328,000, tested payment about $2,197/month, tax about $307, heating $150 — shelter of about $2,655, a GDS of about 31.9%. Inside the classic ceiling with room to spare. Notice the pattern: the bigger down payment bought a higher price, mostly by removing the premium, not a dramatically bigger mortgage.

Step 5: What a truck payment does at $100K

At this income the constraint quietly changes: the GDS binds first when you have no debts, but one vehicle payment flips the binding constraint to TDS. A $450/month truck payment eats the same TDS room as roughly $67,000 of mortgage. Add the truck and a card balance, and the realistic purchase range on this salary drops from ~$375,000 toward $300,000–$320,000. Run your own debts through the same machinery with our affordability worksheet before falling in love with a listing.

Two more notes at this band. First, lenders count two-year-averaged overtime, bonuses and — at many lenders — the Canada Child Benefit on top of salary, so your qualifying income may be higher than your base. Second, on price: posted rates are a starting point, rates are sometimes negotiable, and I work with multiple lenders with different and sometimes more competitive products — contact us and we’ll shop across lenders, because at $100K the difference between a 32% lender and a 35% lender is a different neighbourhood.

For rate context as of October 29, 2026: the Bank of Canada raised its policy rate to 2.50% on October 28, and big-bank prime moved to 4.70% on October 29 (dominionlending.ca was still showing pre-hike prime of 4.45% that morning — posted pages lag decisions, which is why live quotes matter more than posted pages).

Frequently asked questions

What mortgage can I afford on $100,000 a year in Alberta? With 5% down and no other debts, roughly a $370,000 mortgage — about a $375,000 Edmonton home over 25 years, or about $400,000 over a 30-year amortization. With 20% down, about a $410,000 purchase.

Why do different lenders give me different answers on the same salary? Because the ratio ceilings differ. An insured lender approving at 35% GDS / 44% TDS gives you roughly $25,000–$40,000 more house than one holding the classic 32% / 39% guidelines — before rate differences are even considered.

Does a $100,000 salary qualify for a $500,000 house? Not on salary alone with a small down payment — the tested shelter cost overshoots every ratio ceiling. It becomes possible with a much larger down payment, a co-borrower’s income, or additional qualifying income like two-year-averaged overtime.

Is the “4 to 5 times your income” rule right at $100K? Closer to 3.7 times at the stress test with 5% down. The multiple rises with a bigger down payment and falls with every monthly debt you carry.

Get your lender-by-lender number

At $100,000, the answer genuinely depends on which lender’s rulebook we use and what your other debts look like. Run your real figures through the free Pre-Approval & Refinance Check and I’ll calculate your ceiling across lenders — and tell you which lever moves it most. Call Travis Bannert, licensed Mortgage Broker with Next Door Mortgages, BFL Dominion Lending Centres, at 780-720-8240.

Want me to walk you through it? Call 780-720-8240 or register and I will call you — I will try to call you this week; reply with a good time.

By Travis Bannert, Realtor and Mortgage Broker
Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | 780-720-8240 | nextdoormortgages.com

Moving Your Mortgage to Alberta: Porting, Qualifying With a New Job, and What Lenders Need

General Travis Bannert 1 Nov

Your mortgage does not have to die because your postal code changed. Moving to Alberta from another province, you typically have three paths: port your existing mortgage to the new home, port it and increase it with the extra money blended in, or break it, pay the penalty, and borrow fresh. The right path is a math question — your rate, term, porting rules, and penalty size decide it, not habit. This guide covers the mechanics: how porting works, how lenders treat a brand-new Alberta job, and the document file to assemble before you list. For the general overview, see our Ontario-to-Alberta mortgage guide — this post is the deeper mechanics version for movers from any province.

Porting, explained: same mortgage, new house

Many Canadian mortgages are portable, which means you can move your existing rate, term, and balance from the home you sell to the home you buy. Typically, the port must happen within a window your lender sets after your sale — often 30 to 120 days — so the timing of your two closings matters as much as the numbers.

Porting is not automatic. Your lender re-qualifies you on the new purchase — income, debts, and credit are reviewed again — and it must approve the new property as well. The Alberta home also has to fall within the lender’s lending area: national lenders and broker-channel lenders lend in Alberta, but a smaller regional lender may not, so confirm before you fall in love with a house. One more caution: some low-rate and discount products restrict or prohibit porting entirely. Check the porting clause first — your mortgage may not travel with you.

Edmonton skyline

Port and increase: when the new home costs more

If the Alberta home costs more than your old balance covers, many lenders let you port the existing balance and add the increase on top. The increase is usually blended at current rates with your existing rate, or added as a second portion. Blending keeps things simple — one mortgage, one payment — but part of your money is priced at today’s rates while the ported part keeps your original deal. Whether the blended result beats breaking depends on the size of the increase, your remaining term, and the penalty. Run both scenarios side by side; blending wins surprisingly often when the increase is modest and the remaining term is long.

When breaking makes sense — and when it is a trap

Sometimes breaking is the right call: your porting window cannot line up with your closings, your lender will not lend on the new property, your product prohibits porting, or a fresh mortgage is enough better to outweigh the penalty. But breaking a fixed-rate mortgage can trigger a prepayment penalty, often calculated using an interest rate differential — a figure that can be far larger than movers expect. Variable-rate penalties are typically smaller, but they still belong in the math.

The rule is simple: get your exact penalty quoted, in writing, for a specific payout date, and run the port-versus-break comparison before you list your old home — not after you have a firm purchase depending on the answer. A penalty discovered mid-move has a way of becoming a penalty simply paid.

Qualifying with a new Alberta job

The question every relocating buyer asks: will a lender use income from a job I have barely started? Often, yes. Lenders can typically use new employment income when you provide an employment letter and a first pay stub, especially when the new job is in the same field as your previous work — a track record in the industry carries real weight. A probationary period is often acceptable to many lenders when the overall file is strong, though it is handled lender by lender.

Two situations need more care. Self-employed movers generally need a two-year income history, averaged, so bring your tax documents even if the business moves with you. Income from a job that has not started yet is handled case by case — a signed employment contract with a near-term start date helps considerably, but do not assume it qualifies until a lender has reviewed it. If your move involves a career change too, raise it at pre-approval, not after you have written an offer. Our newcomer mortgage guide covers the related document logic for buyers whose income history sits partly outside a lender’s usual view.

The document checklist

Assemble this file before the house hunt, and every step after it gets faster:

  • Government-issued identification
  • An employment letter setting out your salary, start date, and probation terms
  • A recent pay stub from the new job
  • Your most recent Notice of Assessment and T4, for income history
  • Down payment proof: typically 90 days of account history showing the source of funds
  • The sale documents for the home you are selling

Screenshots and partial statements slow files down. Full statements, in order, with any large deposits explainable, are what underwriters want to see.

Timing: rate holds and the right sequence

Rate holds for a pre-approval typically run 90 to 120 days, which shapes the smart sequence: get pre-approved before the house-hunting trip, not after it. A pre-approval confirms the lender is comfortable with your new-job income, your porting plan, and the price range — and it holds a rate while you shop. Line the porting window up with both closings, because a port that expires between the two deals can quietly become a break you never budgeted for. When you are ready, the Pre-Approval & Refinance Check is where we open the file.

A note on the rates themselves: posted rates are a starting point; rates are sometimes negotiable. Travis works with multiple lenders through BFL Dominion Lending Centres, whose products are sometimes more competitive than a single bank’s posted offer. Contact us and we will shop across lenders for you — that comparison matters even more on a port-and-increase, where the blended figure is built from whatever rate the increase is priced at.

Frequently asked questions

Can I port my mortgage to a home in another province? Often, yes — many Canadian mortgages are portable across provinces, provided the new property falls within your lender’s lending area. National and broker-channel lenders lend in Alberta. Your lender re-qualifies you and must approve the new property, and the port usually has to complete within a set window after your sale, often 30 to 120 days.

What happens if the new home costs more than my current mortgage? Many lenders offer a port-and-increase: your existing balance keeps its rate and term, and the extra amount is blended at current rates or added as a second portion. Compare the blended result against breaking and borrowing the full amount fresh — the better answer depends on the penalty and how much extra you need.

Can I qualify for a mortgage with a new job in Alberta? In many cases, yes. Lenders can often use new employment income supported by an employment letter and a first pay stub, particularly when the job is in the same field as your previous work, and probation is often acceptable when the file is strong. Self-employed movers generally need a two-year income history, and not-yet-started jobs are assessed case by case.

Should I break my mortgage instead of porting it? Only when the math says so. Breaking a fixed-rate mortgage can trigger a prepayment penalty, often based on an interest rate differential, which can be substantial. Get the penalty quoted in writing and compare the total cost of breaking against porting — including any blended increase — before you list your current home.

Move the mortgage properly, not hopefully

Port, blend, or break — each is right for somebody, and the wrong one can cost thousands. Before you list, run your numbers through the Pre-Approval & Refinance Check or call Travis Bannert, licensed Mortgage Broker with BFL Dominion Lending Centres at Next Door Mortgages, at 780-720-8240. And for the house side of the same move — neighbourhoods, process, and possession — start with Bridge Realty Group’s Moving to Alberta hub.
By Travis Bannert, Realtor and Mortgage Broker
Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | 780-720-8240 | nextdoormortgages.com

The 32/39 Rule: GDS and TDS Ratios Explained With a Real Edmonton Budget

General Travis Bannert 31 Oct

The 32/39 rule is the lender’s budget test: your housing costs should stay under 32% of your gross income (the GDS ratio), and housing plus all your other debt payments should stay under 39% (the TDS ratio). Pass both, and the income side of your application works. Fail either one, and the mortgage shrinks until you pass.

These two percentages quietly decide more Edmonton approvals than any other numbers in the file. Here’s exactly how they’re calculated — with a real budget.

GDS: the housing-cost ratio

Gross Debt Service ratio = (mortgage payment + property tax + heating cost + 50% of condo fees) ÷ gross monthly income

Key details borrowers miss:

  • The mortgage payment is calculated at the stress-test qualifying rate, not your actual rate — the higher of your contract rate + 2% or the 5.25% benchmark. That’s why our mortgage stress test explainer matters to this math: https://nextdoormortgages.com/general/mortgage-stress-test-explained-qualifying-rate-edmonton/
  • Property tax is your actual annual tax divided by 12 — in Edmonton, roughly $260–$330/month on a mid-priced detached home.
  • Heating is usually a standardized estimate, commonly $100/month for a house.
  • Only half of condo fees count in GDS — but as the worked example below shows, half is still plenty.

TDS: the everything ratio

Total Debt Service ratio = (all GDS costs + every other debt payment) ÷ gross monthly income

“Every other debt payment” means the minimum or contractual payments on car loans and leases, credit cards (assessed at 3% of the balance, not your actual payment), student loans, lines of credit (typically assessed at 3% of balance too), and any support payments. Lenders don’t use what you usually pay — they use their formula, and the formula is not generous.

The worked Edmonton budget

Meet our example buyers: a household earning $110,000/year ($9,167/month gross), no debts, looking at a $450,000 Edmonton detached home with 10% down.

  • Mortgage: $405,000 + CMHC premium (2.80% at 90% LTV ≈ $11,340) ≈ $416,340
  • Tested payment at a 6.50% qualifying rate (example): about $2,790/month
  • Property tax: about $300/month
  • Heat: $100/month
  • GDS total: $3,190 ÷ $9,167 = 34.8%

Against the classic 32% rule, this file fails. Against the extended ratios insurers allow on strong insured files (35% GDS / 44% TDS), it passes. Same house, same income, same buyers — the rulebook decides. Now add a $480/month vehicle payment:

  • TDS total: ($3,190 + $480) ÷ $9,167 = 40.0%

That busts the classic 39% TDS but fits the extended 44%. This is the single most common pattern I see in Edmonton: a household that qualifies for the house, right up until the truck payment enters the spreadsheet.

Edmonton skyline from Saskatchewan Drive

Photo via Wikimedia Commons

Now the condo version — where fees bite

Same $110,000 household, now buying a $290,000 apartment condo with 10% down and $390/month condo fees.

  • Mortgage: $261,000 + premium ≈ $268,300; tested payment about $1,797/month
  • Property tax: about $185/month; heat: $50/month (smaller unit)
  • Condo fees in GDS: 50% × $390 = $195/month
  • GDS total: $2,227 ÷ $9,167 = 24.3% — passes easily

Cheaper homes leave ratio room to spare, which is why condo files so often survive a car payment that kills a detached file. Run the same condo at a $72,000 income ($6,000/month) and GDS jumps to 37% — a fail almost everywhere. Price-to-income fit is the whole game.

Are 32/39 hard rules?

They’re guidelines with documented flexibility, and the flexibility has rules of its own:

  • Insured mortgages (less than 20% down) with a credit score of 680+ can be approved up to 35/44 by the insurers. Below that credit score, you’re held closer to the classic numbers — one more reason the down payment and credit file interact, as covered in how much down payment you need in Canada: https://nextdoormortgages.com/general/how-much-down-payment-canada-insured-uninsured/
  • Uninsured mortgages (20%+ down) are underwritten lender by lender; strong files with big equity sometimes stretch slightly past 39% TDS, weak ones get cut below it.
  • B lenders publish higher ratio ceilings — sometimes 50%+ TDS — priced accordingly.

What never flexes: the direction. Every dollar of monthly debt payment you carry is a dollar that can’t go to housing, at roughly a 150-to-1 exchange rate against mortgage size (a $100/month payment ≈ $15,000 of mortgage at today’s qualifying rates, as an example calculation).

Three moves that fix a failed ratio

  1. Kill the smallest debts first. A $95/month store-card payment blocks about $14,000 of mortgage. Paying it off entirely beats adding the same cash to your down payment, almost every time.
  2. Re-shop the property taxes. On the same income, a home with lower taxes (newer Edmonton subdivisions vs. some mature areas can differ by $1,000+/year) quietly raises what you qualify for.
  3. Pick the lender whose rulebook fits. Ratio ceilings, condo-fee treatment, and line-of-credit assessment vary. Posted rates are a starting point and rates are sometimes negotiable — but the lender with the best rate and the wrong ratio treatment still says no. I work with multiple lenders precisely so your file goes to the rulebook that fits it, and we’ll shop your rate across them once it does.

Check your own two numbers

Bring your income, your debts, and a target price to our free Pre-Approval & Refinance Check: https://nextdoormortgages.com/pre-approval-refinance-check/ and I’ll run your exact GDS and TDS — at the classic and extended ratios — and tell you which lenders your budget passes today. Call Travis Bannert, Mortgage Broker with Next Door Mortgages, BFL Dominion Lending Centres, at 780-720-8240.

FAQ

What is a good GDS and TDS in Canada? The classic underwriting targets are 32% GDS and 39% TDS. Insured files with credit scores of 680+ can often be approved up to 35% and 44%. Lower is always safer — and cheaper in life, not just on paper.

Do lenders use my actual mortgage payment in the ratios? No. They use your payment calculated at the stress-test qualifying rate — contract rate + 2%, or the 5.25% benchmark, whichever is higher. Your tested payment is higher than your real one.

Why does only half my condo fee count? Because part of a condo fee covers things like exterior insurance and reserves that aren’t personal shelter costs. Lenders split the difference at 50% — but on a high-fee building, that half can still decide the file.

Can I be approved if I’m slightly over 39% TDS? Sometimes, on an insured file with strong credit (up to 44%) or an uninsured file with large equity. “Slightly over” is a lender-selection problem, not an automatic no — which is why the file should be shopped, not surrendered.

Want me to walk you through it? Call Travis Bannert at 780-720-8240 — I will try to call you this week; reply with a good time and we will set a phone appointment to run your exact GDS and TDS before you shop.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | 780-720-8240 | nextdoormortgages.com

Photos via Wikimedia Commons.

The Bank Hiked on a 2% Growth Forecast. StatsCan Just Said 1.3%. What That Changes Before December 9

General Travis Bannert 31 Oct

Two days after the Bank of Canada raised its policy rate to 2.50%, Statistics Canada reported that Canada’s economy did not grow at all in August — the second flat month in a row — and likely shrank slightly in September. Preliminary third-quarter growth is tracking at 1.3% annualized, well below the roughly 2% the Bank projected in the Monetary Policy Report it published alongside the hike. For Edmonton borrowers, that gap is now the whole December 9 story: the Bank hiked to fight inflation, but it did so into an economy that is barely growing.

Canada GDP — Statistics Canada, released Oct. 30, 2026

Real GDP, August 2026 Essentially unchanged (expected +0.2%)
Sectors that expanded 9 of 20
Retail trade / manufacturing / construction +1.2% / +0.3% / +0.2%
Wholesale trade / public sector / utilities −1.4% / −0.2% / −0.4%
September advance estimate −0.1%
Preliminary Q3 growth (annualized) 1.3% — vs the Bank of Canada’s ~2% projection; Q2 was 3.3%
Official September / Q3 figures November 30, 2026

Source: Statistics Canada, Gross Domestic Product by Industry, August 2026, released October 30, 2026.

Edmonton skyline and High Level Bridge

Photo via Wikimedia Commons

Why this release matters more than most

GDP reports usually change nothing for a household. This one lands in the middle of a live rate decision. The Bank of Canada raised rates on October 28 because inflation is running near 3% and it expects it to stay there through most of 2027. But its own forecast assumed the economy would grow about 2% in the third quarter. The first hard data since the decision says 1.3% — and the details are not an Alberta collapse story: construction still grew, manufacturing grew for the fifth time in seven months, and Alberta’s drag was scheduled oil sands maintenance in the north, not a housing or jobs downturn. The weakness was concentrated in wholesale trade, a winding-down census in the public sector, and utilities.

That mix matters because it gives the Bank a reason to pause in December without admitting the October hike was wrong — and it gives borrowers a genuine two-way risk to plan around instead of a one-way escalator.

What it changes for your mortgage before December 9

If you hold a variable-rate mortgage: your rate follows the Bank’s policy rate, and prime is 4.70% today. A soft economy makes a second consecutive hike on December 9 harder to justify — but inflation near 3% makes a cut unlikely too. Plan for prime to stay where it is, know your trigger rate if your payment is fixed, and treat any December surprise as a bonus or a manageable cost — not as your plan.

If you are choosing fixed vs variable right now: fixed rates are priced off bond yields, not the policy rate, and bond markets read releases like this one within hours. Weak growth data can soften fixed pricing slightly even while the Bank holds — which is why the rate you are quoted this week may differ from last week’s in either direction. This is a week to have a live quote on your actual file, not to shop from a posted-rate table.

If you renew in the next six months: do not wait for December 9 to start. Rate holds typically protect a rate for 90–120 days while you decide, and starting the renewal conversation now costs nothing. If December brings a hold, you renew calmly; if it brings another hike, you already hold pricing.

If you are buying this fall: get or refresh your pre-approval at today’s numbers. A pre-approval at prime 4.70% with the stress test applied is a real budget; a budget built on September’s rates is not.

Posted rates are a starting point, not the final word. Rates are sometimes negotiable depending on the person and the situation, and we work with multiple lenders who offer different products and sometimes more competitive rates than any single posted table shows. Contact us and we will shop across lenders for your file — call Travis Bannert at 780-720-8240. Any rate quoted for your file is based on an application and lender approval — it is confirmed only when a lender reviews your full application.

Run your numbers through the Pre-Approval & Refinance Check: https://nextdoormortgages.com/pre-approval-refinance-check/ — that page is the fastest way to sign up for a review of what you qualify for, what documents you need, and what your payment would look like at today’s rates.

Frequently asked questions

What did Statistics Canada report about Canada’s GDP? Real GDP was essentially unchanged in August 2026 — the second consecutive flat month — missing expectations of a 0.2% gain. The advance estimate for September is a 0.1% decline, putting preliminary third-quarter growth at 1.3% annualized, below the Bank of Canada’s roughly 2% projection. Official figures arrive November 30.

Does weak GDP mean the Bank of Canada will cut rates in December? Not necessarily. The Bank raised its policy rate to 2.50% on October 28 because inflation is near 3%. Weak growth makes another hike harder to justify, but a cut would require inflation to cooperate. The realistic planning case for December 9 is a hold — with risk on both sides.

When is the next Bank of Canada rate decision? December 9, 2026. Statistics Canada’s official September and third-quarter GDP figures land November 30, nine days before the decision, and will be one of the last major data points the Bank sees.

Should I lock in a fixed rate before December 9? It depends on your file, not the headline. Fixed rates move with bond yields and can ease on weak growth data even if the Bank holds. The right move is a live quote and a rate hold on your actual application — call 780-720-8240 and we will run both the fixed and variable scenarios on your numbers.

Want me to walk you through it? Call Travis Bannert at 780-720-8240 — I will try to call you this week; reply with a good time and we will set a phone appointment to review your rate hold, your renewal, or your pre-approval before December 9.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | 780-720-8240 | nextdoormortgages.com

Photos via Wikimedia Commons.

Ontario Mortgage Arrears Are Climbing Into 2027. Alberta’s Are Falling. CMHC Just Said So.

General Travis Bannert 30 Oct

Mortgage stress in Canada is regional, not national — and Alberta is on the stronger side of it. In its Fall 2026 Residential Mortgage Industry Report (released October 27, 2026), CMHC reported that arrears have declined in Alberta and Saskatchewan and are expected to remain stable through mid-2027, while Ontario’s arrears rate hit 0.32% in the second quarter of 2026 and is projected to record the largest and most sustained increase in the country. CMHC’s own summary: “Canada is not facing a broad mortgage crisis.”

Ontario arrears, Q2 2026 0.32% (up from 0.21% a year earlier)
Ontario outlook Largest, most sustained increase through mid-2027
Alberta and Saskatchewan Arrears have declined; expected stable through mid-2027
B.C. and Atlantic Canada More moderate rise expected

Source: CMHC Fall 2026 Residential Mortgage Industry Report, Oct. 27, 2026. Arrears = payments 90 days or more past due.

What is driving the split

CMHC ties Alberta’s improvement to stronger economic conditions and higher energy prices — the same energy prices behind the inflation pressure that pushed the Bank of Canada to raise its policy rate to 2.50% on October 28. Ontario’s pressure is concentrated in the Greater Toronto and Hamilton Area and southwestern Ontario, where trade tensions are affecting manufacturing, including the automotive sector, and housing conditions are softer. In other words: the national headline is an average of two very different regional stories, and Edmonton borrowers live in the steadier one.

Edmonton skyline from Saskatchewan Drive

Photo via Wikimedia Commons

What this means if you have — or want — an Edmonton mortgage

If you are renewing: a stable regional arrears picture does not lower your renewal rate, but it does mean Alberta lenders are not pricing in a regional distress wave. Your renewal is still a negotiation — get competing offers instead of signing the first letter.

If you are buying, including moving to Alberta: lenders qualify you on your income, debts, and the property — not on Ontario headlines. If you are relocating from the GTA, do not assume Ontario’s market stress follows you; your Alberta file is assessed on Alberta conditions and your own numbers.

If you are struggling anywhere: arrears are counted at 90 days past due, but help works best at day one. Lenders have relief options — payment deferrals, amortization changes, and other arrangements — that are far easier to arrange before a payment is missed than after three are. Regional strength is not a reason to wait if your own budget is tight.

Posted rates are a starting point, not the final word. Rates are sometimes negotiable depending on the person and the situation, and we work with multiple lenders who offer different products and sometimes more competitive rates than any single posted table shows. Contact us and we will shop across lenders for your file — call Travis Bannert at 780-720-8240. Any rate quoted for your file is based on an application and lender approval — it is confirmed only when a lender reviews your full application.

Run your numbers through the Pre-Approval & Refinance Check: https://nextdoormortgages.com/pre-approval-refinance-check/ — that page is the fastest way to sign up for a review of what you qualify for, what documents you need, and what your payment would look like on the homes you are actually watching in Edmonton and across Alberta.

Frequently asked questions

What did CMHC’s Fall 2026 report say about Alberta mortgage arrears? That arrears have declined in Alberta (and Saskatchewan) amid stronger economic conditions and higher energy prices, and are expected to remain stable through mid-2027.

What is Ontario’s mortgage arrears rate? 0.32% in the second quarter of 2026, up from 0.21% a year earlier, for mortgages 90 days or more past due. CMHC projects Ontario will record the largest and most sustained increase through mid-2027, concentrated in the GTHA and southwestern Ontario.

Is Canada facing a mortgage crisis? No, according to CMHC. Its deputy chief economist said directly that “Canada is not facing a broad mortgage crisis” — the stress is concentrated in specific regions, mainly parts of Ontario.

Does Alberta’s stronger arrears picture change my mortgage approval? Not directly. Approvals turn on your income, debts, credit, and the property. What the regional picture does is remove a layer of background risk — Alberta files are not being assessed against a backdrop of rising local defaults.

Want me to walk you through it? Call Travis Bannert at 780-720-8240 — I will try to call you this week; reply with a good time and we will set a phone appointment to review your renewal, your move to Alberta, or a payment problem before it becomes an arrears statistic.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | 780-720-8240 | nextdoormortgages.com

Prime Is 4.70% Now: What Changed on Your Variable Mortgage This Week (and Why TD Borrowers Pay 4.85%)

General Travis Bannert 30 Oct

Prime is 4.70% after the Bank of Canada’s October 28, 2026 hike to 2.50% – except at TD, which posts 4.85%. If your variable payment is fixed, more of it now goes to interest and you are closer to your trigger rate; if it adjusts, your payment just went up. Here is the math on an Edmonton mortgage.

Canada’s prime rate is now 4.70%, effective October 29, 2026 — up from 4.45% — after the Bank of Canada raised its policy rate to 2.50% on October 28. If you hold a variable-rate mortgage or a HELOC in Edmonton, your borrowing cost changed this week automatically. If you are with TD, check your statement carefully: TD’s separate mortgage prime — the rate its variable mortgages are actually priced on — is now 4.85%, not 4.70%.

Bank of Canada policy rate 2.25% → 2.50%, effective Oct. 28, 2026
Big-bank prime rate 4.45% → 4.70%, effective Oct. 29, 2026
TD mortgage prime rate 4.60% → 4.85%, effective Oct. 29, 2026

Source: Bank of Canada decision, Oct. 28, 2026; big-bank prime announcements reported by Canadian Mortgage Professional (Oct. 29, 2026) and Canadian Mortgage Trends (Oct. 28, 2026).

Edmonton skyline and the High Level Bridge

Photo via Wikimedia Commons

Who feels this, and how

Adjustable-payment variable mortgages: your payment rose with prime. On a standard amortization, a quarter-point rise adds roughly $13–$14 a month per $100,000 you owe — an illustration, not a quote; your lender’s statement is the exact number for your file.

Fixed-payment variable mortgages: your payment did not change, but more of each payment now goes to interest and less to principal, so your amortization stretches. If your payment no longer covers the interest owing, you approach your trigger rate — the point where the lender can require a payment increase, a lump sum, or a conversion. This is the group that needs to check numbers this week, not next month.

HELOCs and lines of credit priced off prime: interest cost rose the same quarter point, immediately.

Fixed-rate mortgages: nothing changed on your current term. Fixed rates are priced off bond yields, not prime, and your payment is locked until renewal.

Why TD borrowers pay 4.85%

TD prices its variable-rate mortgages off a separate “mortgage prime” that sits 15 basis points above its standard prime. When prime moved to 4.70%, TD mortgage prime moved to 4.85%. The discount in your mortgage contract (for example, “prime minus 0.50%”) is calculated off that 4.85% figure if you are a TD mortgage client — which is why comparing discounts across lenders without asking which prime they use can mislead you by exactly this gap.

What to do this week

  1. Find your current rate and which prime it follows. Your lender app or latest statement shows it. If you do not know whether your payment is adjustable or fixed, that is the first question to answer.
  2. If you are on a fixed-payment variable, ask for your current amortization and trigger rate in writing. Those two numbers tell you whether you need to act now or simply monitor.
  3. If you renew in the next 12 months, start the conversation now. Renewal pricing is being set in a rising-rate environment for the first time in over three years; waiting for your bank’s renewal letter is not a strategy.
  4. Do not panic-convert to fixed on a headline. Converting locks today’s fixed pricing and can carry costs and trade-offs. Run both scenarios on your actual balance and remaining term first.

Posted rates are a starting point, not the final word. Rates are sometimes negotiable depending on the person and the situation, and we work with multiple lenders who offer different products and sometimes more competitive rates than any single posted table shows. Contact us and we will shop across lenders for your file — call Travis Bannert at 780-720-8240. Any rate quoted for your file is based on an application and lender approval — it is confirmed only when a lender reviews your full application.

Run your numbers through the Pre-Approval & Refinance Check: https://nextdoormortgages.com/pre-approval-refinance-check/ — that page is the fastest way to sign up for a review of what you qualify for, what documents you need, and what your payment would look like at today’s prime.

Frequently asked questions

What is Canada’s prime rate today? 4.70% at the six big banks, effective October 29, 2026, up from 4.45%, following the Bank of Canada’s October 28 decision to raise its policy rate to 2.50%.

Why is TD’s mortgage prime 4.85% when prime is 4.70%? TD uses a separate mortgage prime rate to price its variable-rate mortgages, set 15 basis points above its standard prime. TD variable mortgage discounts are calculated off the 4.85% figure.

How much does a 0.25% prime increase add to my payment? On an adjustable-payment variable mortgage, roughly $13–$14 per month per $100,000 owed on a standard amortization — an illustration only. Fixed-payment variable borrowers see no payment change, but more of each payment goes to interest.

When is the next Bank of Canada decision? December 9, 2026. A BMO economist quoted this week noted the first hike in over three years “may not be its last” — future decisions depend on inflation and growth data, so variable borrowers should know their trigger rate before December, not after.

Want me to walk you through it? Call Travis Bannert at 780-720-8240 — I will try to call you this week; reply with a good time and we will set a phone appointment to review your variable, your trigger rate, or your upcoming renewal.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | 780-720-8240 | nextdoormortgages.com

How Rental Income Counts When You Qualify for a Mortgage in Canada

General Travis Bannert 30 Oct

The short answer

Yes, rent counts — but it counts the way the insurer and lender define it, not the way the listing advertises it. For an owner-occupied purchase in Canada, the mortgage insurers (CMHC, Sagen, and Canada Guaranty) each publish an approach to rental income, and they are not all the same approach. Under CMHC’s published rental-income framework, an owner-occupied two-unit property that is the subject of your application can use up to 100% of gross rental income added to your qualifying income; an owner-occupied three- or four-unit property (and non-owner-occupied two-to-four-unit properties) uses either up to 50% of gross rental income, or a net rental income calculation (gross rents minus operating expenses). Sagen’s published investment-property approach uses 50% of gross rental income, with the property’s taxes and heat excluded from the debt-service calculation, and the rent validated by lease agreements or an appraiser’s market-rent opinion.

Which approach applies to your file — and which insurer and lender produce the strongest approval — is exactly the kind of thing a broker sorts out before you write an offer. This post explains the machinery: the two calculation approaches, how unit count changes the treatment, what documents prove the rent, and the down-payment rules that come with multi-unit purchases.

Prepared by Travis Bannert, licensed Mortgage Broker with BFL Dominion Lending Centres. 780-720-8240.

1. The two approaches: gross add-back vs net rental income

Every rental-income calculation in Canadian insured lending is a version of one of these two ideas:

The gross rental income approach (add-back). A defined percentage of the property’s gross rent is added to your gross annual income, and the full carrying costs of the property (principal, interest, taxes, heat — “PITH”) are counted in your debt-service ratios. The percentage and the details are set by the insurer’s published rules. CMHC’s reference framework permits up to 100% of gross rent for an owner-occupied two-unit subject property, and up to 50% for owner-occupied three- and four-unit properties and non-owner-occupied two-to-four-unit properties. Sagen’s published investment property program uses 50% of gross rental income in the borrower’s income, with taxes and heat excluded from the debt-service calculation under that program.

The net rental income approach. Instead of adding a percentage of rent to your income, the calculation works the property’s own math: gross rents minus operating expenses equals net rental income, which is then added to (or, if negative, deducted from) your income side of the ratios. CMHC’s framework offers this as an alternative to the 50% gross approach for three- and four-unit owner-occupied and for non-owner-occupied properties.

Why two approaches exist: they reward different properties. A property with low operating expenses can look better under the net approach; a property with strong gross rents but ordinary expenses can look better under an add-back. A broker runs your actual property both ways where the insurer permits a choice.

One more distinction that matters: rental income from a property not part of this application (a rental you already own) is treated under a separate branch of the same frameworks — typically the net rental income approach — and your existing properties’ full carrying costs enter the picture. Bring the whole portfolio to the first conversation, not just the new purchase.

2. Unit count changes the rules

For the property you’re buying, the number of units drives both the rental treatment and the down payment:

  • Two units, owner-occupied (a duplex, or a house with a suite): CMHC’s framework allows up to 100% of gross rental income from the rented unit to be added to your qualifying income. This is the most generous treatment in the system, and one reason the suited-house purchase qualifies so differently from a single-unit purchase at the same price.
  • Three or four units, owner-occupied: up to 50% of gross rental income, or the net rental income approach — the file uses the permitted approach that fits the property.
  • Two to four units, not owner-occupied (pure investment): the 50% gross or net rental approaches apply, and the purchase requires at least 20% down (insured investment programs such as Sagen’s start at 20% down), because mortgage default insurance for high-ratio purchases requires owner occupancy.
  • Down payment minimums (federal rules, insured mortgages): for owner-occupied properties, 5% of the first $500,000 plus 10% of the portion above that, up to the $1.5 million insured price cap, for one- and two-unit properties; a flat 10% minimum for three- and four-unit owner-occupied properties. At or above $1.5 million, the purchase can’t be insured and needs at least 20% down. (Financial Consumer Agency of Canada / Department of Finance Canada rules; insured cap of $1.5 million in effect since December 15, 2024.)

All insured and uninsured approvals still run through the federal stress test — you qualify at the higher of your contract rate plus 2% or the benchmark floor rate (5.25% under Sagen’s published program terms, consistent with the federal framework). Rental income helps your ratios; it doesn’t exempt you from them.

3. What proves the rent

Insurers and lenders don’t take the seller’s word for rental income. Expect some combination of:

  • Signed lease agreements for tenanted units, showing the actual contracted rents.
  • An appraiser’s market-rent opinion (the economic rent schedule in the appraisal) — used especially for vacant units, newly created suites, or where existing rents look off-market. Sagen’s published program explicitly validates income using leases or fair market rent from an appraisal.
  • Rent history where available — deposits and records supporting that the stated rent is real.

Practical consequences: a vacant unit gets qualified at appraised market rent, not at the rent you hope to achieve; a long-term tenant paying below market is qualified at the lease, not at what the unit “should” rent for; and a brand-new suite with no history leans on the appraiser’s number. Run your qualification math on the provable rent, and treat anything above it as upside, not plan.

4. Does the suite have to be legal for the rent to count?

Treat the honest answer as: legality can matter, and it is much easier to deal with before the offer than after. Lenders and insurers underwrite the property they’re lending on; a rented unit that is part of the application invites questions about whether the property complies with municipal requirements, and individual lenders apply their own policies on suites that lack permits. There is no single published national rule that answers this identically for every lender and insurer — which is precisely why the property’s permit file should be reviewed during your condition period, with your financing condition still protecting you.

What is certain: a permitted, inspected suite is never a financing problem, an insurance problem, or a resale problem. A non-permitted one can be all three — and the buyer who discovers that after conditions come off owns it.

5. How to structure a house-hacking application properly

  1. Choose the insurer/lender combination for the property, not by habit. The same duplex can produce different approvals depending on which published rental approach applies (up to 100% gross on a two-unit under CMHC’s framework vs a 50% program elsewhere) and how a given lender overlays its own rules.
  2. Run both permitted calculations where the framework offers a choice (50% gross vs net rental) using the property’s real expense figures.
  3. Qualify on provable rent: leases for tenanted units, appraised market rent for vacant ones.
  4. Match the down payment to the unit count (Section 2) and keep the stress test in the math from the first estimate.
  5. Keep the financing condition until the property checks out — permits, appraisal (including the rent schedule), and insurer approval all land inside that window.

This is broker work in the truest sense: one property, several published rulebooks, and an answer that depends on matching them correctly. Call 780-720-8240 with the property you’re considering — before you write the offer.

Common questions

Q: Can I use rent from a basement suite to qualify for my mortgage?
A: Yes. On an owner-occupied two-unit property (a house with a suite is two units), CMHC’s published rental-income framework allows up to 100% of the gross rental income from the rented unit to be added to your qualifying income, with the property’s full carrying costs counted in your ratios. Individual lenders apply the framework alongside their own policies, and the rent has to be provable — by lease or by an appraiser’s market-rent opinion. The suite’s permit status can also matter; see Section 4.

Q: How is rental income treated on a triplex or fourplex I’ll live in?
A: Under CMHC’s framework, an owner-occupied three- or four-unit property uses either up to 50% of gross rental income added to your income, or a net rental income approach (gross rents minus operating expenses). Your broker runs the permitted calculation that fits the property’s actual numbers. The minimum down payment for an owner-occupied three- or four-unit purchase is 10%, under the federal insured-mortgage rules.

Q: What’s the difference between the gross add-back and the net rental approach?
A: The gross approach adds a set percentage of the property’s rent (up to 100% for an owner-occupied two-unit property under CMHC’s framework; up to 50% in the other insured categories) to your annual income, and counts the property’s full mortgage payment, taxes, and heat in your ratios. The net approach instead calculates the property’s own bottom line — rents minus operating expenses — and adds that net figure to your income (or deducts it if negative). Different properties win under different approaches, which is why the calculation is run both ways where the insurer allows a choice.

Q: I’m buying a rental I won’t live in. How does the rent count then?
A: Non-owner-occupied two-to-four-unit purchases use the 50% gross or net rental approaches under the insurers’ frameworks — Sagen’s published investment property program, for example, uses 50% of gross rental income with taxes and heat excluded from the debt-service calculation, requires at least 20% down, validates rent through leases or appraised market rent, and requires a general assignment of rents and leases. Conventional (uninsured) lender programs each set their own rental methodology on top of that.

Q: What down payment do I need for a duplex or fourplex?
A: Under the federal insured-mortgage rules: for an owner-occupied one- or two-unit property, 5% of the first $500,000 of the price plus 10% of the portion above that, up to the $1.5 million insured price cap. For an owner-occupied three- or four-unit property, a flat 10% minimum. At $1.5 million or above, or for a property you won’t occupy, at least 20% down. Every case still qualifies under the federal stress test.

Q: The suite in the house I want isn’t permitted. Will the rent still count?
A: It’s lender- and insurer-specific — there’s no single published national rule, and some lenders’ policies are stricter than others about non-permitted suites. The safe sequence is to keep your financing condition in place until the property’s permit file has been checked and your lender has confirmed its position on that specific property. A permitted suite is never a problem; discovering a non-permitted one after you’re firm can be. Call 780-720-8240 to structure the conditions properly before you write.

Travis Bannert, Licensed Mortgage Broker | BFL Dominion Lending Centres (Edmonton). Buying a suited home or a 2–4 unit property? Start with the qualification math: Mortgage Pre-Approval or call 780-720-8240.

General information only — not mortgage advice for your specific file. Insurer frameworks summarized from CMHC’s published rental income reference and Sagen’s published Investment Property Program (as of Oct 2026) and federal down payment rules via the Financial Consumer Agency of Canada; lender policies vary and all figures are confirmed at application. Rates and program terms change without notice.

The Mortgage Side of a Posting: Pre-Approval Before the House-Hunting Trip

General Travis Bannert 30 Oct

The short answer

On a posting, the mortgage is the schedule. Your house-hunting trip (HHT) is a few days long, your change-of-strength date is fixed, and your household goods move once. A mortgage that is “probably fine” is not fine — the pre-approval has to be a documented, lender-reviewed file before the HHT, built on your actual posting income documents, with a plan for the home you’re leaving: port the mortgage, sell first, or bridge the gap deliberately.

That is the work of this post: what a posted member’s pre-approval really involves, which income documents lenders ask for on a posting, how porting works when the posting orders the move, and how buying in Edmonton before the sale at the old base closes gets structured without gambling.

Prepared by Travis Bannert, licensed Mortgage Broker with BFL Dominion Lending Centres — also a licensed Realtor® in Alberta, so your purchase timeline and your mortgage timeline get planned as one file. 780-720-8240.
1. Why the pre-approval comes before the HHT

A civilian buyer can pre-approve loosely and fix things over a few weekends of shopping. A posted member can’t:

  • The HHT is a decision trip. You arrive with a shortlist and leave — ideally — with an accepted offer. An offer written on a soft pre-approval (a rate hold and a five-minute conversation) can collapse at the financing condition when the lender sees the full file for the first time.
  • The financing condition is short. Posting purchases run on tight condition windows. A fully documented pre-approval means the lender is reviewing the property during that window, not discovering your income structure.
  • Your file has posting-specific features (below) that are routine — but only if they’re presented properly the first time.

A documented pre-approval means: income verified from documents, down payment sourced and seasoned as required, debts and the property you’re leaving properly accounted for, and a rate hold in place. Anything less is a guess with a rate attached.

2. Income documentation for a posted member

CAF pay is stable, salaried income — lenders like it. The work is in documenting the posting correctly:

  • Your posting message / assignment documentation, showing the new posting location and the timeline. It establishes that the move is an employment relocation, not a resignation.
  • Current pay documentation from DND (pay statements / employer confirmation through the usual CAF channels) showing rank, component, and current pay — including which allowances form part of your regular compensation.
  • Allowances need care. Posting-related and location-related allowances (for example, allowances tied to a specific posting location) may end or change when you move. Lenders qualify you on income that will actually exist in Edmonton — expect questions about which pay components continue after the move, and don’t build the budget on an allowance that stops at the new base.
  • A spouse’s income counts where it’s verifiable and continuing — a spouse leaving a job at the old base and hoping to find one in Edmonton is a different underwriting conversation than a spouse transferring or working remotely. Have it early and honestly.
  • The standard file still applies: government ID, recent pay documentation, down payment history (typically three months of statements showing the funds’ source), and your existing property and debt details.

Get this package assembled the week the posting message arrives — not the week of the HHT.

3. Porting your mortgage on a posting

If you have a mortgage on the home at your current base, porting — moving the existing mortgage, rate, and term to the Edmonton purchase — is often the first option to price out:

  • How it works in general terms: your lender approves the new property and your continued qualification, the mortgage amount transfers (and can often be increased with a blend if the Edmonton home costs more), and you avoid the prepayment penalty that breaking the term would trigger.
  • The catches are timing and portability windows. Lenders set a window between the sale of the old home and the purchase of the new one for a port to complete. Posting timelines — COS dates, HHT scheduling, possession dates at two bases — have to be mapped against that window at the start, not discovered in the middle.
  • Not every mortgage is portable, and not every port is the best deal. If your current rate is well above today’s market, breaking and paying the penalty can occasionally win — occasionally. That comparison is a calculation with your actual penalty figure, not a hunch. Get the payout penalty in writing from your current lender and run both paths side by side.
  • Selling after you buy changes the structure. If the Edmonton purchase closes before the old home sells, a straightforward port may not be available and the plan may involve bridge financing or a different product entirely (next section).

4. Buying in Edmonton before the home at the old base closes

This is the most common posting stress point: possession dates at two bases that don’t line up. The structured options:

  • Sell first, buy second (the calm default). A firm sale at the losing end fixes your net proceeds and your porting/bridge window. Interim housing in Edmonton is a cost — but a known, bounded one.
  • Bridge financing covers the gap when you own both properties briefly: a short-term loan against the equity in the old home, repaid when it closes. Lenders generally want a firm, unconditional sale on the existing home to approve a bridge — a listing is not a sale. Bridge terms, limits, and costs are lender-specific.
  • Buy with a longer possession in Edmonton, timed behind your sale — works when sellers can accommodate it, and removes the overlap entirely.
  • What not to do: write a firm Edmonton purchase that only works if an unlisted (or freshly listed) home sells on schedule at an assumed price. Posting timelines punish optimism. If the plan needs the sale, sequence the sale first.

5. The Edmonton purchase itself: posting-specific notes

  • Remote signing is workable but not casual. Alberta closings can be signed through your Alberta lawyer using current remote-signing practices, but under Law Society of Alberta rules your lawyer must verify (not just identify) a remote client’s identity using an approved method, and lenders impose their own verification requirements. Start the identity step early — it is the most common last-minute scramble on posting files.
  • Alberta closing costs are comparatively light: no land transfer tax; Land Titles registration fees under the tariff in effect Oct 1, 2026 are $50 plus $5 per $5,000 of value for the transfer and the same formula for a mortgage registration. Legal fees, inspection, and appraisal are the other ordinary lines.
  • Buy for the next posting too. Mainstream product in high-demand areas protects you when this posting ends — your broker and realtor conversation should include resale, not just approval. (Travis holds both licences; the two conversations happen together: 780-720-8240.)
  • Relocation benefits are your file’s business. Which real-estate and mortgage-related costs your relocation file covers — and any requirements around service providers — are set by the Canadian Armed Forces Relocation Directive and administered through SIRVA (files authorized on or after January 6, 2026) or BGRS (earlier files), per canada.ca. Confirm coverage and requirements through your relocation coordinator before assuming any cost is reimbursable.

6. Your posting mortgage checklist

  1. Posting message received → start the mortgage file immediately (documents in Section 2).
  2. Get a documented pre-approval — income verified, down payment sourced, the old property accounted for.
  3. Price the three paths for the old home’s mortgage: port, break-and-restart (with the written penalty figure), or bridge across an overlap.
  4. Map the lender’s porting/bridge windows against your COS and possession dates.
  5. Complete the identity-verification groundwork for remote signing early.
  6. Arrive at the HHT with the pre-approval done — the trip is for choosing the house.

Common questions

Q: When should I start the mortgage process for a posting?
A: The week the posting message arrives. A documented pre-approval — income verified, down payment sourced, your existing property and its mortgage properly accounted for — has to be finished before the house-hunting trip, because the HHT is a decision trip and the financing condition window after it is short. Starting early also leaves time to price porting against breaking your current term with real figures.

Q: What income documents does a posted member need?
A: Your posting/assignment documentation, current CAF pay documentation showing rank and pay, ID, three months of down-payment history, and details of your existing property and debts. Expect questions about which pay components continue at the new posting — allowances tied to your current location may not follow you, and lenders qualify you on the income that will exist in Edmonton. A spouse’s income is documented the same way, with an honest picture of whether it continues after the move.

Q: Can I port my mortgage when I’m posted?
A: Often, yes — porting moves your existing rate and term to the new property and avoids a prepayment penalty. The constraints are your lender’s porting window (the allowed gap between selling the old home and buying the new one) and re-qualification on the new property. If your current rate is above today’s market, breaking can occasionally be cheaper even after the penalty — that’s a calculation using your written penalty figure, which you should request from your current lender early.

Q: What if my Edmonton purchase closes before my old home sells?
A: That’s what bridge financing is for: a short-term loan against your old home’s equity, repaid when it closes. Lenders generally require a firm, unconditional sale on the existing home to approve a bridge, and terms vary by lender. The safer default for most posting files is sequencing — firm sale first, then the Edmonton purchase — or negotiating a longer Edmonton possession so the overlap disappears.

Q: Do I have to use a specific mortgage broker under the relocation program?
A: Your relocation file is governed by the Canadian Armed Forces Relocation Directive, administered through SIRVA for files authorized on or after January 6, 2026, and BGRS for files authorized before that date (per canada.ca). Any requirements or covered-cost rules in your file are set by the program — confirm them with your relocation coordinator. What you want in a broker on a posting is someone who works posting timelines, prices the port-vs-break comparison properly, and coordinates with the purchase itself. Call 780-720-8240.

Q: Why does it help that my broker is also a Realtor®?
A: Because a posting purchase fails at the seams between the two transactions — possession dates, condition deadlines, porting windows, and a sale at another base all interact. Travis Bannert is a licensed Mortgage Broker with BFL Dominion Lending Centres and a licensed Realtor® with Bridge Realty Group, Maxwell Progressive Realty, so the Edmonton offer strategy and the mortgage structure are planned as one file instead of two. Call 780-720-8240 before your HHT, not during it.
Posted to CFB Edmonton? Start with the mortgage file before the house-hunting trip — begin with the Pre-Approval & Refinance Check or call Travis Bannert, Licensed Mortgage Broker | BFL Dominion Lending Centres, at 780-720-8240.

Travis Bannert, Licensed Mortgage Broker | BFL Dominion Lending Centres (Edmonton). Posted to CFB Edmonton? Start with the mortgage file: call 780-720-8240.

General information only — not mortgage advice for your specific file, and not a statement of relocation entitlements. Relocation benefits and provider requirements are set by the Canadian Armed Forces Relocation Directive and your individual file; SIRVA/BGRS status as of Oct 2026 per canada.ca. Mortgage products, porting and bridge terms vary by lender and are confirmed at application.