Debt Consolidation Into a Mortgage in Canada: When the Math Works and When It Doesn’t

General 25 Oct

Consolidating high-interest debt into a mortgage works when three things are true at once: the new total payment is genuinely lower after all costs, you have a plan that keeps the cleared cards from refilling, and the penalty and fees to restructure do not eat the savings. It fails when it only stretches short-term debt across a 25-year amortization — the rate falls, but the total interest can rise, and unsecured debt becomes debt secured by your Edmonton home. Run the full comparison, not the payment comparison alone.

What are the actual routes to consolidate?

At renewal, a refinance or switch-plus-increase can absorb the debts with no penalty. Mid-term, a refinance triggers a prepayment charge — three months’ interest on most variable mortgages, and the greater of three months’ interest or the interest rate differential on most fixed mortgages — which must be priced first. Alternatives include a HELOC or home-equity loan for part of the debt, keeping the first mortgage untouched. I compare those structures in HELOC vs home equity loan vs refinance.

How do you run the honest math?

List every debt: balance, rate, minimum payment. Total the interest you would pay clearing them on your current path — aggressively, over two to three years if cash flow allows. Then total the consolidation path: new mortgage interest on the added balance over the years you will actually carry it, plus penalty, legal and appraisal costs. Consolidation wins when its total is lower AND your monthly cash flow improves enough to stay out of new debt. If the cards refill, you end with both debts — the classic failure mode, and the reason a consolidation plan includes closing or freezing the consolidated lines where the lender requires it and your budget demands it.
Edmonton homeowners reviewing mortgage consolidation

Photo via Wikimedia Commons.

What will lenders require?

You must qualify for the larger mortgage under the stress test, with the debts being paid out counted until they are actually discharged — brokers structure the payout through the lawyer so the new ratios are the ones assessed. You will generally need sufficient equity: refinances are capped at 80% of the home’s value. Start with the Pre-Approval & Refinance Check; if you are instead approaching renewal, the Mortgage Renewal Check times the move to avoid a penalty entirely.

“Travis talked us out of consolidating mid-term because the penalty ate the savings — and set the plan for our renewal instead. That honesty saved us thousands.” — Google review excerpt

Want the full-math comparison on your debts? Call (780) 722-5621 — I will try to call you this week, or reply with a good time and we will set a phone appointment to run both paths honestly.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
How Parents Can Help With a Down Payment: Gift, Loan, Co-Sign or Guarantor

General 24 Oct

Parents can help with a first home four distinct ways — an outright gift, a documented loan, co-signing the mortgage, or guaranteeing it — and lenders treat each one differently. A gift adds to the down payment without adding debt; a loan adds a payment to your ratios; a co-signer adds their income and their liability; a guarantor adds strength without going on title. Choosing the wrong structure is the most common way family help accidentally weakens an application.

How does each structure change the application?

A gifted down payment needs a signed gift letter confirming the money is not repayable, plus a paper trail showing the funds moving into the buyer’s account — lenders verify both. If the money is actually a loan, it must be declared as one: the repayment amount enters your debt ratios, and disguising a loan as a gift is misrepresentation, not strategy. A co-signer becomes a co-borrower — their income helps qualification, their debts count too, and they share legal liability for the mortgage and usually a place on title. A guarantor backs the loan without the same title position, used when the buyers’ income is close and a parent’s strength closes the gap. See gifted down payment rules: the lender’s paperwork.

Which help fits which problem?

Match the help to the actual gap. Short on down payment but comfortably qualifying on income? A gift is cleanest. Short on qualifying income but strong on savings? Co-signing or a guarantee addresses the ratio problem a gift cannot. Parents who want the money to remain a family asset — or who are helping several children — may prefer a registered loan with real terms, accepting the ratio cost openly. In Edmonton, where the standard condo median sits at $207,700 and detached at $529,600 (Q3 2026, Royal LePage), the size of the gap — and therefore the right structure — differs enormously by target property. See FHSA vs the Home Buyers’ Plan for the buyer’s own savings.

“He would get back to me with an answer to my questions in no time… Very professional and kind.” — Aniela Lesyk, Google review

Edmonton family home bought with parental down payment help

Photo via Wikimedia Commons.

What should the family settle before any money moves?

Who is on title, what happens if the buyers separate or sell early, whether the help is an advance on inheritance or separate from it, and how siblings are treated — written down, with independent legal advice for the parents. Money should move only after the structure is chosen and the broker confirms how the lender wants it documented; a transfer that lands before the paperwork exists creates the source-of-funds questions that delay funding. The First Home Guide for Edmonton covers where gifted funds sit in the overall purchase sequence.

Planning a purchase with family help and want the structure set before money moves? Call me at (780) 722-5621 and we will choose gift, loan, co-sign, or guarantee on the real numbers. See the first-time buyer journey the parents are funding. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Costs Beyond the Down Payment: Closing Costs Edmonton First-Time Buyers Forget

General 24 Oct

Beyond the down payment, Edmonton buyers need closing funds for legal fees and disbursements, land title registration, an appraisal where required, a home inspection, property tax and utility adjustments, and CMHC insurance taxes where applicable — and lenders commonly check that you hold roughly 1.5% of the purchase price for closing costs on top of your down payment. Buyers who budget only the down payment discover these costs in the worst week of the process: the one before possession. See how much house you can afford once closing costs are in the math.

What are the main items, in the order you will meet them?

The inspection comes first, during your condition period, paid directly to the inspector. The appraisal, if your lender requires one, is arranged during financing and sometimes deducted at funding. Legal fees and disbursements are settled with your lawyer before possession and include the land titles registration of the transfer and mortgage — Alberta’s registration fees are calculated on the property value and mortgage amount, so they scale with price. Adjustments reimburse the seller for prepaid property taxes or condo fees beyond possession day, and a tax account or utility deposits may be required depending on the property and your providers. On insured mortgages, the provincial sales tax on the CMHC premium where it applies is due at closing and cannot be added to the mortgage — a line item that surprises buyers who assumed the whole premium was financed. On a new build, GST on a new home: the closing cost that isn’t in most budgets. For the premium itself, see CMHC premiums and the tax charged on them.

Why does the 1.5% check matter to your approval?

Because it is part of the approval, not just budgeting advice: lenders verify funds to close — the down payment plus closing costs, sourced with the same paper trail as the down payment itself. Money that appears late, moves between accounts without explanation, or sits in someone else’s name triggers the same source-of-funds questions as the down payment does. Keep closing funds in the same documented accounts, and do not spend the buffer on furniture before funding.

“Great rates, fast closing, and excellent customer service.” — Madhav Dhakal, Google review

Edmonton buyers budgeting closing costs and funds to complete

Photo via Wikimedia Commons.

How much should an Edmonton first-time buyer actually set aside?

Use the verified anchors you have: your lawyer’s written estimate, your lender’s appraisal requirement, and the property’s tax and condo-fee position — then hold the 1.5% guideline as the floor, not the ceiling, especially on older homes where immediate post-possession work is likely. The First Home Guide for Edmonton sequences these costs against the rest of the purchase, and if you are refinancing or renewing instead, run a Mortgage Renewal Check — closing-cost logic applies there too, and it is where switch costs are often covered or not.

Want your full funds-to-close number — down payment plus every closing item — before you start touring? Call me at (780) 722-5621 and we will build it line by line. Or follow the first-time buyer journey, with closing day at the end, or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
How Much House Can a First-Time Buyer Afford in Edmonton? A Worksheet Approach

General 24 Oct

How much house you can afford is set by two ratios lenders use — your housing costs as a share of gross income, and all your debts as a share of gross income — tested at the stress-test qualifying rate, not the rate you will actually pay. A worksheet that runs those ratios on your real numbers gives you a price range you can trust more than any calculator’s single answer. See the stress test, explained before you run the worksheet.

What goes on the worksheet?

Line one is gross household income — the income your lender can document. Line two is the housing-cost ratio (GDS): mortgage payment calculated at the qualifying rate, plus property taxes, heating, and half of any condo fee, should generally stay within about 39% of gross income for insured files. Line three is the total-debt ratio (TDS): everything in line two plus car payments, cards, lines of credit, and student loans, generally within about 44%. Line four is your actual down payment and closing funds, because the ratios test the payment — and the payment depends on how much you borrow, over what amortization. See 25 vs 30 years: what amortization does to the worksheet. See the down payment rules behind the worksheet’s first line.

Why does the qualifying rate change the answer so much?

Because the stress test qualifies you at the higher of your contract rate plus 2% or the Bank of Canada benchmark. On the same income, the home you qualify for at the test rate is meaningfully smaller than the home your actual payment would suggest — deliberately. It also means small debts punch above their weight: a car payment consumes TDS room dollar for dollar against the mortgage it displaces, which is why paying down a vehicle loan before applying sometimes unlocks more house than adding the same cash to the down payment.

“This has been the best customer service experience I’ve had in Canada over the past five years.” — Minsang Lee, Google review

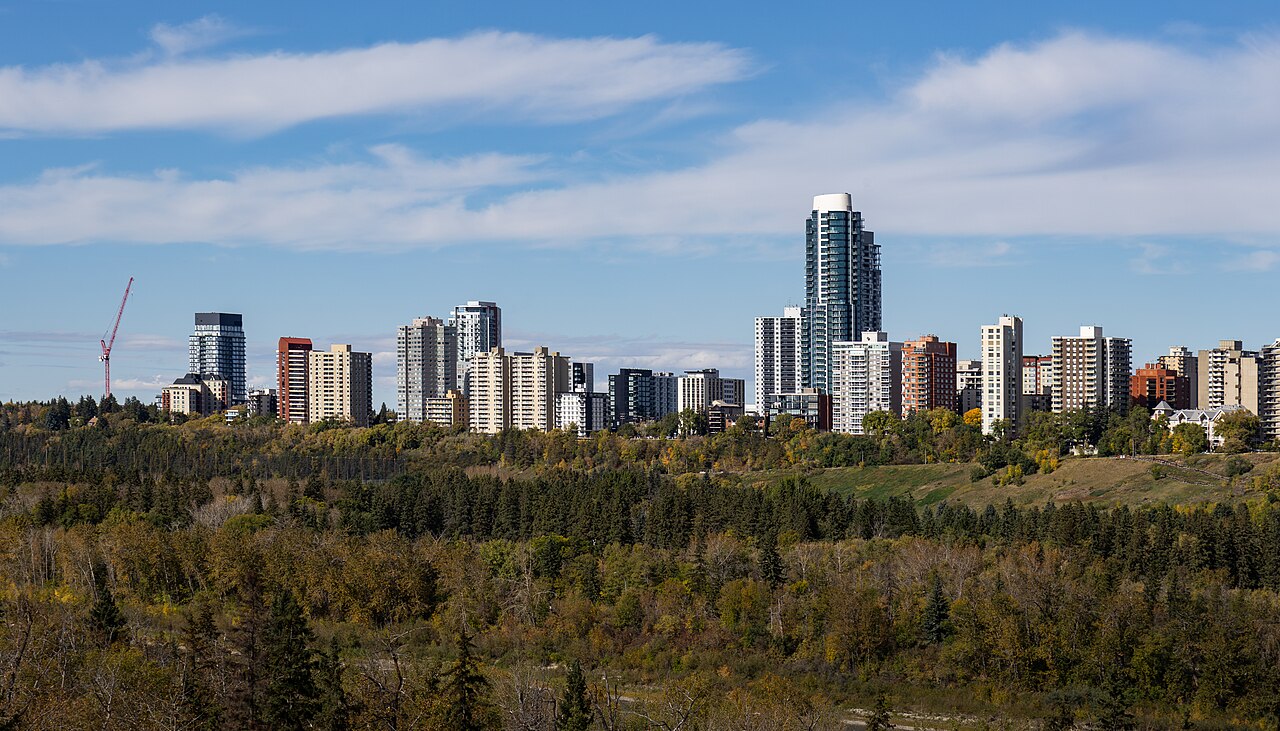
Edmonton first-time buyers building an affordability worksheet

Photo via Wikimedia Commons.

What does the worksheet say in Edmonton terms?

Anchor it to real prices: Royal LePage put Edmonton’s Q3 2026 detached median at $529,600 and the standard condo median at $207,700. Run your ratios at both price points and the worksheet stops being abstract — you see whether your income supports detached, where the condo-to-house gap sits, and what changes it: a larger down payment, a paid-off debt, a co-borrower, or a longer amortization where you qualify for one. The First Home Guide for Edmonton walks the purchase steps that follow once the number is real.

Want the worksheet run on your actual income and debts — not a website estimate? Call me at (780) 722-5621 and we will build your real price range together. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Cash-Back Mortgages in Canada: Who Pays for the “Free” Money?

General 23 Oct

You pay for a cash-back mortgage — through a higher interest rate over the full term, and through a clawback that can demand part of the cash back if you leave the mortgage early. For a borrower who will stay the full term and genuinely needs the cash for the home, it can still be a rational tool; for everyone else, the “free” money is usually the most expensive money in the file.

How does a cash-back mortgage work?

The lender gives you a percentage of your mortgage amount as cash at funding, on top of the mortgage itself. In exchange, your rate is higher than the same lender’s best rate for that term. The difference seems small as a percentage; multiplied by your balance and five years of payments, it commonly totals more than the cash you received — which is the business model, and it is not hidden, just rarely added up out loud.

What is the clawback?

If you break the mortgage before the term ends — selling, refinancing, or switching — the lender typically requires repayment of a pro-rata share of the cash back, on top of any interest penalty that applies. That double cost is why cash-back mortgages punish exactly the people most likely to move early: first-time buyers whose lives change fastest. If there is a realistic chance you will not finish the term, the clawback math belongs in your decision from day one. Also note open vs closed: the flexibility a cash-back term usually gives up.

“Mei is very detail-oriented, efficient, and managed to secure me a great rate.” — Kani Lo, Google review

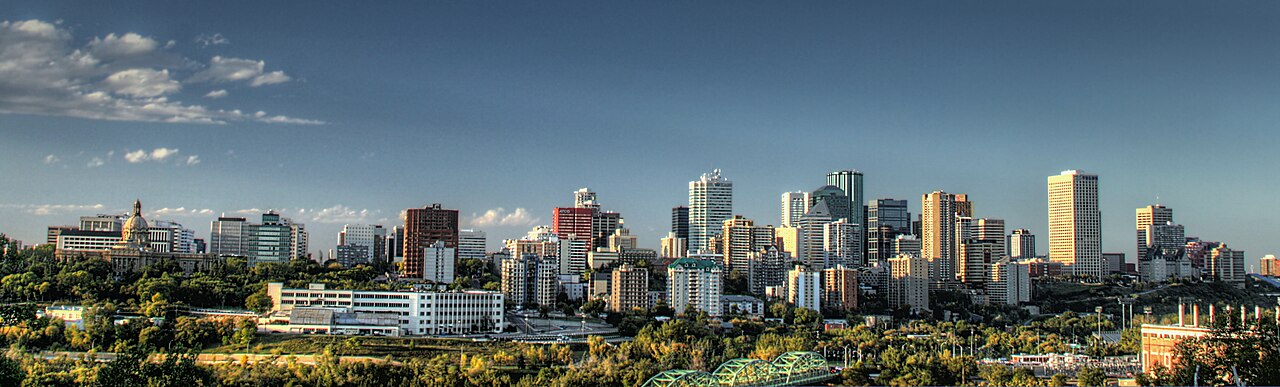
Edmonton mortgage borrower comparing cash-back costs

Photo via Wikimedia Commons.

When can cash-back still make sense?

When the cash funds something essential to the purchase — furnishing a first home, or necessary immediate repairs — you have compared the total cost against alternatives like a smaller purchase-plus-improvements structure or saving longer, and you are confident you will stay the full term. It never makes sense as spending money, and it cannot be used to manufacture a down payment: lenders require your minimum down payment to come from your own verifiable resources under the applicable rules. For cheaper ways to the same cash, see HELOC vs equity loan vs refinance: cheaper ways to the same cash.

Compare any cash-back offer against the lender’s best-rate version of the same mortgage, in total dollars over the term. If you are renewing, a Mortgage Renewal Check runs that comparison on your file; first-time buyers should read the First Home Guide for Edmonton before signing any “free money” offer.

Offered cash back with a mortgage? Call me at (780) 722-5621 and we will add up what it actually costs before you decide. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
HELOC vs Home Equity Loan vs Refinance in Canada: Three Ways to Borrow Against Your Home

General 23 Oct

A HELOC gives you revolving credit you can draw and repay repeatedly, a home equity loan gives you one lump sum at a fixed structure, and a refinance replaces your mortgage with a larger one — all three borrow against your home, but they differ in rate type, flexibility, and what happens if your plans change. Choosing by the shape of your spending, not just the rate, is what keeps the cheapest option from becoming the most expensive one. For the no-payment alternative, see reverse mortgages: the no-payment equity option for 55+.

How does a HELOC work in Canada?

A home equity line of credit is revolving credit secured by your home, usually at a variable rate tied to prime. You draw what you need, pay interest on what you have drawn, and can repay and redraw within the limit during the draw terms your lender sets. Combined HELOC-and-mortgage products have regulatory limits on the total secured borrowing relative to your home’s value, and your lender will confirm your specific limit. A HELOC suits costs that arrive in stages — a renovation with progress payments is the classic example — because you only pay interest on money actually out the door.

How is a home equity loan different?

It is a separate loan for a set amount, with a set payment schedule — closer to a second mortgage in structure. You get certainty of payment and usually a fixed structure in exchange for giving up the redraw flexibility: once repaid, that money is not available again without a new application. It suits one defined cost with a known total.

When does a full refinance beat both?

When your existing mortgage rate is uncompetitive, when you want one payment instead of two or three, or when the amount you need is large enough that mortgage pricing beats line-of-credit pricing by enough to cover the refinance costs — legal fees, appraisal, and any penalty to break your current term early. That penalty check is not optional: breaking a fixed mortgage mid-term can cost far more than the rate saving, which is why I run the full math before recommending it. Start any of the three conversations with a Mortgage Renewal Check if your term is ending soon anyway — timing a refinance to renewal can eliminate the penalty entirely. Also see cash-back mortgages: who pays for the ‘free’ money, and blend-and-extend: borrowing more without breaking your term.

“She got everything done fast and found me a great rate too. Honestly, I felt really taken care of the whole time.” — Vince, Google review

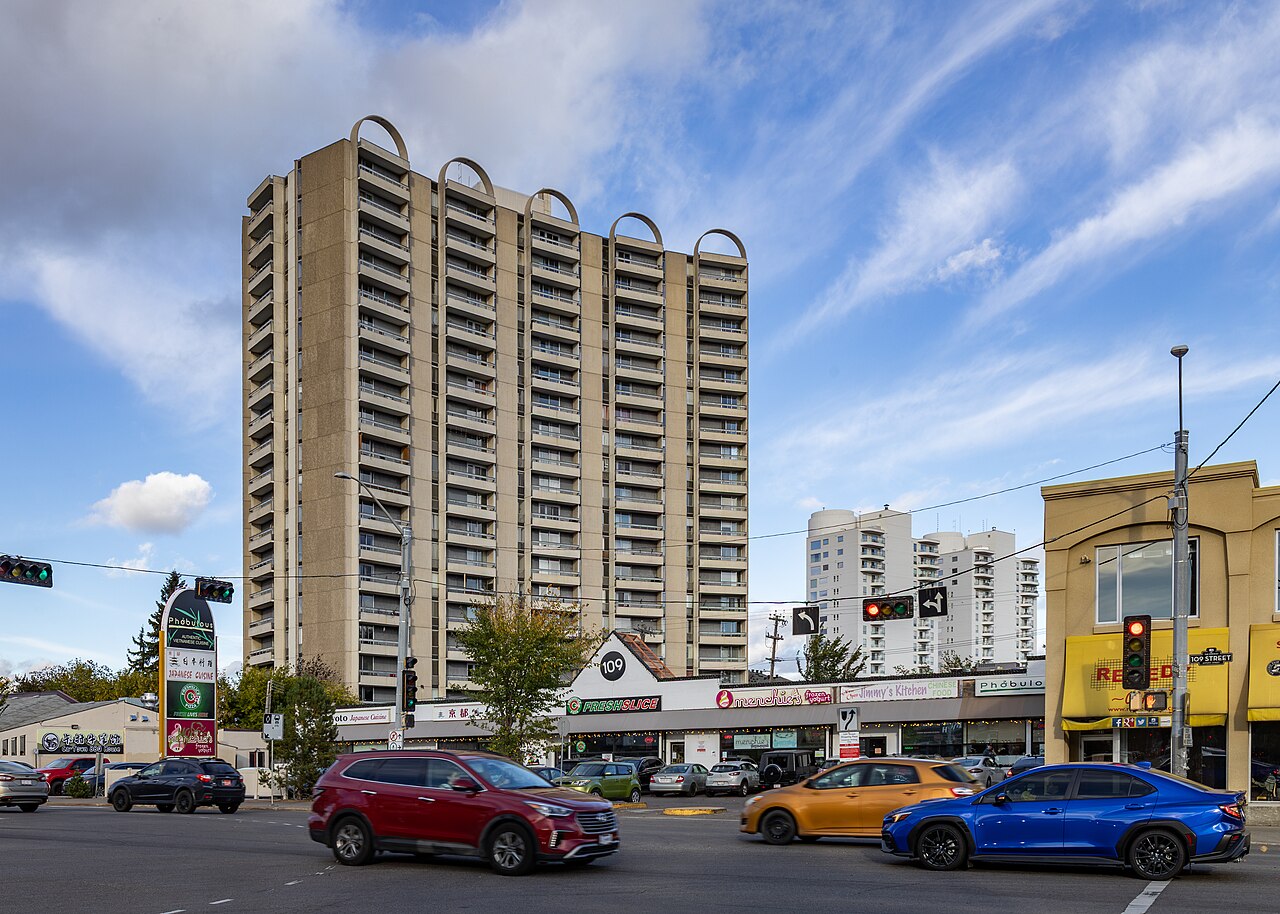
Edmonton homeowner comparing home equity borrowing options

Photo via Wikimedia Commons.

Renovation, debt consolidation, or a major purchase coming up? Call me at (780) 722-5621 and we will compare all three structures on your actual balance, rate and timeline — including the penalty, in writing. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Gifted Down Payment Rules in Canada: Gift Letters, Timing and Source of Funds

General 22 Oct

A gifted down payment in Canada must come from an immediate family member, be confirmed in a signed gift letter stating the money does not have to be repaid, and be supported by a paper trail showing where the funds came from and that they are in your account. Handled early and documented properly, a gift is a normal, accepted way for Edmonton buyers to complete a down payment. See parents helping with a down payment: all four routes compared.

Who is allowed to gift you a down payment?

For most lenders and insurers, the gift must come from an immediate family member, such as a parent, grandparent, sibling, or spouse or partner, depending on the lender’s policy. Gifts from friends or more distant relatives are not accepted as a down payment source by many lenders.

The relationship matters because the lender needs to know this is genuine family support, not a hidden loan. If your situation does not fit the usual definition, raise it at pre-approval so we can check which lenders will accept it.

My First Home Guide for Edmonton covers gifts alongside savings and other down payment sources for first-time buyers.

What does a gift letter need to say?

The gift letter is a signed document from the person giving the money. While exact forms vary by lender, it typically confirms the giver’s name and relationship to you, the amount, the property being purchased, and a clear statement that the funds are a gift with no expectation or requirement of repayment. See how much down payment you need before the gift tops it up.

That no-repayment statement is the heart of the letter. If the money has to be paid back, it is a debt, and a debt changes how a lender views your application. Do not sign a gift letter for money that is actually a loan — misrepresenting a down payment source can put the whole approval at risk.

Why do lenders ask for a 90-day paper trail?

Lenders need to verify the source of funds for your down payment, and they commonly review about 90 days of account history. They are checking that the money is yours or a documented gift, that it was not borrowed, and that it did not appear without explanation.

“The team at NextDoor Mortgages (Mei & Travis) are the absolute best… provided the help I needed in securing my mortgage.” — Yomi Odusanya, Google review

For a gift, that trail can include the transfer into your account and, in some cases, confirmation from the giver’s account as well. Keep statements for your own savings too, so every dollar can be explained without scrambling at the last minute.

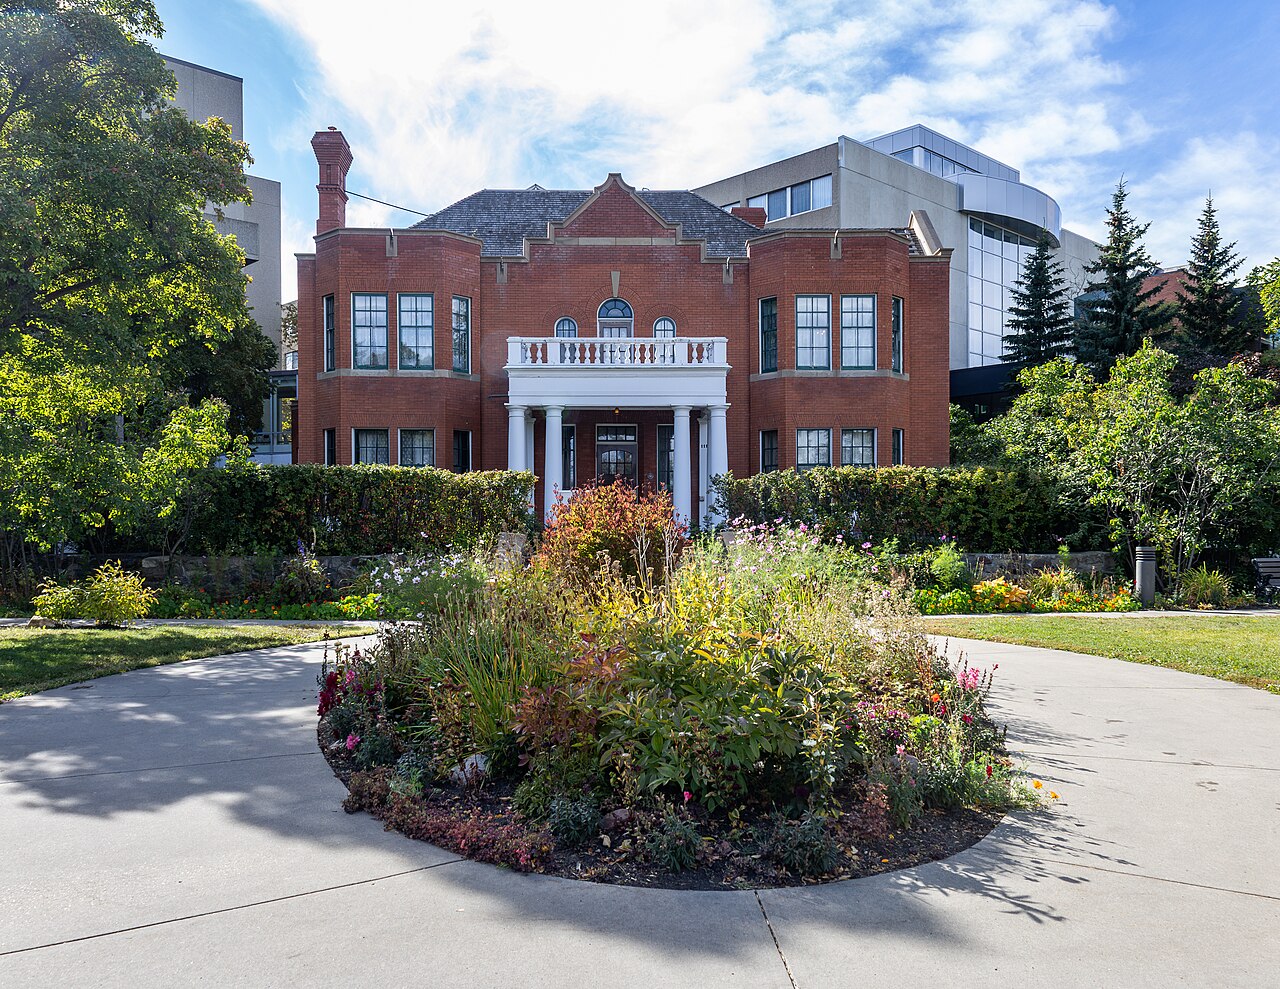
Gift letter for an Edmonton home purchase — home in Strathcona, Edmonton

Credit: via Wikimedia Commons — home in Strathcona, Edmonton.

When should the gift money be transferred?

As early as practical, and ideally before you write an offer. Having the funds in your Canadian account, with the letter signed and the transfer documented, removes one of the most common causes of last-minute financing stress.

A transfer made well before closing is far easier to document than one made days before possession, when lawyers, lenders, and insurers face tight deadlines. Tell your broker at pre-approval, not at the financing-condition stage. Not buying yet? A Mortgage Renewal Check is still worth doing before you sign a renewal.

What mistakes cause problems with gifted funds?

The most common are using a giver who does not qualify as immediate family for that lender, missing or incomplete gift letters, transfers with no paper trail, and gifts that are quietly expected to be repaid.

Is family helping with your down payment? Call me at (780) 722-5621 before you transfer anything, and I will set out the letter and paper trail your lender will actually ask for. See FHSA vs Home Buyers’ Plan: saving the rest yourself. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
25-Year vs 30-Year Amortization in Canada: Payment, Interest and Qualification

General 22 Oct

A 30-year amortization lowers your monthly payment compared to 25 years, but you pay more total interest because the balance comes down more slowly, and in Canada 30 years on an insured mortgage is now available only to first-time buyers and buyers of new builds. If you do not fall into one of those groups, 25 years is the insured limit, so eligibility is the first question, not preference.

Who qualifies for a 30-year insured amortization in Canada?

First-time buyers and buyers of new-build homes can now access a 30-year amortization on an insured mortgage. That change was made to help those buyers manage payments on a first purchase or a newly built home.

Other insured buyers remain at a maximum of 25 years. Uninsured mortgages follow different lender rules, and some lenders may offer longer amortizations on uninsured files, but that is lender-specific and should never be assumed at pre-approval.

If you are a first-time buyer in Edmonton, the First Home Guide for Edmonton sets out how amortization fits with your down payment, stress test, and closing timeline.

How does amortization change your monthly payment?

Amortization is the total length of time it would take to pay off the mortgage if the rate and payment stayed the same. Stretching that period spreads the principal over more payments, so each payment is lower.

Here is a clearly labelled illustrative example using round numbers only, not a rate quote: on a $500,000 mortgage, repaying the same principal over 30 years instead of 25 produces a lower monthly payment at the same rate. Your exact payment depends on the rate you actually qualify for. See payment frequency and accelerated payments, explained.

Why does a longer amortization cost more interest?

Because the balance stays higher for longer. Interest is charged on what you owe, so paying principal down more slowly means more interest paid over the life of the mortgage, even at the same rate.

“She took the time to understand my unique financial situation and offered tailored solutions… I’m now a proud homeowner.” — Ivan, Google review

Many borrowers manage this trade-off actively: they choose the longer amortization for flexibility, then use prepayment privileges, when their terms allow, to pay extra in good months and reduce the balance faster. That only works if your mortgage’s prepayment terms allow it, so check them alongside the rate.

Choosing a mortgage amortization in Edmonton — Rutherford House, Edmonton

Credit: via Wikimedia Commons — Rutherford House, Edmonton.

Does amortization affect how much you qualify for?

Yes. Lenders use your required monthly payment, along with your other debts and housing costs, when they assess how much you can borrow under the stress test. A lower required payment from a 30-year amortization can increase the amount that fits within those ratios for an eligible buyer. See running your own affordability worksheet.

It does not change your income, your credit, or the stress test itself. It changes one input in the calculation. A buyer who qualifies for slightly more should still decide how much they actually want to spend in Edmonton, based on the full cost of owning that home. See the stress test that decides which amortization you qualify for.

If you are renewing rather than buying, your remaining amortization is part of the review as well. Use the Mortgage Renewal Check to look at your options before your term ends.

Which amortization should you choose?

Choose 25 years if you value paying less total interest and building equity faster, and you are comfortable with the higher required payment. Choose 30 years, if you are eligible, if the lower payment is what makes the purchase work responsibly, or if flexibility matters more right now than speed of repayment.

Eligible for 30 years, or deciding between the two? Call me at (780) 722-5621 and I will compare both amortizations on your actual purchase before you write an offer, or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
CMHC Mortgage Insurance Explained: What It Protects, What It Costs, What It Unlocks

General 22 Oct

CMHC mortgage insurance protects the lender, not the borrower, if the borrower defaults, and it is required in Canada when you buy with less than 20% down. The premium is added to your mortgage, scales with how much you borrow compared to the home’s value, and in return an insured mortgage can unlock a lower interest rate and a purchase with a smaller down payment. See the insured vs uninsured down payment rules.

Who does mortgage insurance actually protect?

It protects the lender. If a borrower stops paying and the sale of the home does not cover what is owed, the insurer covers the lender’s eligible loss under the policy.

That protection lets lenders approve high-ratio mortgages with confidence. You pay the premium, but the coverage is for the lender — a point many Edmonton buyers misunderstand at first. Insurance comes through CMHC or another approved insurer, and both insurer and lender must approve the file.

What does CMHC insurance cost?

The premium is a one-time amount that is added to your mortgage balance and paid off over the amortization, with interest. You do not usually pay it in cash at closing, which helps buyers preserve cash for other costs. See closing costs, including the tax on the CMHC premium.

Premiums scale with loan-to-value: the smaller your down payment is as a share of the price, the higher the premium will be as a percentage of the mortgage. Premiums are set by the insurer, not by the lender or the broker, and they depend on the specifics of the file.

Because the premium increases the amount borrowed, include it when you compare an insured purchase against saving more. My First Home Guide for Edmonton shows where it sits in the full cost of buying.

Why can an insured mortgage have a better rate?

Because the lender’s risk is covered by the insurance, insured mortgages can access lower rates than comparable uninsured mortgages. That is not guaranteed on every file, but it is a real and common feature of the Canadian system.

“Mei is very detail-oriented, efficient, and managed to secure me a great rate.” — Kani Lo, Google review

This is why the cheapest option is not always the one with no insurance. You need to compare the rate, the premium added to the balance, your monthly payment, and how long you expect to keep that mortgage before deciding which version costs less for you.

Mortgage insurance for Edmonton home buyers — Walterdale Bridge, Edmonton

Credit: via Wikimedia Commons — Walterdale Bridge, Edmonton.

What rules does the insurer apply to your purchase?

Insured purchases in Canada are capped at $1.5 million. The home must meet the insurer’s property and borrower requirements, and you must qualify at the stress test rate set by federal rules, not just at your contract rate. See the stress test every insured mortgage still has to pass.

Amortization is also limited on insured files. Most insured buyers use up to 25 years, while 30 years is now available to first-time buyers and to buyers of new builds on insured mortgages. Those details should be confirmed at pre-approval, not after you have written an offer.

If you already own a home and your term is ending, insurance from your original purchase can affect your renewal options too. Start with the Mortgage Renewal Check before you accept a renewal offer.

Should you try to avoid mortgage insurance?

Not automatically. Avoiding it by putting 20% down removes the premium, but it can also mean a higher rate, a different amortization, and much less cash left after closing.

For many buyers, buying sooner with insurance, at a responsible price and a carryable payment, is the better decision. For others, waiting and saving more is right.

Want to see what insurance adds to your mortgage — and what it unlocks? Call me at (780) 722-5621 and I will show you the insured and uninsured versions side by side, with no obligation. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

How Much Down Payment Do You Need in Canada? The Insured and Uninsured Rules Explained

General 22 Oct

In Canada, the minimum down payment is 5% on the first $500,000 of the purchase price and 10% on the portion between $500,000 and $1.5 million for an insured purchase, while putting 20% or more down lets you buy without mortgage insurance. The right amount depends on the price, your savings, and whether the insured or uninsured product fits you better overall.

What is the minimum down payment on an Edmonton home?

The minimum is tiered, not a single percentage. On a purchase at or under $500,000, you can buy with 5% down, provided the mortgage is insured and you qualify under the stress test and lender rules.

On a higher-priced home, you pay 5% on the first $500,000 and 10% on the part above that, up to the insured cap of $1.5 million. That blended calculation is why two buyers at different price points end up with very different minimums, even though both use the smallest allowed down payment.

If you are buying your first home, my First Home Guide for Edmonton walks through how the down payment fits with closing costs, pre-approval, and your offer timeline.

When does 20% down change the mortgage you get?

At 20% down, mortgage insurance is no longer required. That removes the insurance premium from the mortgage, which can lower the total amount you borrow and the interest you pay over time.

It also changes the product. An uninsured mortgage follows a different set of lender rules than an insured one, and the rate, amortization options, and property rules can differ. More down payment is not automatically better if it leaves you with no reserve for moving, repairs, or an emergency fund.

Why do some buyers choose an insured mortgage on purpose?

An insured mortgage can be a deliberate choice, not just a fallback for buyers with less saved. Because the insurance protects the lender if the borrower defaults, insured files can access lower rates than comparable uninsured files. See CMHC insurance: what it protects, what it costs, what it unlocks.

That rate advantage has to be weighed against the premium, which is added to the mortgage rather than paid in cash up front. For some buyers, especially those who value keeping cash available, the insured option works out well.

“Great rates, fast closing, and excellent customer service.” — Madhav Dhakal, Google review

Down payment rules for Edmonton home buyers — downtown Edmonton

Credit: via Wikimedia Commons — downtown Edmonton.

What else should you budget for besides the down payment?

Your down payment is not your total cash to close. You will also need funds for legal fees, a home inspection if you choose one, an appraisal if the lender requires it, and other closing costs that vary by purchase.

Lenders also need to see where the down payment came from. Savings, investments, or a gift from an immediate family member can all work, but each source needs a paper trail. Having those documents ready before you write an offer makes the approval much smoother. See gifted down payments: letters, timing and source of funds.

If your mortgage is coming up for renewal instead, use the Mortgage Renewal Check to review your options before you sign anything back to your current lender.

How do you decide how much to put down?

Start with the minimum for your price, then test 20% and one option in between. Compare the monthly payment, the total borrowed including any premium, the rate available on each version, and how much cash you keep after closing. See how much house the down payment actually buys you.

Not sure whether insured or uninsured is better for your purchase? Call me at (780) 722-5621 and I will run both options on your real numbers before you commit to an offer. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

12