Bank of Canada Decision in Three Days: The Monday Checklist for Edmonton Borrowers Before October 28

General Travis Bannert 25 Oct

The Bank of Canada announces its next policy decision on Wednesday, October 28, with the rate currently at 2.25% and prime at 4.45% — and for the first time in a year, a hike is the majority expectation: 19 of 34 economists in the Reuters October 21–23 poll expect a 25-point rise to 2.50%, with futures pricing roughly a three-in-four chance. Monday is the last full business day to act before the announcement, so Edmonton borrowers with a variable mortgage, a renewal inside 120 days, or a purchase closing soon should use it for three things: a rate hold, their variable-payment math, and a renewal plan that works under either outcome.

What exactly is expected on October 28 — and why did it flip?

A week ago most forecasters expected another hold. Two things changed the call: September inflation printed at 3.1%, just above the Bank’s 1–3% target range, and the Bank’s Business Outlook Survey showed sharply rising inflation expectations, followed by Governor Macklem remarks markets read as a hike hint. Oxford Economics now expects hikes on October 28 and again in December to 2.75%. This is still a forecast, not a decision — the Bank has held at 2.25% at every 2026 decision so far — which is exactly why Monday’s job is preparation, not prediction. My earlier breakdown of what a Bank of Canada decision does to your mortgage explains the fixed-versus-variable mechanics behind this checklist.

Monday action 1: Get a rate hold if your date is inside 120 days

A rate hold locks today’s fixed-rate pricing for a set window — commonly up to 120 days — at no cost, and if rates fall before you fund, you generally get the lower rate. If you are renewing, start with a Mortgage Renewal Check; if you are buying, use the Pre-Approval & Refinance Check. A hold taken Monday covers you whether Tuesday brings a hike, a hold, or bond-market movement afterward — fixed rates follow bond yields, which have already been repricing on these expectations, so waiting for the announcement does not freeze today’s offers.
Edmonton borrowers preparing for the Bank of Canada decision

Photo via Wikimedia Commons.

Monday action 2: Know your variable number before Tuesday

On an adjustable-payment variable, each 0.25% rise adds roughly $13 per month per $100,000 owed. On a fixed-payment variable, the payment stays the same and more of it goes to interest, which matters if you are near a trigger point. Find your current balance, your payment type, and your lender’s prime-minus or prime-plus margin on Monday while there is time to ask questions — not on Wednesday morning in a headline.

Monday action 3: Decide your renewal move in advance

If your term ends in the next four months, choose now: sign the bank’s first offer, switch lenders, or hold a rate while you compare. The comparison is free and the hold makes it riskless. First-time buyers closing soon should pair the hold with the steps in the First Home Guide for Edmonton.

“Travis explained what the rate news actually meant for our renewal in plain language, and got our hold in place before the announcement.” — Google review excerpt

Decision lands Wednesday at 7:45 AM Edmonton time. Want your hold in place Monday? Call (780) 722-5621 — I will try to call you this week, or reply with a good time and we will set a phone appointment before the announcement.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Rate Hold Expired Before Possession? Options for Long New-Build Timelines in Edmonton

General Travis Bannert 24 Oct

When a rate hold expires before a long new-build possession, you have not lost your mortgage — you have lost the ceiling on its price. The practical options are a fresh hold or approval at current rates, a builder-affiliated lender’s capped-rate program if your builder offers one, or restructuring the file (down payment, amortization, product) so the new rate environment still qualifies you comfortably. See new-build approvals: holds, deposits and long possession dates.

Why do new builds outrun rate holds?

A standard rate hold runs about 90 to 120 days; an Edmonton new build can run a year or more from contract to possession. Lenders generally will not extend a hold indefinitely, and each new hold is priced on the market of the day it is issued — in a rising-rate stretch, that repricing is the whole problem. The timing risk is live right now: a Reuters poll published October 23 found most economists expect the Bank of Canada to begin raising its policy rate on October 28, and bond yields that drive fixed rates have already been moving on those expectations. See the original case for holding a rate early.

What are the real options, in order?

First, re-secure approval early rather than waiting for possession month — a broker can place a new hold as the old one lapses, and knowing your new number a year out beats discovering it at funding. Second, check your builder’s lender program: some builders arrange capped rates with a partner lender, where your rate can float down but not above a ceiling, in exchange for using that lender. Third, adjust the structure: additional down payment saved during the longer build, choosing the amortization that keeps qualification comfortable, or selecting a product whose penalty and portability terms forgive a later refinance if rates retreat. Fourth — the one to avoid improvising — do not quietly assume the original budget still works; re-run the stress-test math on the new rate before possession, while you still have choices. See GST timing on a long new-build timeline.

“Mei is very detail-oriented, efficient, and managed to secure me a great rate.” — Kani Lo, Google review

Edmonton new construction and long mortgage rate holds

Photo via Wikimedia Commons.

What should you do at contract signing to prevent this?

Build the rate conversation into the purchase: ask what happens to your approval if possession slips by a season, keep your broker informed of every builder delay notice, and keep your file warm — updated income documents and no new debts during the build — so a re-approval is a refresh, not a restart. A Mortgage Renewal Check is built for renewals, but the same discipline applies here: never let a date on a calendar quietly reprice your largest debt.

Building in Edmonton with a possession date beyond your rate hold? Call me at (780) 722-5621 and we will set the re-hold schedule now, not in possession month. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Reuters Poll Flips: Most Economists Now Expect a Bank of Canada Hike on October 28 — What Edmonton Borrowers Do This Weekend

General Travis Bannert 24 Oct

The forecast for the Bank of Canada’s October 28 decision flipped this week: a Reuters poll of economists conducted October 21-23 found 19 of 34 — 56% — now expect a 25-point hike to 2.50%, after the previous poll had 80% expecting a hold at 2.25% through the end of 2026. Edmonton borrowers with a renewal, closing, or variable mortgage have this weekend to get a rate hold and a two-outcome plan in place before Tuesday’s announcement. See the decision itself, explained for Edmonton borrowers.

What changed the forecast in one week?

The Bank’s own Business Outlook Survey. It showed inflation expectations rising sharply as trade talks with the United States broke down, and Governor Tiff Macklem’s remarks last weekend were widely read as a hint a hike is coming. Desjardins’ Royce Mendes said the survey responses changed both the Governor’s tone and economists’ views: “the survey responses… suggest there are more serious inflationary pressures coming.” Markets moved with them — interest-rate futures went from pricing a roughly 30% chance of an October hike to about three-in-four. September inflation at 3.1%, just above the Bank’s 1-3% target range, and oil touching $117 a barrel on Friday complete the case the hike camp is making. See the earlier Oxford-C.D. Howe split this poll overtook.

What does the poll expect after October?

A short campaign, not a cycle. Sixteen of 29 respondents expect one more hike before March 2027, taking the policy rate to 2.75%, and then a hold — which Reuters noted would be the shortest Bank of Canada tightening campaign in 30 years. The hold camp’s argument is the other half of the data: a weak economy, growth expected at just 1.0% in 2026, and subdued inflation once energy is stripped out. BMO’s Benjamin Reitzes summed up the hike logic: the Bank would rather hike slightly early than fall behind the curve as it did in 2021-22.

“Great rates, fast closing, and excellent customer service.” — Madhav Dhakal, Google review

Edmonton mortgage borrowers preparing for a possible rate hike

Photo via Wikimedia Commons.

What should Edmonton borrowers do before Tuesday?

If your mortgage renews or your purchase closes within about 120 days, ask for a rate hold now — it costs nothing and caps your exposure whichever way Tuesday goes; start with a Mortgage Renewal Check if your term is ending. If you hold a variable mortgage, know in advance what a 25-point rise does to your payment or your amortization. And remember fixed rates follow bond yields, which have already been repricing on these expectations — waiting for the announcement does not freeze today’s fixed offers. First-time buyers should pair the hold with the steps in the First Home Guide for Edmonton. See why a rate hold is this weekend’s move.

Renewing, closing, or holding a variable rate into Tuesday’s decision? Call me at (780) 722-5621 this weekend and we will run both outcomes on your actual balance before October 28. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Mortgage Payment Frequency in Canada: Weekly, Accelerated and Lump Sums Explained

General Travis Bannert 23 Oct

The word “accelerated” is what saves you money in a payment frequency — not weekly or bi-weekly by itself. An accelerated bi-weekly payment takes your monthly payment, divides it by two, and collects it every two weeks, which quietly adds one extra monthly payment a year and cuts years of interest over an amortization.

What are the standard frequency options?

Monthly is the baseline: twelve payments a year. Semi-monthly collects half a monthly payment twice a month — twenty-four payments totalling exactly the same as monthly. Regular bi-weekly collects every two weeks based on dividing the year differently, totalling roughly the same as monthly. Accelerated bi-weekly and accelerated weekly are the versions that overpay on purpose: because there are twenty-six bi-weekly periods in a year, twenty-six half-monthly payments equal thirteen monthly payments — one full extra payment annually, applied against principal and interest over time.

How much difference does the extra payment make?

It depends on your balance, rate and remaining amortization, but the direction never changes: more principal paid earlier means less interest charged on every payment after it. On a typical mortgage held to term, one extra monthly payment a year commonly shortens the amortization by several years. The honest way to see your number is an amortization comparison on your actual balance — I run both versions side by side for clients, because the generic online examples rarely match a real file. See 25-year vs 30-year amortization: the payment trade-off.

“She took the time to understand my unique financial situation and offered tailored solutions… I’m now a proud homeowner.” — Ivan, Google review

Edmonton homeowner setting mortgage payment frequency

Photo via Wikimedia Commons.

What about lump sums and payment increases?

Frequency is one lever; your prepayment privileges are the other. An annual lump sum within your privilege limit, or a permanent payment increase, can outpace even accelerated frequency — and the two combine. The discipline that matters is matching payments to your pay schedule so the account is never strained: an accelerated plan you abandon after six months loses to a plain plan you keep for twenty years. If your income is irregular — common for self-employed borrowers — a monthly payment plus voluntary lump sums often fits better than a rigid accelerated schedule. See open vs closed: whether your term lets you pay faster.

Set the frequency at origination, then revisit it at every renewal. A Mortgage Renewal Check is a good moment to recalculate what your current frequency is actually doing to your payoff date.

Want your real payoff dates compared — monthly vs accelerated, with and without a lump sum? Call me at (780) 722-5621 and bring your current balance and rate. See also fixed vs variable, and which payment behaviour each rewards, or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Open vs Closed Mortgages in Canada: Prepayment Privileges That Actually Matter

General Travis Bannert 23 Oct

A closed mortgage trades flexibility for a lower rate: you may prepay only within set privileges, and leaving early triggers a penalty. An open mortgage lets you repay or leave at any time without penalty, at a noticeably higher rate. For most Edmonton borrowers, a closed mortgage with generous prepayment privileges is the sweet spot — if you actually read the privileges before signing. See fixed vs variable: payment, penalty and flexibility compared.

What prepayment privileges do closed mortgages include?

Two kinds, both lender-specific. Lump-sum privileges let you pay an extra percentage of the original balance each year — commonly in the range of 10% to 20% depending on the lender and product — without penalty. Payment-increase privileges let you raise your regular payment by a set percentage, which quietly shortens your amortization. Some products restrict both sharply in exchange for a slightly lower rate; those “no-frills” trade-offs are where borrowers get trapped, because the rate saving is small and the lost flexibility is permanent for the term. See using payment frequency and lump sums inside a closed term.

When is an open mortgage worth its higher rate?

When you know money is coming or a change is booked: a home you expect to sell within months, an estate settlement or inheritance arriving soon, a planned move for work, or a short bridge between situations where certainty of exit matters more than rate. Open terms are usually short — six months or one year — and are priced as flexibility products. Holding an open mortgage for years “just in case” is paying a premium every month for an exit you never use.

“She got everything done fast and found me a great rate too. Honestly, I felt really taken care of the whole time.” — Vince, Google review

Edmonton homeowner reviewing mortgage prepayment privileges

Photo via Wikimedia Commons.

How should you choose?

Estimate honestly how much extra you will actually prepay — most borrowers use far less than their maximum privilege — then compare lenders on both rate and privilege percentages together. If a sale or refinance is even a possibility mid-term, also compare penalty formulas: on fixed mortgages the interest rate differential calculation varies widely between lenders, and that difference can exceed every other feature combined. This comparison is a standard part of a Mortgage Renewal Check — privileges and penalties, not just the rate on the letter. See the two penalty formulas, worked through.

Choosing between open, closed, and a low-rate restricted product? Call me at (780) 722-5621 and we will match the privileges to how you will really use the mortgage, or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Bank of Canada October 28: Oxford Says Hike, C.D. Howe Says Hold — How Edmonton Borrowers Should Prepare This Weekend

General Travis Bannert 23 Oct

Five days before the Bank of Canada’s October 28 decision, two credible forecasters published opposite calls on October 22: Oxford Economics expects a 25-point hike next week and another in December, while the C.D. Howe Institute’s Monetary Policy Council recommends holding at 2.25%. Edmonton borrowers cannot control the decision — but this weekend is exactly when a rate hold and a two-outcome plan are worth the most. See what the decision does to variable payments, renewals and holds.

What exactly did each forecaster say on October 22?

Oxford Economics moved its hike forecast forward, citing higher oil prices and the risk that headline inflation stays elevated into early 2027. It now expects the policy rate to rise 25 basis points on October 28 and again in December, reaching 2.75% — roughly a year earlier than its September forecast. Oxford called October a “toss-up” after weaker employment and inflation data, but expects a cumulative 50 basis points of tightening by January even if the Bank holds next week.

The C.D. Howe Monetary Policy Council — chaired by Jeremy Kronick and including chief economists of the six largest banks — voted 6 to 1 to hold at 2.25% on October 28, then rise to 2.50% by April 2027 and 2.75% by October 2027. Same destination in Oxford’s case, very different timing. See the Reuters poll flip in the decision’s final week.

What are the facts both sides are looking at?

The policy rate has been held at 2.25% through seven consecutive decisions, with big-bank prime at 4.45%. September inflation was 3.1%, driven mostly by gasoline — excluding gasoline it was 2.2% — while September employment fell by 68,000 and unemployment rose to 6.5%. Inflation argues one way; jobs argue the other. That is a genuine split, not forecast theatre.

“Great rates, fast closing, and excellent customer service.” — Madhav Dhakal, Google review

Edmonton mortgage borrowers preparing for the Bank of Canada decision

Photo via Wikimedia Commons.

What should Edmonton borrowers do before October 28?

If you have a variable mortgage, know your number in advance: on an adjustable-rate mortgage a 25-point hike raises the payment; on a fixed-payment variable, more of the same payment goes to interest. If you renew, close, or refinance within roughly 120 days, ask about a rate hold now — it gives you a ceiling while you keep comparing, whichever way the decision goes. Start with a Mortgage Renewal Check if your term is ending, and remember fixed rates follow bond yields, not the announcement — they can rise even on a hold. See getting a rate hold in place this weekend.

First-time buyers can pair a hold with the steps in the First Home Guide for Edmonton.

Renewing or closing before the holidays and want both outcomes run on your real balance? Call me at (780) 722-5621 this week — before October 28, not after. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Interest-Rate News Explained: What the Bank of Canada’s October 28 Decision Does to Your Edmonton Mortgage

General Travis Bannert 22 Oct

If the Bank of Canada holds its policy rate at 2.25% on October 28, 2026, variable mortgage rates in Edmonton should stay where they are, with big-bank prime at 4.45%. If the Bank raises the rate by 0.25 points, prime would be expected to move to 4.70% and variable payments or interest costs would follow. Fixed rates are a different story — they follow bond yields, not the Bank’s announcement directly.

The Bank has held at 2.25% through seven consecutive decisions, most recently on September 2, 2026. The October 28 decision comes with a Monetary Policy Report, and forecasters are split between another hold and a hike, so this is a week to have a plan for both outcomes. See the Reuters poll that flipped to a hike in the final week, and Oxford versus C.D. Howe: the two cases, side by side.

What is the Bank of Canada deciding on October 28?

The Bank sets the policy interest rate, which influences what lenders charge for variable-rate mortgages and lines of credit. The current rate is 2.25%, set in October 2025, and big-bank prime sits at 4.45% — prime is the policy rate plus 2.20 points.

Inflation is part of the tension. Consumer prices rose 3.1% in September 2026, up from 3.0% in August — above the Bank’s 2% target, but still inside its 1% to 3% control range, at the top end.

What happens to a variable-rate mortgage if the Bank holds?

Nothing changes on the rate itself. Prime stays at 4.45%, your variable rate stays the same, and your payment or amortization continues as it is now.

A hold is still useful information. It gives borrowers renewing this fall a clearer window to compare staying variable against locking into a fixed rate, without a deadline created by the announcement itself. Start that comparison with a Mortgage Renewal Check rather than waiting for your lender’s renewal letter.

What happens if the Bank raises the rate by 0.25 points?

Variable rates move with prime. A 0.25-point hike would be expected to lift prime from 4.45% to 4.70%, and lenders typically adjust their variable rates by the same amount.

On an adjustable-rate mortgage, the payment rises. On a variable mortgage with a fixed payment, more of each payment goes to interest and the amortization stretches instead. Either way, the change usually takes effect quickly after the decision — this is not a slow, distant adjustment.

“We had an excellent experience working with Travis as both our realtor and mortgage broker… professional, knowledgeable, patient.” — Sheri Tian, Google review

Why do fixed mortgage rates not simply follow the Bank?

Fixed rates follow bond yields, especially the 5-year Government of Canada bond yield, which was 3.54% on October 16, 2026. When bond yields rise, fixed mortgage rates tend to face upward pressure. When yields fall, fixed rates can ease — sometimes even on a day the Bank holds or raises its policy rate. For more on fixed vs variable when the Bank is this unpredictable.

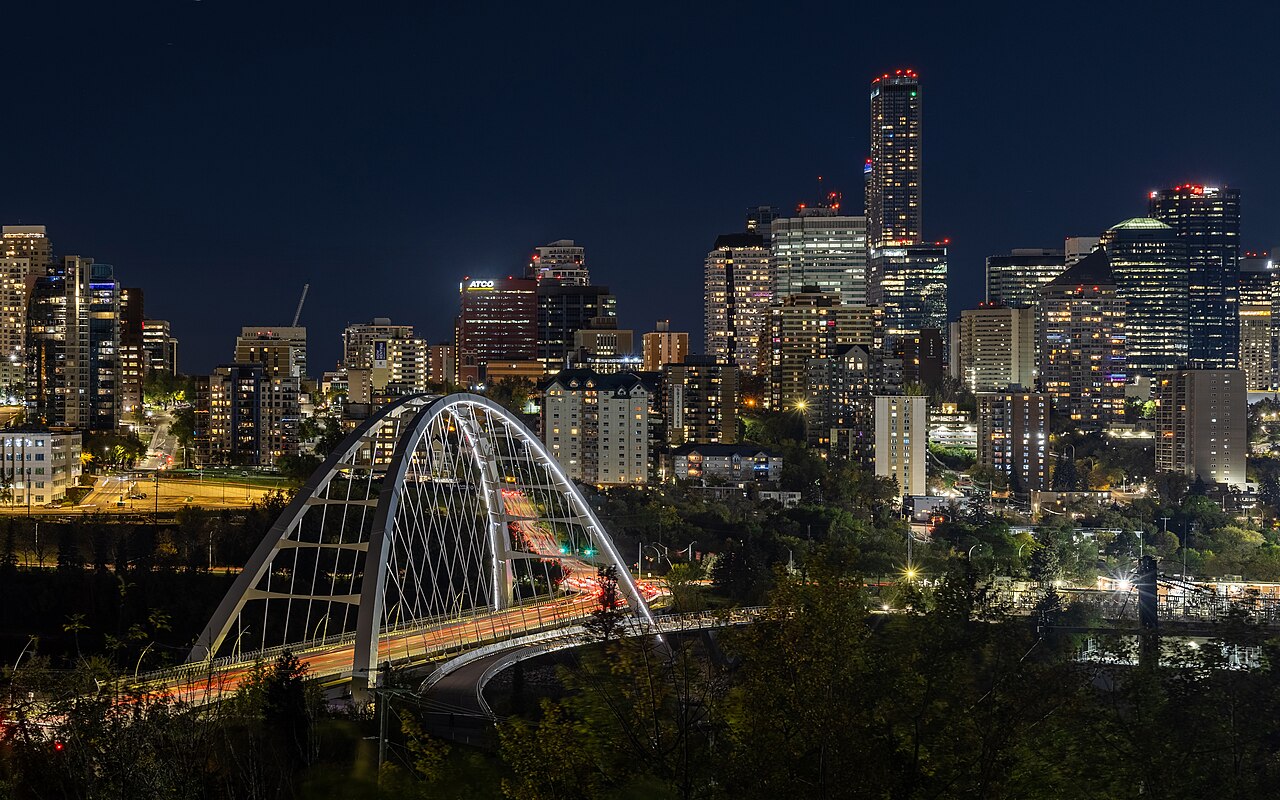
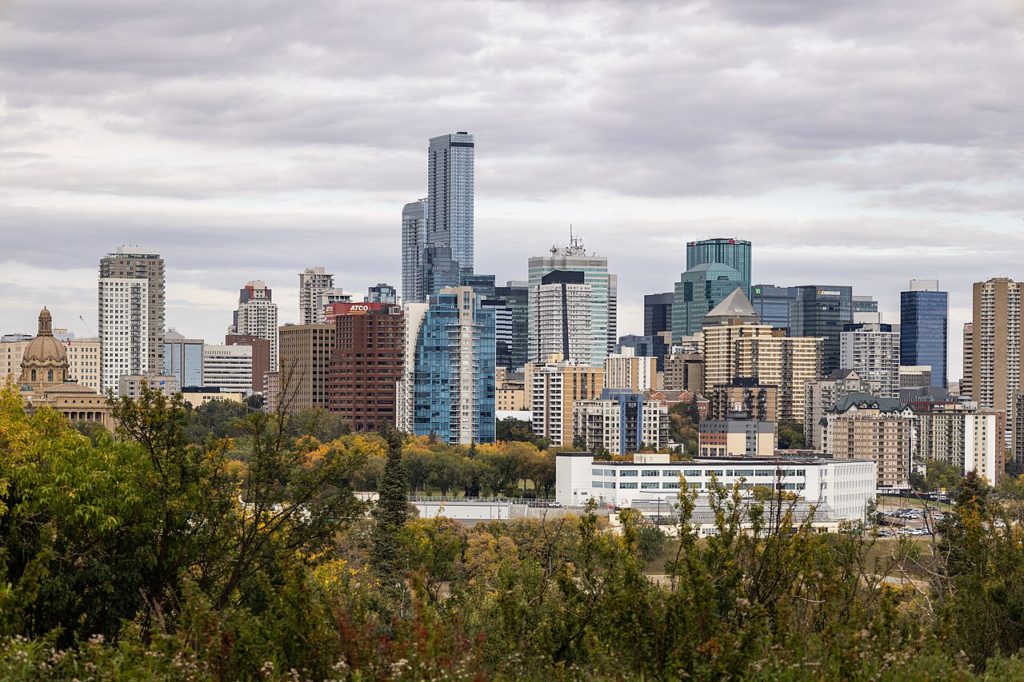
Edmonton mortgage rates and the High Level Bridge — skyline from the High Level Bridge

Credit: Crisco 1492, via Wikimedia Commons (CC BY-SA 4.0).

Should you lock in a rate hold before October 28?

If your renewal, purchase closing, or refinance falls within the next 120 days, yes — ask about a rate hold now. Rate holds usually cost nothing, and many lenders will honour a lower rate if prices fall before you close or renew. See locking a rate hold before the decision.

A hold is protection, not a commitment to that lender or that product. It gives you a ceiling while you keep comparing, which is exactly what you want heading into a split decision. First-time buyers can pair a hold with the steps in the First Home Guide for Edmonton.

Renewing or closing in the next 120 days? Call me at (780) 722-5621 before October 28 and we will get a rate hold in place and walk through what a hold or a hike does to your specific mortgage. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
New-Build Mortgage Approvals in Edmonton: Rate Holds, Deposits and Long Possession Dates

General Travis Bannert 21 Oct

A new-build mortgage approval in Edmonton is really two approvals: one when you sign with the builder, and a final one near possession — and the second one re-checks everything. Standard rate holds run only 90 to 120 days, far shorter than most build timelines, so the strategy is to protect a rate where you can, keep your file unchanged during the build, and calendar a full re-check about 90 days before possession.

Buyers who treat the first approval as final get surprised. Builders sell 8, 12, or 18 months out; lenders fund at the end of that timeline, on the file as it stands then — not at signing.

How long does a mortgage rate hold last on a new build?

A standard rate hold lasts 90 to 120 days, depending on the lender. That covers a typical resale purchase and a new build almost never. See rate hold expired before possession? Your options.

For longer timelines, some lenders offer builder-affiliated or “capped rate” long-hold programs: your rate is capped for the build period, and if rates are lower at funding, you may receive the lower rate per that program’s rules. These programs are lender- and builder-specific — confirm the exact terms on your file. Starting that conversation is part of my Pre-Approval & Refinance Check.

What do builder deposits do to your mortgage?

Deposits you pay the builder during construction reduce the cash still owing at possession — but they do not reduce the price your mortgage is approved on. Your final mortgage is approved on the final price, including GST and any upgrades you added along the way.

That matters twice. Upgrades chosen mid-build raise the final price, and the approval has to match it. And money tied up in deposits is not available for closing costs, moving costs, or your emergency cushion. Map the deposit schedule against your savings before you sign. See GST on the new home and your closing funds.

“The team at NextDoor Mortgages (Mei & Travis) are the absolute best… provided the help I needed in securing my mortgage.” — Yoni Odusanya, Google review

Edmonton new-build mortgage planning — Walterdale Bridge over the North Saskatchewan River

Does the lender re-check your income and credit at possession?

Yes. Completion and final approval happen near possession, and the lender re-verifies income, debts, and credit at funding. A job change, a new car loan, or a fresh credit card mid-build can change — or break — the file at exactly the moment you have the least room to fix it.

The rule during a build: keep the file boring. No new debt, no job moves without a conversation first, no missed payments. If life changes, tell your broker immediately — most problems have a workaround months early and almost none in the funding week.

What if the appraisal comes in below the contract price?

The home is appraised at completion, and if the finished value comes in under your contract price, the mortgage is based on the lower value — that is standard lender practice. The difference becomes additional cash from you at closing.

Keep a cushion beyond your deposit schedule, especially if you loaded the home with upgrades that appraisals tend to value conservatively.

What is the difference between a draw mortgage and a completion mortgage?

Most builder purchases use a completion mortgage: the full amount funds once, at possession. A draw mortgage — more common when you contract the build yourself — advances funds in stages as construction reaches set milestones, with inspections along the way. The right structure depends on who holds the construction risk. If other financing renews in the same window, a Mortgage Renewal Check keeps the timing coordinated.

Signed with a builder, or about to? Call me and we will set the rate protection, map your deposits, and put the 90-day re-check on the calendar. Call (780) 722-5621. For the finishing work, see purchase plus improvements for the finishing work.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

New-Build Mortgage Approvals in Edmonton: Deposits, Rate Caps and Possession Delays

General Travis Bannert 21 Oct

New-build mortgage approvals in Edmonton work differently from a resale purchase because you are approved long before the home exists: you sign with a builder, pay deposits in stages, and your full approval and funding happen near possession, which can be many months later. The mortgage work splits in two — a builder cap or rate hold now to protect your ceiling, and a complete re-check of your file close to possession. Set both up at the start and a delayed possession is an inconvenience, not a crisis.

New construction homes in Edmonton — Walterdale Bridge
Photo: Crisco 1492, via Wikimedia Commons (CC BY-SA 4.0).

How do builder deposits and draws work?

Builders typically collect deposits in stages as construction reaches set milestones, rather than one lump sum at the end. Your deposit money is committed early and is not sitting in your account when the lender does its final review — so the down payment you show at possession has to account for every deposit already paid.

Some construction financing advances funds in draws as the build progresses; a conventional purchase from a builder usually funds once, at possession. Either way, keep statements proving where each deposit came from — lenders trace deposit funds as part of source-of-funds checks.

What is a rate cap, and how long can it run?

A builder cap is a long rate hold arranged through the builder’s lender or program — holds of 180 to 360 days are available in the market and vary by builder and lender. It caps the rate you will pay if rates rise during construction, while still letting you take a lower rate at possession if pricing has improved.

A standard pre-approval rate hold runs 90 to 120 days, which is rarely long enough for a full build. If your possession date is a season away, ask specifically about builder-cap options when you sign, not when the home is framed.

What gets re-checked before possession?

Near possession, the lender completes the file: current income and employment confirmation, updated credit, the finished property’s appraisal, and confirmation your down payment funds are in place. If your job, debts or credit changed during the build, the approval can change with them.

That is the quiet risk in new builds. A car loan taken mid-construction, or a job change in the final months, can shrink what you qualify for at exactly the moment you cannot walk away. Keep your financial picture boring from signing to possession.

“Absolutely the best, informative, great communication… and very helpful” — Michelle, Google review

What happens if possession is delayed?

Build timelines slip: weather, trades and inspections all push dates. A delay matters to your mortgage when it runs past your rate hold or cap expiry, or stretches beyond document validity windows — your broker then has to extend or re-apply, and rates are whatever they are that month.

Protect yourself at signing: know your cap’s expiry date, keep documents easy to refresh, and tell your broker about any financial change immediately rather than at final approval. If possession moves, the GST side of a new home moves with it — that piece is covered in GST on a New Home in Canada.

Start the process through my Pre-Approval & Refinance Check before you visit the show home, so deposit structure and rate protection are planned together.

What is the difference between a draw mortgage and a completion mortgage?

A completion mortgage funds once, at possession — the standard structure for a builder purchase. A draw mortgage advances funds in stages as construction reaches set milestones, with inspections at each stage; it is more common when you contract the build yourself and hold the construction risk. The right structure depends on who is building, and the draw schedule is agreed before the first shovel hits the ground.

What if the appraisal comes in below the contract price?

The home is appraised at completion, and the mortgage is based on the lower of the contract price and the appraised value. If the finished home appraises below what you agreed to pay, the difference is additional cash from you at closing — the lender will not fund the gap.

Keep a cushion beyond your deposit schedule, especially if you loaded the home with upgrades that appraisals tend to value conservatively.

Thinking about a new build in Edmonton or a surrounding community? Call me at (780) 722-5621 — I will try to call you this week, and if you reply with a good time, we can line up deposits, rate protection and possession timing before you sign.

By Travis Bannert, Realtor and Mortgage Broker
Travis Bannert, Mortgage Broker | Next Door Mortgages, Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

Fixed vs Variable Mortgages: Payment, Penalty and Flexibility Differences

General Travis Bannert 21 Oct

The real difference between a fixed and a variable mortgage in Canada isn’t today’s rate — it’s what moves your payment, and what it costs to leave. Variable rates follow your lender’s prime rate (driven by the Bank of Canada), while fixed rates are set by the bond market; variable penalties are usually three months’ interest, while fixed penalties use an interest-rate-differential calculation that can be far larger. Choose on payment behaviour and exit cost first, and the rate second.

Fixed vs variable mortgages in Edmonton — skyline from Saskatchewan Drive in fall

What actually moves each rate?

Variable: your rate is prime minus (or plus) a spread. Prime is currently 4.45%, because the Bank of Canada’s policy rate is 2.25% — and the Bank’s next decision is October 28. If the Bank moves, most variable rates move within days. Some variable mortgages have payments that rise and fall with prime; others hold the payment steady and change how much of it goes to interest — know which kind you’re being offered. See how a Bank of Canada move hits variable borrowers first.

Fixed: your rate is locked for the term, but it’s priced off Government of Canada bond yields, not the Bank of Canada. That’s why fixed rates climbed through September 2026 while the policy rate never moved — and why a Bank of Canada hold on October 28 wouldn’t automatically make fixed rates cheaper.

Which one costs more to break?

This is where the two products genuinely separate:

  • Variable (closed): the penalty is typically three months’ interest on the balance — predictable, and usually modest.
  • Fixed (closed): the penalty is the greater of three months’ interest or the interest rate differential (IRD) — a calculation based on the difference between your contract rate and current rates for the remaining term. When rates have fallen since you signed, IRD penalties can reach into five figures on a mid-size mortgage.

Life changes — a move, a sale, a separation, a refinance — break more mortgages than rate predictions do. If there’s a real chance you’ll sell or refinance inside the term, the penalty column matters more than a small rate difference. (Thinking of renewing instead of breaking? Run a Mortgage Renewal Check before signing anything.) See three months’ interest vs IRD: which penalty you’d actually pay.

“The team at NextDoor Mortgages (Mei & Travis) are the absolute best… provided the help I needed in securing my mortgage.” — Yomi Odusanya, Google review

So which suits you — fixed or variable?

Fixed tends to suit borrowers who need a payment that cannot change (tight monthly budget, first purchase, fixed income), and anyone who is confident they’ll stay in the home and the mortgage for the full term.

Variable tends to suit borrowers with payment room to absorb a rise, a shorter expected stay in the mortgage (where the three-months’-interest penalty protects them), and the temperament to ignore rate headlines between Bank of Canada decisions. See open vs closed: the prepayment privileges that decide flexibility.

Either way, the pre-approval stage is where this gets decided properly — with your income, your timeline, and a rate hold protecting you while you shop. My Pre-Approval & Refinance Check covers exactly that review, and first-time buyers can see the full sequence in the First Home Guide for Edmonton.

Renewing or buying before the October 28 decision? Call me and we’ll compare fixed and variable on your actual balance and timeline — payment, penalty, and flexibility — not just the headline rate.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

12