How much house you can afford is set by two ratios lenders use — your housing costs as a share of gross income, and all your debts as a share of gross income — tested at the stress-test qualifying rate, not the rate you will actually pay. A worksheet that runs those ratios on your real numbers gives you a price range you can trust more than any calculator’s single answer. See the stress test, explained before you run the worksheet.
What goes on the worksheet?
Line one is gross household income — the income your lender can document. Line two is the housing-cost ratio (GDS): mortgage payment calculated at the qualifying rate, plus property taxes, heating, and half of any condo fee, should generally stay within about 39% of gross income for insured files. Line three is the total-debt ratio (TDS): everything in line two plus car payments, cards, lines of credit, and student loans, generally within about 44%. Line four is your actual down payment and closing funds, because the ratios test the payment — and the payment depends on how much you borrow, over what amortization. See 25 vs 30 years: what amortization does to the worksheet. See the down payment rules behind the worksheet’s first line.
Why does the qualifying rate change the answer so much?
Because the stress test qualifies you at the higher of your contract rate plus 2% or the Bank of Canada benchmark. On the same income, the home you qualify for at the test rate is meaningfully smaller than the home your actual payment would suggest — deliberately. It also means small debts punch above their weight: a car payment consumes TDS room dollar for dollar against the mortgage it displaces, which is why paying down a vehicle loan before applying sometimes unlocks more house than adding the same cash to the down payment.
“This has been the best customer service experience I’ve had in Canada over the past five years.” — Minsang Lee, Google review
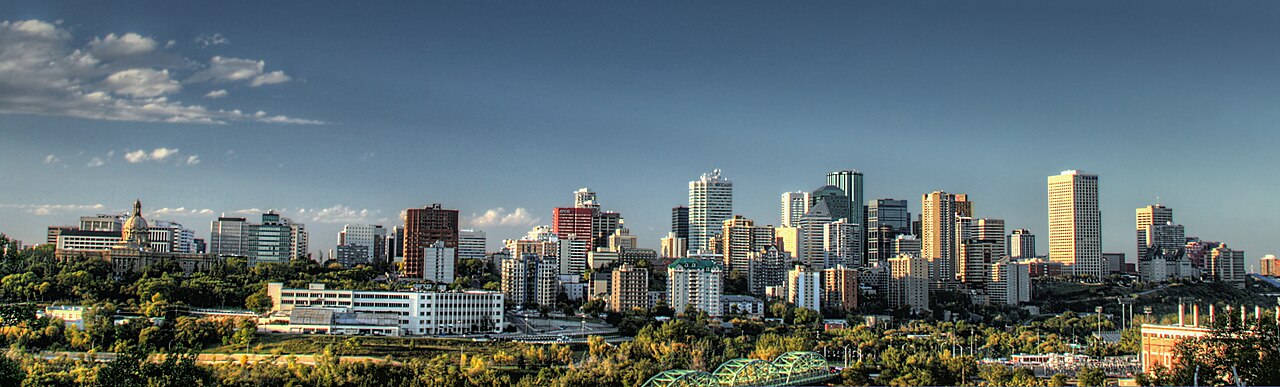
Photo via Wikimedia Commons.
What does the worksheet say in Edmonton terms?
Anchor it to real prices: Royal LePage put Edmonton’s Q3 2026 detached median at $529,600 and the standard condo median at $207,700. Run your ratios at both price points and the worksheet stops being abstract — you see whether your income supports detached, where the condo-to-house gap sits, and what changes it: a larger down payment, a paid-off debt, a co-borrower, or a longer amortization where you qualify for one. The First Home Guide for Edmonton walks the purchase steps that follow once the number is real.
Want the worksheet run on your actual income and debts — not a website estimate? Call me at (780) 722-5621 and we will build your real price range together. Or start with the Pre-Approval & Refinance Check.
By Travis Bannert, Realtor and Mortgage Broker
Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com