Knob-and-tube wiring rarely kills an Edmonton mortgage by itself — but it can kill your insurance binder, and without insurance your mortgage cannot fund. That is the order of operations older-home buyers miss: most lenders will consider the file, while many insurers will decline, surcharge, or require the wiring to be replaced or certified by a licensed electrician within a set window after possession. Confirm insurability during your condition period, not after waiver day, because the mortgage approval and the home insurance policy have to arrive together at funding.
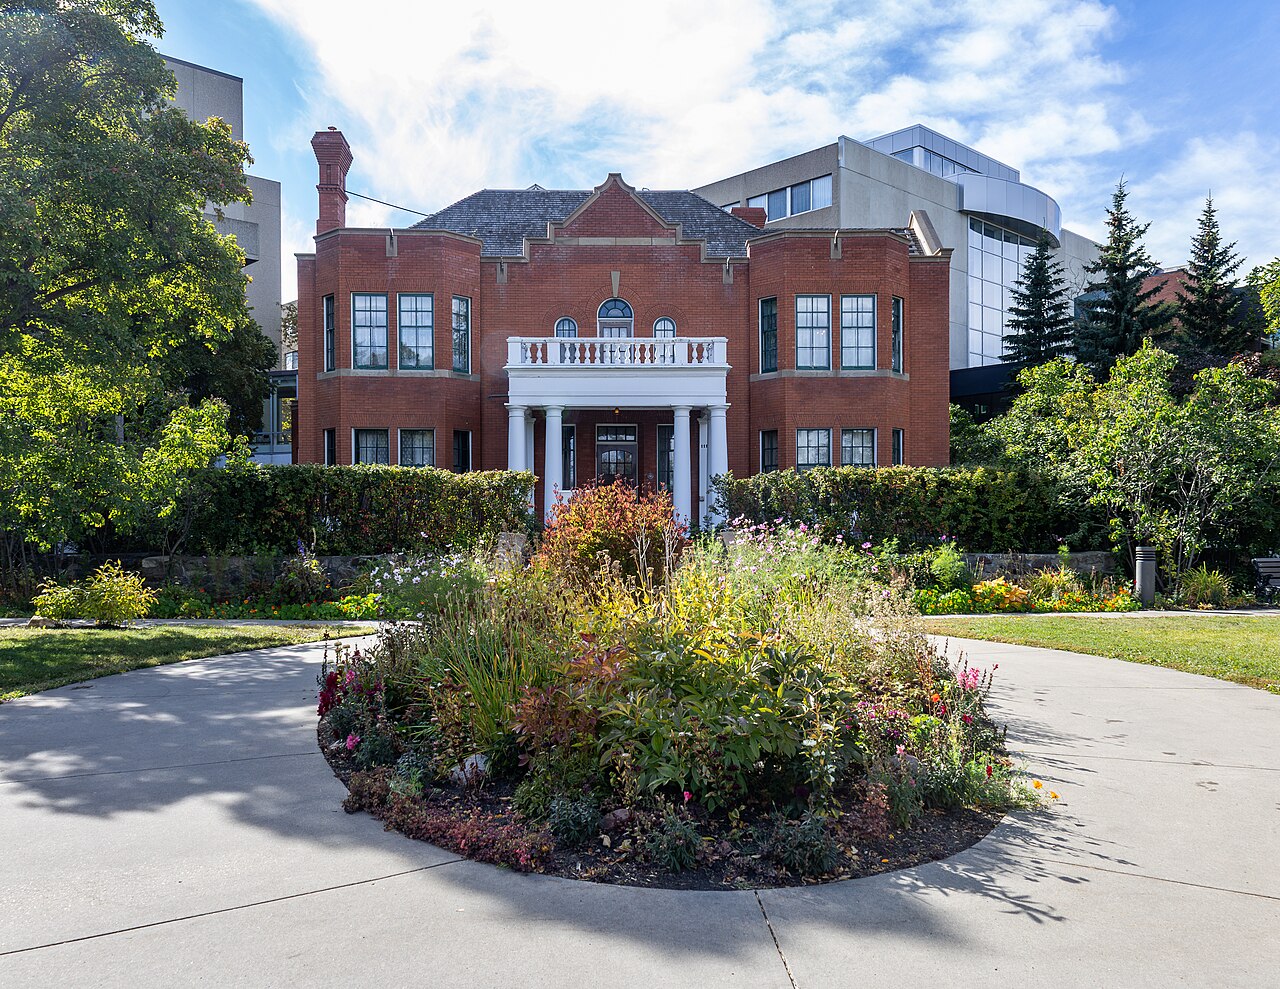
Photo via Wikimedia Commons.
What is knob-and-tube, and where does it show up?
It is an early wiring method — two separate conductors run on ceramic knobs and through tubes — found in Edmonton homes built in the early decades of the last century and sometimes surviving in attics and walls of renovated homes. Home inspectors flag it, electricians can assess how much remains active, and sellers may genuinely not know whether a past renovation removed all of it. The practical question is never the label; it is how much is live, where, and what your insurer says about it in writing.
What do lenders actually require?
The lender’s core requirements are a marketable property and valid home insurance in place for funding. The insurer is usually the strict party: expect one of three answers — insure as-is, insure with a condition (electrician’s certification or a replacement deadline), or decline. If replacement is required, the cost conversation belongs inside your condition window, alongside the documents a broker reviews up front and the financing sequence in my guide to financing condition timelines in Alberta. Get the insurance quote in writing before you waive conditions.
How do you budget for it?
If the insurer requires replacement, get an electrician’s quote during the condition period and decide whether the price, a seller credit, or walking away is the right answer — the same triage as any major system. Buyers sometimes roll eligible work into a purchase-plus-improvements structure; whether that fits your file is a conversation for the Pre-Approval & Refinance Check before you offer, not after.
“Great rates, fast closing, and excellent customer service.” — Madhav Dhakal, Google review
The one rule for older-home buyers
Never let the insurance answer arrive after the financing deadline. The day you write the offer on a century-old Edmonton home, the insurance call goes on the same to-do list as the inspection booking.
Buying an older Edmonton home with wiring questions? Call (780) 722-5621 — I will try to call you this week, or reply with a good time and we will set a phone appointment to line up lender and insurer before your conditions expire.
By Travis Bannert, Realtor and Mortgage Broker
Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com