Bank of Canada Raises to 2.50% — What It Does to Your Edmonton Mortgage

General Travis Bannert 28 Oct

Prime moved to 4.70% on October 29, 2026 (TD mortgage prime 4.85%). The next Bank of Canada decision is December 9, 2026.

The Bank of Canada raised its policy rate to 2.50% on October 28, 2026, and prime moved to 4.70%. On a variable mortgage that raises your payment or pushes you toward your trigger rate; on a fixed term, nothing changes until renewal. The next decision is December 9, 2026.

Short on time? Watch the 1-minute version: https://www.youtube.com/shorts/3uO5rgc4Sgw

The Bank of Canada raised its policy rate by 25 basis points this morning, to 2.50% — the first increase since July 2023, after holding at 2.25% since October 2025. The Bank pointed to inflation that has been around 3% since April and is expected to rise to about 3.5% by year-end, and said there could be a need to increase the policy rate further, though it agreed to proceed carefully. The next decision is December 9, 2026.
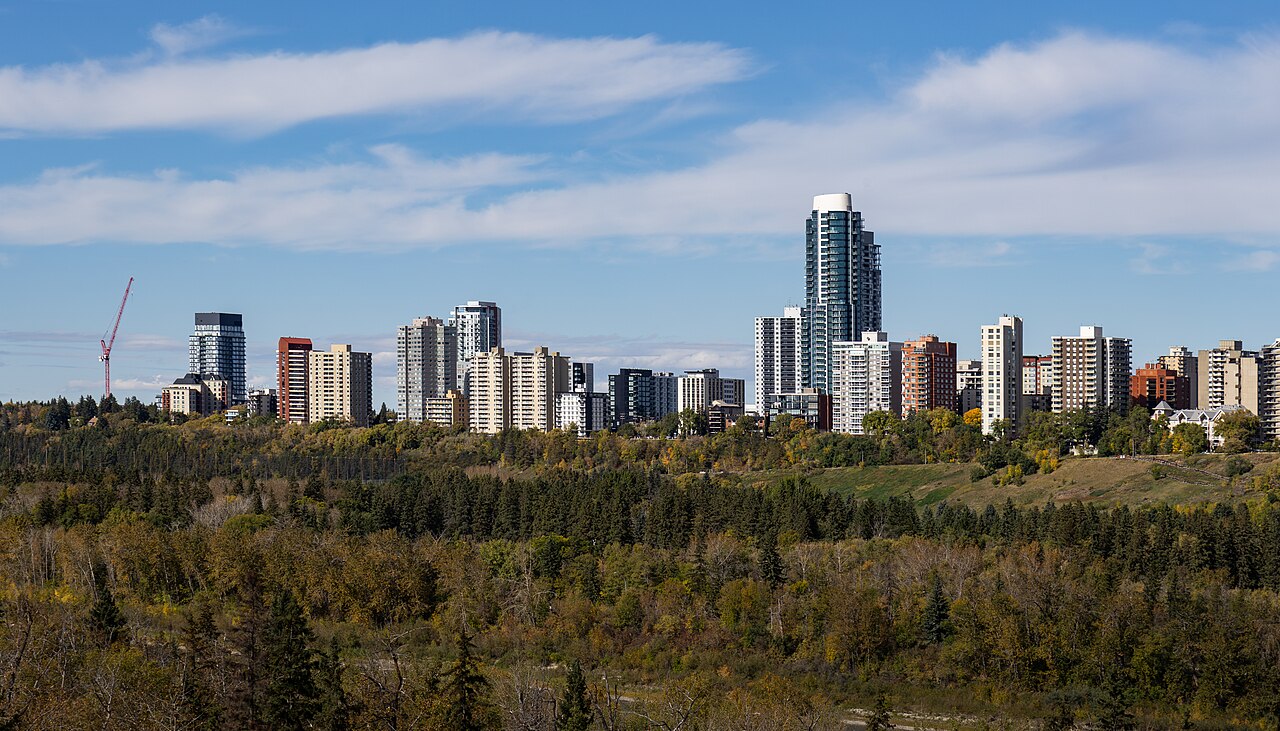
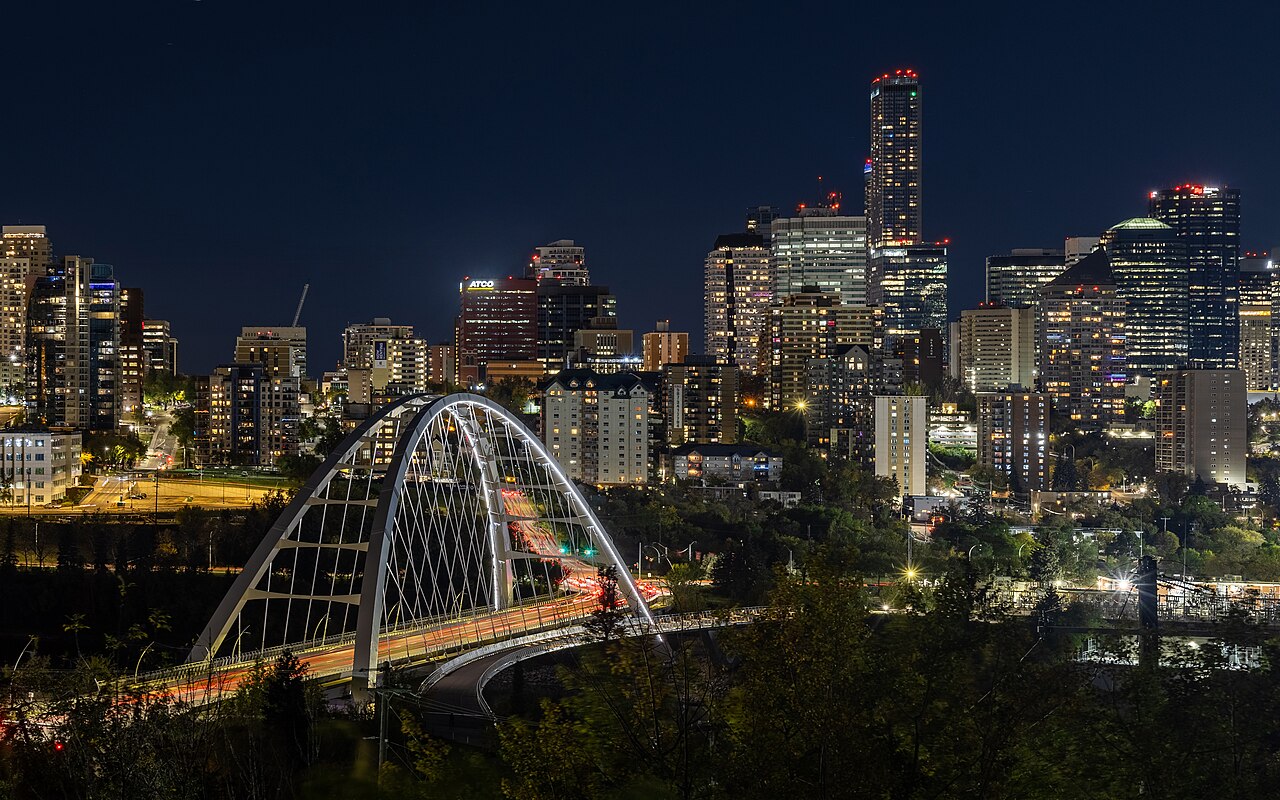
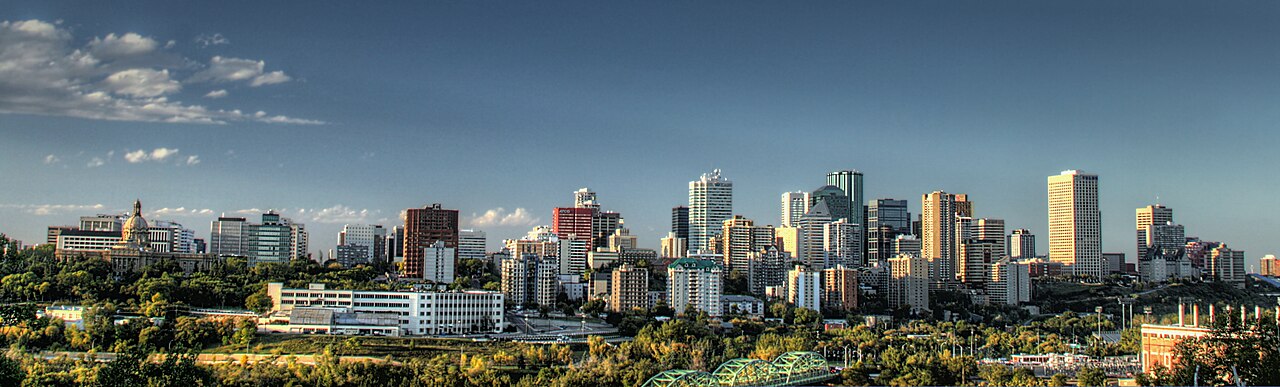
Edmonton skyline
Photo via Wikimedia Commons.

If you have a variable or adjustable-rate mortgage

Your rate is tied to your lender’s prime rate, which lenders typically adjust in the days following a Bank of Canada move. On an adjustable-payment variable, a 0.25% rise works out to roughly $13 more per month per $100,000 owed — about $64 a month on a $500,000 balance with 20 years of amortization left. On a fixed-payment variable, your payment stays the same but more of it goes to interest and less to principal — check where you stand against your trigger rate.

If you have a fixed rate

Nothing changes today. Fixed rates are set by bond yields, not by this decision, and markets had largely priced a hike in before this morning.

Buying or renewing in the next 120 days?

A rate hold can lock today’s fixed pricing while you decide, and if pricing drops before closing you take the lower rate. That window matters more after a hike, not less — especially with the Bank signalling it may need to go further.

A note on posted rates

These posted rates are a starting point — not the final word, and not take-it-or-leave-it. Rates are sometimes negotiable depending on the person and their situation. We work with multiple lenders through BFL Dominion Lending Centres, and those lenders offer different products — sometimes more competitive than the rates shown in any one table, which is one snapshot, not the whole market we can access. Contact us and we’ll shop across lenders for you to find the product and rate that fit your file.

Call Travis Bannert at (780) 720-8240 or start with the Pre-Approval & Refinance Check — I’ll try to call you this week, and if you reply with a good time we can run your exact numbers.

Frequently asked questions

What did the Bank of Canada do on October 28, 2026? It raised its policy rate by 25 basis points to 2.50% — the first increase since July 2023. The next decision is December 9, 2026.

Does a Bank of Canada hike change my fixed mortgage payment? No. A fixed payment stays the same for the whole term. Fixed rates for new borrowers follow bond yields, not the policy rate directly.

How much does a 0.25% rise add to a variable mortgage payment? On an adjustable-payment variable, roughly $13 more per month per $100,000 owed — about $64 a month on a $500,000 balance with 20 years of amortization left.

Have lender prime rates already moved? Not yet on the Dominion Lending Centres posted table checked the morning of October 28 — lenders typically adjust prime in the days following a decision, so check your own lender’s notice before assuming your new payment.

By Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 720-8240 | nextdoormortgages.com
First-Time Buyer Timeline in Edmonton: The Mortgage Milestones at 90, 60 and 30 Days Before Possession

General Travis Bannert 27 Oct

A first Edmonton purchase runs on a countdown most buyers only see in hindsight: at about 90 days out you assemble documents and get a real pre-approval with a rate hold; at 60 days you shop, offer, and convert the pre-approval into a full approval on a specific home; at 30 days the file turns to insurance, lawyer instructions and funding preparation. Work the timeline in that order and possession day is administrative. Compress it, and every stage borrows stress from the next one.

Edmonton first homes and the countdown to possession day

90 days out: documents, down payment trail, pre-approval

Gather the file your lender will actually read: employment letter and pay stubs, Notices of Assessment, and bank statements that show your down payment accumulating — lenders must source the funds, and a down payment with a clean 90-day paper trail is the simplest file in the world to approve. Open or top up the right savings vehicles now (the FHSA-versus-Home Buyers’ Plan comparison is in my FHSA vs RRSP guide), then get the pre-approval done: it sets your real ceiling under the stress test and starts a rate hold that protects the pricing while you shop. The document set is exactly the one in what a broker reviews up front.

60 days out: offer, approval, appraisal

With a signed offer, the file goes property-specific: full underwriting, the appraisal, insurer approval if you are under 20% down, and your financing condition ticking toward its deadline. Protect this window fiercely — no new debts, no job changes, no large unexplained deposits — because the approval is re-verified against the same facts at funding. If the home has insurer-sensitive features (older wiring, a suite, a condo building under review), they surface now, while conditions still let you respond. This is also when parents helping with a gift finalize the gift letter, so the funds are documented before anyone asks.

“The team at NextDoor Mortgages (Mei & Travis) are the absolute best… provided the help I needed in securing my mortgage.” — Yomi Odusanya, Google review

30 days out: insurance, lawyer, funding

Conditions waived, the countdown turns practical: bind home insurance with the lender named, meet your lawyer to sign mortgage and transfer documents, and deliver your remaining down payment and closing funds as instructed — by bank draft, on the lawyer’s schedule, not possession morning. The lender sends instructions to the lawyer, final checks run, and on possession day the funds move and keys release, typically around noon. Start the whole sequence from the beginning at the Pre-Approval & Refinance Check and each stage hands off cleanly to the next.

Frequently asked questions

How long does it take to buy a first home in Edmonton, start to finish?

A prepared buyer commonly takes about three months: a few weeks of document assembly and pre-approval, a shopping and offer period, then a possession typically 30 to 60 days after the accepted offer. Timelines compress for ready files and stretch for new builds, where possession can be a year out.

When should I get pre-approved before buying in Edmonton?

About 90 days before you expect to offer — early enough that the rate hold covers your shopping window and any document problems can be fixed before a specific home and a deadline are involved.

What can delay mortgage funding near possession?

Missing insurance, unsigned documents, unverified down payment funds, or a change in employment or debts discovered at final review. All four are preventable with the 90/60/30 sequence — and all four are emergencies when discovered in the final week.

Buying your first Edmonton home in the next few months and want your countdown built from today? Call (780) 720-8240— I will try to call you this week, or reply with a good time and we will set a phone appointment to set your 90-day plan.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 720-8240 | nextdoormortgages.com
Edmonton Mortgage Myths: What “Waiting for Rates to Drop” Actually Costs Your Qualification

General Travis Bannert 27 Oct

Waiting for mortgage rates to drop before you buy in Edmonton feels like the cautious move — but waiting is a position with its own costs, and right now the direction of travel makes the myth worth examining. The Bank of Canada decides tomorrow, October 28, with forecasters leaning toward the first hike since 2023 (Reuters poll: 19 of 34 economists expect 2.50%; the policy rate sits at 2.25% today). While a borrower waits for lower rates, four other things move too: home prices, their own income and debts, the stress-test qualifying rate, and the inventory of homes that fit them. Any one of those can cost more than a quarter-point of rate saves.

Edmonton homes and the cost of waiting for mortgage rates to fall

The math a quarter-point actually represents

On an adjustable-payment variable mortgage, 0.25% is roughly $13 a month per $100,000 borrowed. That is real money, but put it beside the other side of the ledger: Edmonton’s average price rose 2.9% year over year to $466,080 in September 2026 (REALTORS® Association of Edmonton), and the balanced market at 4.3 months of inventory (Oct 17–23 snapshot) exists now — the selection of homes a buyer can actually choose from this month is part of what waiting spends. A buyer who waits a year for a hypothetical quarter-point while prices rise 2% on a $475,000 home has paid about $9,500 more for the home to save roughly $60 a month. The rate can also be refinanced or not renewed later; the purchase price is permanent.

Your qualification is a moving target too

The stress test qualifies you at the higher of your contract rate plus 2% or the benchmark floor — when contract rates rise, your maximum approval falls, even if your income is unchanged. Income and debts move as well: a car loan taken while waiting reduces approval dollar-for-dollar in the debt ratios, and a job change restarts probation questions. My guide to first-time buyer habits that kill approvals is mostly a list of things people did while “waiting for the right time.” The protective tool costs nothing: a pre-approval with a rate hold locks today’s pricing for its window while keeping you free to take a lower rate if one appears before funding — the mechanics are in my rate hold guide.

“Mei is very detail-oriented, efficient, and managed to secure me a great rate.” — Kani Lo, Google review

When waiting genuinely is right

Waiting is correct when the file is not ready: down payment incomplete, credit actively being repaired on a timeline, employment in probation, or a separation or estate matter unresolved. In those cases the wait is buying qualification strength, not chasing a rate headline. The distinction is the plan: a dated target, a savings schedule, and a rate hold strategy for the final stretch — built through the Pre-Approval & Refinance Check — versus an open-ended hope that next year is cheaper in every direction at once. It rarely is.

Frequently asked questions

Will Edmonton mortgage rates go down in 2027?

Nobody knows, and the current direction of forecasts is the opposite: the Reuters poll of October 21–23, 2026 has a majority expecting a hike on October 28 and another by end-March. Plan on your numbers today; treat any future drop as a refinance opportunity, not a purchase strategy.

What is the mortgage stress test qualifying rate?

You qualify at the higher of your contract rate plus 2 percentage points or the Bank of Canada’s benchmark floor. When market rates rise, the qualifying rate usually rises with them, reducing the maximum mortgage you can be approved for at the same income.

Does a rate hold cost anything?

Rate holds obtained through a broker are generally free and carry no obligation — they reserve today’s pricing for a set period, and if rates fall before you fund, you receive the lower rate instead.

Waiting on the sidelines and want your real numbers — approval, payment and hold — instead of headlines? Call (780) 720-8240 — I will try to call you this week, or reply with a good time and we will set a phone appointment to run them honestly.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 720-8240 | nextdoormortgages.com
Buying a Fixer-Upper in Edmonton: How Purchase Plus Improvements Financing Releases the Money

General Travis Bannert 27 Oct

A Purchase Plus Improvements (PPI) mortgage lets an Edmonton fixer-upper buyer fold renovation costs into the purchase mortgage — but the improvement money is not handed over at possession. The lender approves the total (price plus quoted improvements), funds the purchase portion first, and holds the improvement funds back until the work is complete and verified by an inspection or appraiser visit; then the funds release, usually to pay the contractor. Buyers who plan their cash around that sequence renovate smoothly. Buyers who expect the money up front stall mid-project.

Older Edmonton home planned for renovation after purchase

What qualifies as an improvement

Structural and value-adding work: kitchens, bathrooms, flooring, windows, roofing, furnaces, electrical and plumbing updates, and finishing a basement. Cosmetic luxuries and movable items — furniture, hot tubs, landscaping flourishes — generally do not qualify, and the improvements must be reflected in the property’s value on the final appraisal. Quotes must be in writing from the contractors who will do the work, obtained before your financing condition is waived, because the lender approves the improvement amount from those quotes. The full mechanics, including draw options on larger projects, are in my main guide to Purchase Plus Improvements mortgages in Canada.

The cash-flow reality nobody advertises

Between possession and the release inspection, someone fronts the money: you, your contractor’s payment terms, or a short-term credit line you arranged in advance. Contractors on PPI jobs know the rhythm and usually structure deposits and progress payments around the holdback — get that schedule in writing before work starts. Keep every invoice and receipt: the release is a reimbursement against documented, completed work, and the final appraiser must see the quoted improvements actually done. Scope changes mid-project need lender approval before, not forgiveness after.

“Great rates, fast closing, and excellent customer service.” — Madhav Dhakal, Google review

Which Edmonton homes suit PPI best

Sound-structure homes with dated finishes in established neighbourhoods — the pattern in my guide to the repair side of older homes — where the renovation visibly lifts value. Homes with uninsurable systems are a different conversation: a PPI approval still needs insurance bound for funding, so a knob-and-tube or 60-amp panel problem must be solved inside the plan, which is why those files start with the insurance questions in my old electrical panels guide. Bring the quotes and the plan together through the Pre-Approval & Refinance Check before the offer, and the financing condition becomes a formality instead of a gamble.

Frequently asked questions

How much can I add to my mortgage with Purchase Plus Improvements?

Insured PPI programs commonly allow improvements up to a set percentage of the purchase price or a dollar cap that varies by insurer and lender. Your broker confirms the current limit for your file when the quotes are submitted — do not plan a renovation budget above the program ceiling.

Do I get the renovation money at possession?

No. The purchase portion funds at possession; improvement funds are held by the lender or solicitor and released after the work is complete and verified, against invoices. Arrange how the contractor is paid in the interim before work begins.

Can I do the renovation work myself under PPI?

Lenders generally want licensed contractor quotes and completed-work verification; sweat-equity arrangements are restricted and must be approved in advance. Assume contractor-completed work unless your lender confirms otherwise in writing.

Found an Edmonton fixer-upper and want the renovation financed into the deal properly? Call (780) 720-8240 — I will try to call you this week, or reply with a good time and we will set a phone appointment to structure the quotes, the holdback and your cash bridge.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 720-8240 | nextdoormortgages.com
House Hacking in Edmonton: How Owner-Occupied Rental Income Is Treated When You Qualify

General Travis Bannert 27 Oct

When you house-hack in Edmonton — living in one unit of a duplex or a home with a legal suite while renting the other — lenders do not count the rent the way your spreadsheet does. Depending on the lender and whether the suite is legal, rental income is typically added at a set percentage as an offset against the property’s carrying costs, or partly added to your income, always using market rent from the appraisal when there is no lease history. The strategy absolutely works here; it just has to be qualified on the lender’s formula, not the listing’s promised rent.

Edmonton homes with suites where rental income helps mortgage qualifying

Legal suite vs non-conforming suite: the fork in the file

A legal, permitted suite is a lending asset: its rent can be used in qualifying under the lender’s rental formula, and the property has more appraisal and resale support. A non-conforming or unpermitted suite may be treated as no rental income at all by conservative lenders — you qualify as if the rent does not exist, and any rent you actually collect is gravy, not approval. My guide to homes with legal suites and mortgage qualifying details the documentation that separates the two on a file: permits, separate entrance and fire-safety features your appraiser and insurer will look for.

How the rental math usually runs

For owner-occupied two-unit properties, many lenders apply a rental offset — commonly a percentage of gross rent credited against principal, interest, taxes and heat — while pure investment properties use a stricter rental worksheet with expenses and vacancies factored. Exact percentages are lender-specific and change, so the useful move is having your broker run your actual property through two or three lenders’ formulas before you offer: the same duplex can qualify very differently across the street of lender policy. Down payment follows occupancy: owner-occupied duplexes can qualify under insured programs with a small down payment when the property and borrower qualify, while a purely non-owner-occupied rental generally needs 20% down — the rules my duplex mortgages guide compares for half-duplex and whole-building purchases.

“She got everything done fast and found me a great rate too. Honestly, I felt really taken care of the whole time.” — Vince, Google review

Budget beyond the approval

Qualifying is step one; surviving the first year is the actual plan. Hold a vacancy and repairs reserve from day one, insure the property as a rented occupancy (your insurer must know about the tenancy), and understand your landlord obligations under Alberta’s Residential Tenancies Act. House hacking fails on cash management, not on concept. Set the file up through the Pre-Approval & Refinance Check with the rental formula run in advance, and you will know your real ceiling before you tour a single duplex.

Frequently asked questions

Can I buy an Edmonton duplex with 5% down if I live in one unit?

Potentially yes — owner-occupied two-unit properties can qualify for insured mortgages with a minimum down payment when the borrower and property meet insurer rules. If you will not live there, expect 20% down as a rental purchase.

Does rental income from a basement suite count toward my mortgage qualification?

If the suite is legal and permitted, most lenders will count a portion of its rent under their rental offset or add-back formula. Non-conforming suites are often counted at zero by conservative lenders — have the suite’s status verified before relying on the income.

Is a lease required to use rental income?

Not always for a purchase: where no lease exists yet, lenders commonly use market rent established by the appraisal. An existing lease at fair market rent is the cleanest evidence.

Eyeing an Edmonton duplex or suited home and want the rental math run before you offer? Call (780) 720-8240 — I will try to call you this week, or reply with a good time and we will set a phone appointment to run your numbers under real lender formulas.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 720-8240 | nextdoormortgages.com
Between Offer Acceptance and Possession Day in Alberta: The Mortgage Funding Sequence

General Travis Bannert 27 Oct

Between an accepted offer and possession day in Alberta, your mortgage runs a fixed sequence: full underwriting against the actual property, appraisal, mortgage-insurer approval if your down payment is under 20%, your home-insurance binder, the lender’s instructions to your lawyer, your signing appointment, and finally funding on possession morning, when the lender’s money and your remaining down payment reach the seller’s lawyer and title transfers. Every step has an owner and a deadline — most possession-day stress is just a step that started late.

Edmonton possession day approaching while mortgage funding completes

Step one: the property joins your approval

A pre-approval approved you; the accepted offer adds a specific property, price and possession date, and underwriting re-checks everything together — income documents refreshed if they have aged, the appraisal ordered, condo documents reviewed on a condo purchase. This is the window your financing condition protects, and the sequence my financing condition timelines guide maps day by day. Do nothing in this window that changes your file: no new car loan, no job change without a conversation, no large unexplained deposits.

Step two: insurance binder and lawyer instructions

Your home insurance must be bound — with the lender named as loss payee — before funding, and arranging it takes longer when the home has older wiring, plumbing or a panel an insurer wants answers about. Start the insurance conversation the day conditions are waived, not the week of possession. Once the file is complete, the lender issues mortgage instructions to your lawyer, who prepares the documents, confirms title, and calculates the exact cash you must bring to the signing appointment: remaining down payment plus closing costs, by certified funds or bank draft as the lawyer directs.

“This has been the best customer service experience I’ve had in Canada over the past five years.” — Minsang Lee, Google review

Step three: funding morning and key release

On possession day, your lawyer receives the mortgage funds, combines them with your money, and forwards the total to the seller’s lawyer. Title transfers at Land Titles, and once funds are confirmed received, keys are released — in Alberta, typically around noon on possession day under the standard contract, once the money has landed. If any document in the chain is missing, funding waits, and so do the keys. Files started early through the Pre-Approval & Refinance Check are the ones where this morning is boring. Boring is the goal.

Frequently asked questions

How long does mortgage funding take after conditions are waived in Alberta?

The remaining steps usually run across the weeks between waiver and possession: insurer and lender final review, insurance binding, lawyer instructions and signing. Short possessions (two weeks or less) compress the same steps — possible, but every party must move immediately.

What is an insurance binder for a mortgage?

It is written confirmation from your home insurer that coverage is in place for the property effective on possession, naming the lender as loss payee. Lenders will not fund without it.

When do I need to give my lawyer the down payment money?

At or before your signing appointment, which is typically a few days before possession, by bank draft or certified funds as your lawyer instructs — the exact figure comes from the statement of adjustments your lawyer prepares.

Offer just accepted and want every funding date mapped now, not later? Call (780) 720-8240 — I will try to call you this week, or reply with a good time and we will set a phone appointment to build your step-by-step funding calendar.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 720-8240 | nextdoormortgages.com
When the Lender’s Appraisal Comes In Low in Edmonton: Your Options, In Order

General Travis Bannert 27 Oct

When a lender’s appraisal comes in below your purchase price, the lender lends against the appraised value — not the price you agreed to pay — and the difference becomes your problem to solve before the financing condition deadline. It is not automatically a dead deal. Edmonton buyers have four real options, in the order to try them: challenge the appraisal with better comparable sales, renegotiate the price, cover the shortfall with additional cash, or walk away inside your financing condition if the numbers cannot be made to work.

Edmonton homes valued by lender appraisals against purchase prices

Why appraisals come in low in a balanced market

An appraisal is a licensed appraiser’s opinion of market value built from comparable sold homes — the same sold data your agent used, interpreted more conservatively, and sometimes from a thinner set of comparables in slow segments. In September 2026 the Greater Edmonton Area recorded 1,959 sales with an average price of $466,080 (REALTORS® Association of Edmonton) — a market with enough sales to support most appraisals, but individual pockets, unusual properties and over-asking-price purchases still come in light. Note what an appraisal is not: it is not a home evaluation for pricing your offer, and it is not an online estimate. Three different numbers, three different jobs.

The shortfall math, plainly

Suppose you agreed to pay $500,000 with 20% down — a $400,000 mortgage. If the appraisal lands at $480,000, the lender’s 80% is now $384,000. Your choices are to bring $16,000 more cash (keeping your total commitment the same), renegotiate the price toward $480,000, or combine both. On insured purchases (under 20% down), a low appraisal can also affect the insurer’s approval, which narrows the cash option — another reason the financing condition stays in place until the appraisal is back and accepted. Keep the deadline discipline from my guide to financing condition timelines in Alberta: an appraisal problem found early is negotiable; found after waiver, it is yours.

“She took the time to understand my unique financial situation and offered tailored solutions… I’m now a proud homeowner.” — Ivan, Google review

Challenging an appraisal — when it works

Appraisers reconsider when presented with genuinely better comparable sales they missed: a similar home, closer, more recent, that sold for more. They do not reconsider because the buyer is disappointed, and submitting your own listing agent’s asking-price comparables helps no one. Ask your broker whether a reconsideration, a second appraisal with a different lender, or a straight renegotiation is strongest in your case — then do it inside the condition window, with the seller’s side informed through your agent. Start files early through the Pre-Approval & Refinance Check so appraisal timing never collides with your waiver date.

Frequently asked questions

Does the lender use the purchase price or the appraised value?

The lender uses the lower of the two for calculating your maximum mortgage. If the appraisal is higher than the price, the price governs; if it is lower, the appraisal governs and the gap must be covered, renegotiated or resolved under your conditions.

Can a low appraisal kill an insured mortgage in Canada?

It can complicate one: the mortgage insurer must also accept the value. If neither the lender nor the insurer will proceed at the agreed price, a financing condition lets you exit with your deposit protected, provided you act before the deadline.

Who pays for the appraisal in Alberta?

It varies — some lenders cover it, others pass the cost to the borrower, and brokers sometimes absorb it. Confirm who pays when your application is submitted so it is not a surprise line item.

Offer accepted in Edmonton and worried about the appraisal step? Call (780) 720-8240 — I will try to call you this week, or reply with a good time and we will set a phone appointment to map your condition dates and your shortfall options before they are urgent.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 720-8240 | nextdoormortgages.com
New-Home Closing Costs in Alberta: Planning Funds to Close Beyond the Down Payment

General Travis Bannert 27 Oct

On a new-build purchase in Alberta, the cash you need on possession day is your remaining down payment plus a closing-cost layer that resale buyers never see in the same form: legal fees, GST on the new home, utility hookup charges, landscaping deposits or obligations, and development levies written into the builder contract. Lenders test whether you actually have these funds — the standard planning rule remains roughly 1.5% of the purchase price for closing costs on top of the down payment, and new builds are exactly where that buffer gets used. Budget the full number at contract signing, not in the month before possession.

Edmonton new neighbourhoods where closing costs include hookups and levies

The line items, one by one

Legal fees and disbursements cover your lawyer’s work, Land Titles registration and the statement of adjustments. GST is the big one unique to new homes: it applies to the purchase price (your contract states whether the quoted price is net of GST or plus GST — the two readings differ by thousands of dollars, so know which you signed; my GST guide linked from my builder deposit explainer walks through the mortgage effect). Utility hookups, appraisal fees, and any builder-charged items — fencing, deck or landscaping deposits, Homeowners Association or community fees in newer neighbourhoods — complete the list. Alberta has no provincial land transfer tax, which is the one closing-cost mercy Edmonton buyers get that Toronto buyers do not.

How your lender looks at funds to close

Underwriting adds it up: purchase price, plus GST where payable, plus estimated closing costs, minus deposits already paid, minus the approved mortgage. The remainder must be sitting in your accounts, sourced and seasoned, when the file is reviewed — and reviewed again before funding on long builds. A shortfall discovered at the final review is not a small problem; it can delay funding past the builder’s possession date, which triggers its own contractual consequences. This is one of the quiet ways approvals fall apart late, the pattern in my guide to what can make a mortgage approval fall apart.

“The team at NextDoor Mortgages (Mei & Travis) are the absolute best… provided the help I needed in securing my mortgage.” — Yomi Odusanya, Google review

Build the closing fund on day one

Open the contract, list every charge the builder can pass through, add legal and GST, then hold that total untouched in a separate account while the home is built. If the estimate is wrong, be wrong on the high side — surplus closing funds become your first lump-sum prepayment or your furniture budget, while a shortfall becomes a crisis. Set the number up properly through the Pre-Approval & Refinance Check at the same time as the deposit schedule, so one plan covers the whole build.

Frequently asked questions

How much should I budget for closing costs on a new build in Alberta?

A common lender planning standard is about 1.5% of the purchase price for closing costs beyond the down payment, plus GST on the new home itself where the contract price is quoted plus GST. Your builder contract’s specific charges decide the real figure — itemize it rather than relying on the rule of thumb alone.

Does Alberta charge land transfer tax?

No. Alberta does not levy a provincial land transfer tax, though Land Titles registration fees apply. That is a material saving compared with Ontario or British Columbia purchases.

Can closing costs be added to my mortgage?

Generally no — closing costs and any GST owing must be available from your own funds at closing, which is why lenders verify them. Some insured programs have limited flexibility products, but the safe plan is cash on hand.

Building new in Edmonton and want your funds-to-close number calculated from your actual contract? Call (780) 720-8240 — I will try to call you this week, or reply with a good time and we will set a phone appointment to itemize it line by line.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 720-8240 | nextdoormortgages.com

Builder Deposit Schedules in Alberta: How Your Deposits Interact With Your Mortgage

General Travis Bannert 27 Oct

When you buy a new-build home in Edmonton, your deposits are paid to the builder in stages across the build — an initial deposit at contract, further amounts at milestones set in the purchase agreement — and that money is credited toward your purchase price at possession, reducing what your mortgage and remaining down payment must cover on funding day. Your lender needs a paper trail for every dollar: deposit receipts from the builder must match the contract schedule, because underwriting reconciles total funds to close — price, plus GST where it applies, plus closing costs, minus deposits already paid.

Edmonton new build buyers planning deposits and mortgage funding

When deposits are typically paid

Schedules are set by the builder’s contract, not by law, so read yours rather than assuming. A common pattern is an initial deposit on signing, a second instalment after selections or at a construction stage, and the balance of the agreed deposit structure before possession. Spec and quick-possession homes compress this into weeks; a full build can stretch it past a year. Each payment date is a real cash deadline that exists independently of your mortgage — the mortgage does not exist until funding day, so deposits come from your own funds as they fall due.

What your lender needs to see

Every deposit receipt, the full contract with its deposit schedule, and bank statements showing where the deposit money came from — lenders verify source of funds for anti-fraud and anti-money-laundering compliance, and unexplained deposits into your account create exactly the kind of problem my guide to what documents a broker reviews up front exists to prevent. Keep the trail boring: same account, clear transfers, receipts filed. If family is helping with a deposit instalment, tell your broker before the money moves, not after underwriting asks.

“Mei is very detail-oriented, efficient, and managed to secure me a great rate.” — Kani Lo, Google review

The long-build trap: approval timing

A mortgage approval obtained at contract signing does not survive a 14-month build untouched — rate holds expire, documents go stale, and you will be re-qualified closer to possession. My guide to new-build mortgage approvals in Edmonton covers the rate-hold and re-qualification strategy in full. The deposit-side rule is simpler: never let a deposit deadline push you into a financial move — a new car loan, a drained account — that breaks the approval you will need at the end. Plan the whole cash staircase at the start, through the Pre-Approval & Refinance Check, deposits included.

Frequently asked questions

Do builder deposits count toward my down payment?

Yes. Deposits paid to the builder are credited against the purchase price at possession and form part of your total down payment — your mortgage funds the balance. Your lender verifies them with the builder’s receipts.

Can I get deposit money back if my mortgage falls through on a new build?

It depends entirely on your purchase contract with the builder — new-build contracts are typically firm once signed and conditions are removed, and deposits are generally not refundable. This is why mortgage planning happens before you sign, not after.

Does GST apply to my new-build deposits in Alberta?

GST applies to the purchase price of a new home in Alberta, and deposits are instalments toward that price. How GST is calculated and funded at possession is covered in my guide to GST on a new home and your mortgage — confirm your contract states whether the price is net or plus GST.

Signing with an Edmonton builder and want the deposit staircase and the mortgage planned together? Call (780) 720-8240— I will try to call you this week, or reply with a good time and we will set a phone appointment before your first deposit deadline.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 720-8240 | nextdoormortgages.com

Self-Employed in Alberta? How Stated-Income Mortgage Approvals Actually Work

General Travis Bannert 27 Oct

A stated-income mortgage approval lets a self-employed borrower qualify on a reasonable income they state — supported by proof the business exists and is active — instead of only the net income left on their tax return after write-offs. It exists because good tax planning and mortgage qualifying pull in opposite directions: every legitimate expense that lowers your taxable income also lowers the income a traditional lender can use. Stated-income programs through alternative (B) lenders and some insurer programs bridge that gap, at a price: expect a larger down payment, full two-year tax compliance, and a rate above best A-lender pricing.

Edmonton business owners and self-employed mortgage approvals

Who stated income is actually for

Business-for-self owners, incorporated contractors, sole proprietors and commission earners whose Notices of Assessment understate their real earnings. It is not for hiding income, and it is not available just because the numbers are inconvenient: lenders verify the business is real and operating — business licence or articles of incorporation, GST/HST filings, business bank statements showing revenue, and a track record, commonly two years in the same field. My document checklist in self-employed mortgage documents in Canada is the companion piece — stated income changes which income figure is used, not how much paperwork proves it.

What lenders still require, even on stated income

Your taxes must be filed and up to date, with any balance owing paid — an outstanding CRA balance can sink any approval. Credit must be strong; stated-income files lean harder on your credit history because the income is less conventionally proven. The stated figure must be reasonable for your industry and business size: stating double what your bank statements support gets the file declined, not approved. And the property must be marketable and owner-occupied or a standard rental — exotic files need not apply.

“Great rates, fast closing, and excellent customer service.” — Madhav Dhakal, Google review

The honest trade-offs

Stated-income approval trades rate for access: B-lender rates sit above A-lender rates, sometimes with lender or broker fees, and insured stated-income programs have their own premium and eligibility rules. For many Alberta business owners that trade is plainly worth it — the alternative is waiting two tax cycles to show higher net income while prices and rates move. The right comparison is total cost over the term you will actually hold, including the refinance path into an A lender once two stronger tax years exist. Run that plan before you sign, through the Pre-Approval & Refinance Check, so the exit is designed at entry.

Frequently asked questions

What is a stated income mortgage in Canada?

It is a mortgage where a self-employed borrower’s income is stated and verified for reasonableness — with business documentation and bank statements — rather than taken solely from net income on tax returns. It is offered mainly by alternative lenders and specific insurer programs.

How much down payment do I need for a stated income mortgage?

More than a standard A-lender file, in most cases. Uninsured B-lender purchases commonly need at least 20% down, and stronger files put down more. The exact requirement depends on the lender, credit and property.

Do I still need my taxes filed for a stated income mortgage?

Yes. Lenders require current tax filings and Notices of Assessment, and CRA balances owing generally must be paid. Stated income changes how income is assessed, not whether tax compliance is checked.

Self-employed in Alberta and tired of your tax return deciding your mortgage? Call (780) 720-8240 — I will try to call you this week, or reply with a good time and we will set a phone appointment to review your business documents and which lender type fits your file.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 720-8240 | nextdoormortgages.com

For self-employed mortgage programs in Edmonton, see Self-Employed Solutions.