Reuters Poll Flips: Most Economists Now Expect a Bank of Canada Hike on October 28 — What Edmonton Borrowers Do This Weekend

General Travis Bannert 24 Oct

The forecast for the Bank of Canada’s October 28 decision flipped this week: a Reuters poll of economists conducted October 21-23 found 19 of 34 — 56% — now expect a 25-point hike to 2.50%, after the previous poll had 80% expecting a hold at 2.25% through the end of 2026. Edmonton borrowers with a renewal, closing, or variable mortgage have this weekend to get a rate hold and a two-outcome plan in place before Tuesday’s announcement. See the decision itself, explained for Edmonton borrowers.

What changed the forecast in one week?

The Bank’s own Business Outlook Survey. It showed inflation expectations rising sharply as trade talks with the United States broke down, and Governor Tiff Macklem’s remarks last weekend were widely read as a hint a hike is coming. Desjardins’ Royce Mendes said the survey responses changed both the Governor’s tone and economists’ views: “the survey responses… suggest there are more serious inflationary pressures coming.” Markets moved with them — interest-rate futures went from pricing a roughly 30% chance of an October hike to about three-in-four. September inflation at 3.1%, just above the Bank’s 1-3% target range, and oil touching $117 a barrel on Friday complete the case the hike camp is making. See the earlier Oxford-C.D. Howe split this poll overtook.

What does the poll expect after October?

A short campaign, not a cycle. Sixteen of 29 respondents expect one more hike before March 2027, taking the policy rate to 2.75%, and then a hold — which Reuters noted would be the shortest Bank of Canada tightening campaign in 30 years. The hold camp’s argument is the other half of the data: a weak economy, growth expected at just 1.0% in 2026, and subdued inflation once energy is stripped out. BMO’s Benjamin Reitzes summed up the hike logic: the Bank would rather hike slightly early than fall behind the curve as it did in 2021-22.

“Great rates, fast closing, and excellent customer service.” — Madhav Dhakal, Google review
Edmonton mortgage borrowers preparing for a possible rate hike

Photo via Wikimedia Commons.

What should Edmonton borrowers do before Tuesday?

If your mortgage renews or your purchase closes within about 120 days, ask for a rate hold now — it costs nothing and caps your exposure whichever way Tuesday goes; start with a Mortgage Renewal Check if your term is ending. If you hold a variable mortgage, know in advance what a 25-point rise does to your payment or your amortization. And remember fixed rates follow bond yields, which have already been repricing on these expectations — waiting for the announcement does not freeze today’s fixed offers. First-time buyers should pair the hold with the steps in the First Home Guide for Edmonton. See why a rate hold is this weekend’s move.

Renewing, closing, or holding a variable rate into Tuesday’s decision? Call me at (780) 722-5621 this weekend and we will run both outcomes on your actual balance before October 28. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Rental Property Mortgages in Canada: Down Payment and Rental Income Rules for Small Landlords

General Travis Bannert 23 Oct

A non-owner-occupied rental property in Canada generally requires at least 20% down, and lenders qualify you using only part of the rent — through an offset or an add-back formula that varies by lender and insurer. That gap between the rent a property actually collects and the rent a lender will count is where most small-landlord applications succeed or fail.

How much down payment does a rental purchase need?

If you will not live in the property, plan on 20% or more down and uninsured financing rules. If you will live in one unit of a small multi-unit property, insured options with a smaller down payment may be available under the applicable insurer rules for owner-occupied properties — the distinction is genuine occupancy, not intent, and lenders verify it. Either way, your other debts, your credit, and your non-rental income still carry the file: rent supports the application, it does not replace you as the borrower. For condo rentals, see condo rentals: why the building gets reviewed too.

How do lenders count rental income?

Two main methods. A rental offset treats a percentage of the rent as offsetting the property’s carrying costs directly. An add-back adds a percentage of the rent to your income and puts the full property costs into your debt ratios. The percentage counted, and how taxes, heat and vacancy are treated, differ between lenders and insurers — which is why the same property can qualify comfortably at one lender and miss at another. Existing rental properties in your portfolio get the same treatment, so bring leases and tax filings for every property you own, not just the one you are buying. Self-employed landlords should also review self-employed landlords: the documents lenders average.

“The team at NextDoor Mortgages (Mei & Travis) are the absolute best… provided the help I needed in securing my mortgage.” — Yomi Odusanya, Google review

Edmonton small landlord rental property

Photo via Wikimedia Commons.

What else should Edmonton small landlords prepare?

A realistic expense picture: property taxes, insurance at landlord rates, maintenance, and vacancy allowance — lenders think in these terms even when a property’s listing reports a gross rent alone. Edmonton helps the math more than most cities: CMHC’s Fall 2026 supply report found Edmonton is the only large Canadian market with no housing supply gap, keeping purchase prices — and therefore the rent-to-price relationship — more workable for small landlords than in supply-short markets. You still need to qualify at the stress-test rate, and rental rates used in qualifying follow lender policy, not the highest rent you hope to achieve. For a rental that needs work, see purchase plus improvements for a rental that needs work.

If you already own a rental and your mortgage is renewing, run a Mortgage Renewal Check before signing — rental files are exactly where one lender’s income formula can beat another’s by enough to matter.

Buying your first Edmonton rental, or adding a second property? Call me at (780) 722-5621 and we will test the property against several lenders’ rental formulas before you offer. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Mortgage Payment Frequency in Canada: Weekly, Accelerated and Lump Sums Explained

General Travis Bannert 23 Oct

The word “accelerated” is what saves you money in a payment frequency — not weekly or bi-weekly by itself. An accelerated bi-weekly payment takes your monthly payment, divides it by two, and collects it every two weeks, which quietly adds one extra monthly payment a year and cuts years of interest over an amortization.

What are the standard frequency options?

Monthly is the baseline: twelve payments a year. Semi-monthly collects half a monthly payment twice a month — twenty-four payments totalling exactly the same as monthly. Regular bi-weekly collects every two weeks based on dividing the year differently, totalling roughly the same as monthly. Accelerated bi-weekly and accelerated weekly are the versions that overpay on purpose: because there are twenty-six bi-weekly periods in a year, twenty-six half-monthly payments equal thirteen monthly payments — one full extra payment annually, applied against principal and interest over time.

How much difference does the extra payment make?

It depends on your balance, rate and remaining amortization, but the direction never changes: more principal paid earlier means less interest charged on every payment after it. On a typical mortgage held to term, one extra monthly payment a year commonly shortens the amortization by several years. The honest way to see your number is an amortization comparison on your actual balance — I run both versions side by side for clients, because the generic online examples rarely match a real file. See 25-year vs 30-year amortization: the payment trade-off.

“She took the time to understand my unique financial situation and offered tailored solutions… I’m now a proud homeowner.” — Ivan, Google review

Edmonton homeowner setting mortgage payment frequency

Photo via Wikimedia Commons.

What about lump sums and payment increases?

Frequency is one lever; your prepayment privileges are the other. An annual lump sum within your privilege limit, or a permanent payment increase, can outpace even accelerated frequency — and the two combine. The discipline that matters is matching payments to your pay schedule so the account is never strained: an accelerated plan you abandon after six months loses to a plain plan you keep for twenty years. If your income is irregular — common for self-employed borrowers — a monthly payment plus voluntary lump sums often fits better than a rigid accelerated schedule. See open vs closed: whether your term lets you pay faster.

Set the frequency at origination, then revisit it at every renewal. A Mortgage Renewal Check is a good moment to recalculate what your current frequency is actually doing to your payoff date.

Want your real payoff dates compared — monthly vs accelerated, with and without a lump sum? Call me at (780) 722-5621 and bring your current balance and rate. See also fixed vs variable, and which payment behaviour each rewards, or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Open vs Closed Mortgages in Canada: Prepayment Privileges That Actually Matter

General Travis Bannert 23 Oct

A closed mortgage trades flexibility for a lower rate: you may prepay only within set privileges, and leaving early triggers a penalty. An open mortgage lets you repay or leave at any time without penalty, at a noticeably higher rate. For most Edmonton borrowers, a closed mortgage with generous prepayment privileges is the sweet spot — if you actually read the privileges before signing. See fixed vs variable: payment, penalty and flexibility compared.

What prepayment privileges do closed mortgages include?

Two kinds, both lender-specific. Lump-sum privileges let you pay an extra percentage of the original balance each year — commonly in the range of 10% to 20% depending on the lender and product — without penalty. Payment-increase privileges let you raise your regular payment by a set percentage, which quietly shortens your amortization. Some products restrict both sharply in exchange for a slightly lower rate; those “no-frills” trade-offs are where borrowers get trapped, because the rate saving is small and the lost flexibility is permanent for the term. See using payment frequency and lump sums inside a closed term.

When is an open mortgage worth its higher rate?

When you know money is coming or a change is booked: a home you expect to sell within months, an estate settlement or inheritance arriving soon, a planned move for work, or a short bridge between situations where certainty of exit matters more than rate. Open terms are usually short — six months or one year — and are priced as flexibility products. Holding an open mortgage for years “just in case” is paying a premium every month for an exit you never use.

“She got everything done fast and found me a great rate too. Honestly, I felt really taken care of the whole time.” — Vince, Google review

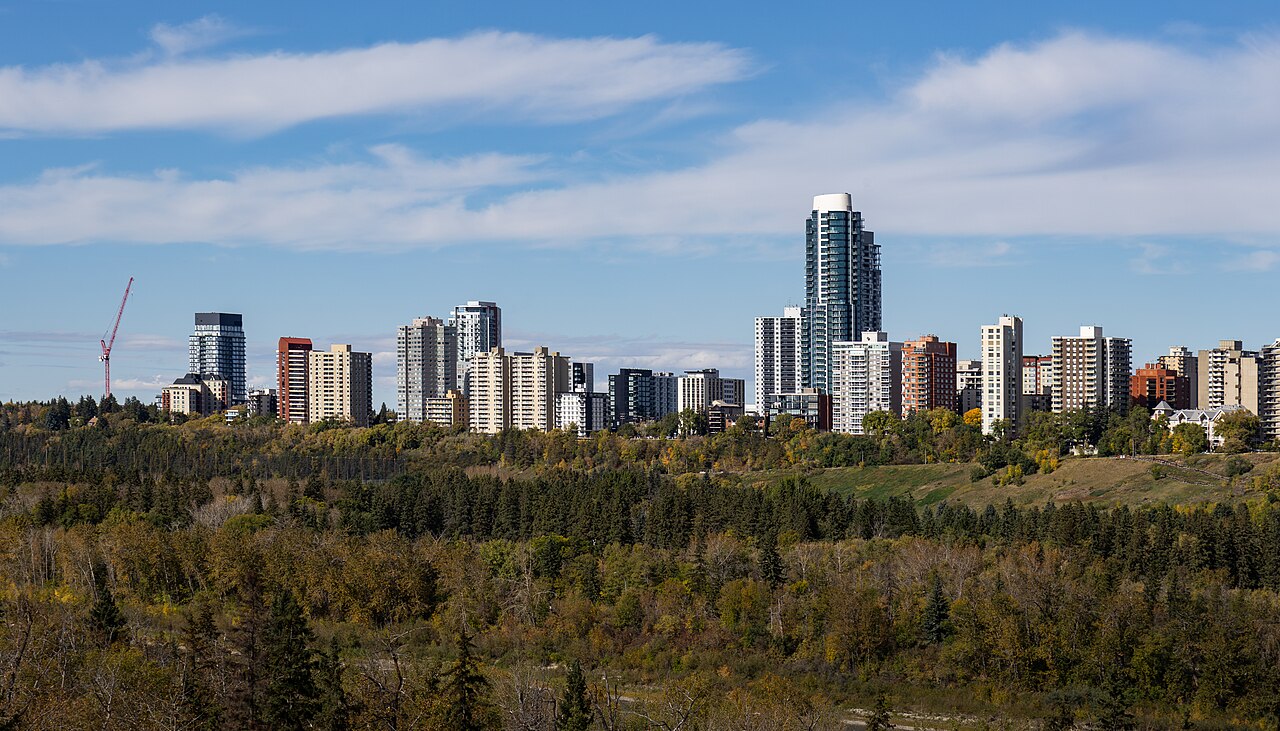
Edmonton homeowner reviewing mortgage prepayment privileges

Photo via Wikimedia Commons.

How should you choose?

Estimate honestly how much extra you will actually prepay — most borrowers use far less than their maximum privilege — then compare lenders on both rate and privilege percentages together. If a sale or refinance is even a possibility mid-term, also compare penalty formulas: on fixed mortgages the interest rate differential calculation varies widely between lenders, and that difference can exceed every other feature combined. This comparison is a standard part of a Mortgage Renewal Check — privileges and penalties, not just the rate on the letter. See the two penalty formulas, worked through.

Choosing between open, closed, and a low-rate restricted product? Call me at (780) 722-5621 and we will match the privileges to how you will really use the mortgage, or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Cash-Back Mortgages in Canada: Who Pays for the “Free” Money?

General Travis Bannert 23 Oct

You pay for a cash-back mortgage — through a higher interest rate over the full term, and through a clawback that can demand part of the cash back if you leave the mortgage early. For a borrower who will stay the full term and genuinely needs the cash for the home, it can still be a rational tool; for everyone else, the “free” money is usually the most expensive money in the file.

How does a cash-back mortgage work?

The lender gives you a percentage of your mortgage amount as cash at funding, on top of the mortgage itself. In exchange, your rate is higher than the same lender’s best rate for that term. The difference seems small as a percentage; multiplied by your balance and five years of payments, it commonly totals more than the cash you received — which is the business model, and it is not hidden, just rarely added up out loud.

What is the clawback?

If you break the mortgage before the term ends — selling, refinancing, or switching — the lender typically requires repayment of a pro-rata share of the cash back, on top of any interest penalty that applies. That double cost is why cash-back mortgages punish exactly the people most likely to move early: first-time buyers whose lives change fastest. If there is a realistic chance you will not finish the term, the clawback math belongs in your decision from day one. Also note open vs closed: the flexibility a cash-back term usually gives up.

“Mei is very detail-oriented, efficient, and managed to secure me a great rate.” — Kani Lo, Google review

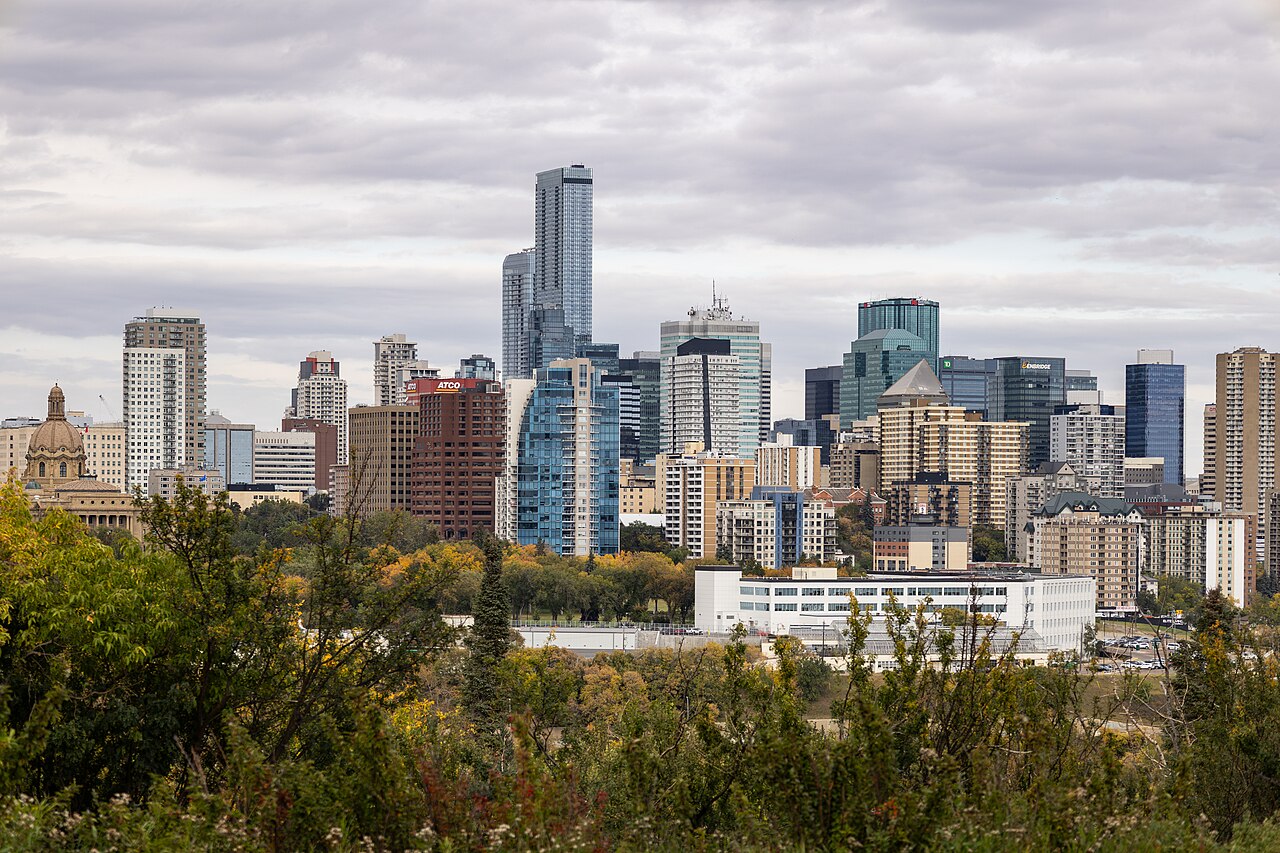
Edmonton mortgage borrower comparing cash-back costs

Photo via Wikimedia Commons.

When can cash-back still make sense?

When the cash funds something essential to the purchase — furnishing a first home, or necessary immediate repairs — you have compared the total cost against alternatives like a smaller purchase-plus-improvements structure or saving longer, and you are confident you will stay the full term. It never makes sense as spending money, and it cannot be used to manufacture a down payment: lenders require your minimum down payment to come from your own verifiable resources under the applicable rules. For cheaper ways to the same cash, see HELOC vs equity loan vs refinance: cheaper ways to the same cash.

Compare any cash-back offer against the lender’s best-rate version of the same mortgage, in total dollars over the term. If you are renewing, a Mortgage Renewal Check runs that comparison on your file; first-time buyers should read the First Home Guide for Edmonton before signing any “free money” offer.

Offered cash back with a mortgage? Call me at (780) 722-5621 and we will add up what it actually costs before you decide. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Blend-and-Extend Mortgages in Canada: When Averaging Your Rate Helps and When It Hurts

General Travis Bannert 23 Oct

A blend-and-extend averages your current mortgage rate with today’s rate for a new, longer term — letting you lower a high payment or borrow more without paying a break penalty — at the cost of committing to your current lender for longer, often without testing the wider market. It helps when the blended result beats your alternatives after all costs; it hurts when waiting for renewal would have been free. See the renewal letter trap this option competes with.

How does the blend actually work?

Your lender weights the two rates by balance and remaining time: part of your money keeps something close to your existing rate, and the new money — a longer term, or additional borrowed funds on a blend-and-increase — is priced at current rates. The result is a single new rate somewhere between the two, on a fresh term that restarts your clock. No penalty is charged because you never leave the lender — which is precisely the lender offers it.

When does blending help?

When your current rate is far below today’s rates and you need more money or a longer runway, blending protects part of that cheap rate while you extend. When your current rate is far above today’s, blending down can cut your payment immediately without a penalty — but compare it against breaking and switching, because sometimes paying a modest penalty on a variable mortgage, or waiting a few months to renewal, produces a much lower rate than any blend your current lender will offer.

“Great rates, fast closing, and excellent customer service.” — Madhav Dhakal, Google review

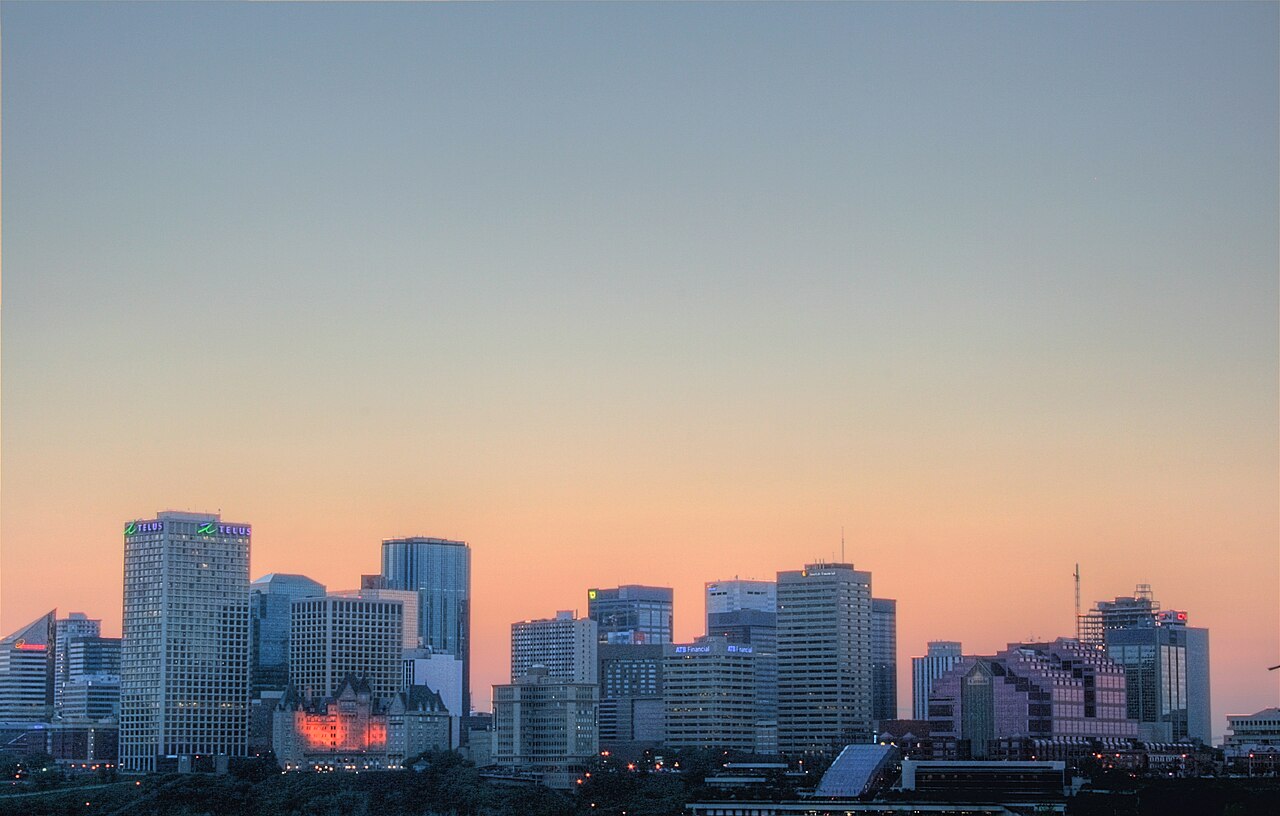
Edmonton homeowner reviewing blend and extend mortgage options

Photo via Wikimedia Commons.

What are the traps?

You are negotiating with one lender who knows leaving costs you a penalty — the first blended offer is rarely the best that lender can do, and it is never compared against the wider market unless you compare it yourself. Blending also restarts a full term, which can strand you if you expect to move. And a blend-and-increase adds debt against your home: the payment math must work at the stress-test qualifying rate, not just at the blended contract rate. The alternative to compare is switching lenders at renewal, step by step.

Run the three-way comparison — blend, break-and-switch, wait for renewal — before you sign anything. A Mortgage Renewal Check covers the renewal-timing version of that math. See also breaking instead of blending: what the penalty would be.

Your lender offered you a blend? Call me at (780) 722-5621 before you accept — I will run it against the break and wait options on your real balance and penalty.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Renewing With a New Lender in Canada: What a Mortgage Switch Involves Step by Step

General Travis Bannert 23 Oct

Switching lenders at renewal means your existing mortgage balance moves to a new lender at the end of your term — no penalty, because you are not breaking anything — in exchange for a better rate, better terms, or both. It involves a fresh application and approval, so it rewards starting three to four months before your renewal date, not the week your current lender’s letter arrives. See why your bank’s first renewal offer is rarely its best.

What is the difference between a switch, a transfer and a refinance?

A switch or transfer keeps the same balance, the same amortization, and the same borrowers on title — you are changing who holds the mortgage, on new terms. A refinance changes the structure: a larger balance, a longer amortization, added borrowers, or cash out. That distinction matters because a straight switch is simpler, often qualifies under insured-switch rules where they apply, and may not require a new appraisal — while a refinance is underwritten as a bigger change and priced accordingly.

What are the steps, in order?

First, a comparison: your current lender’s renewal offer against what other lenders will actually approve, including rate, term, penalty formula, portability and prepayment privileges — not rate alone. Second, an application with income and property documentation, similar to your original purchase file. Third, approval and instructions to a lawyer or title service to discharge the old mortgage and register the new one on your renewal date. Fourth, confirmation after funding that the old balance is discharged and your new payment schedule is correct. Many lenders cover some switch costs, such as appraisal or transfer fees, as part of their offers — confirm what is covered in writing, because “free switch” claims vary.

“The team at NextDoor Mortgages (Mei & Travis) are the absolute best… provided the help I needed in securing my mortgage.” — Yomi Odusanya, Google review

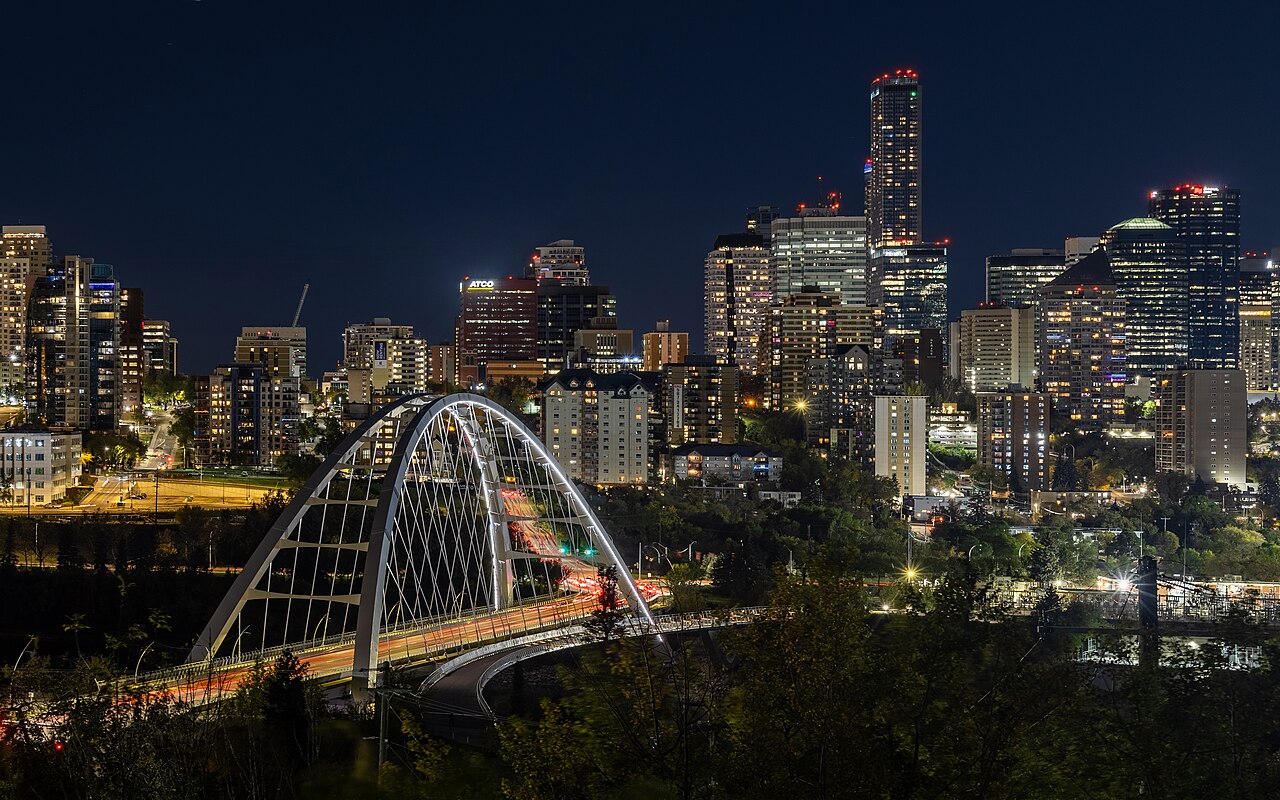
Renewing a mortgage with a new lender in Edmonton

Photo via Wikimedia Commons.

When does switching not make sense?

When your current lender matches the market on a full comparison, when you plan to sell or refinance within the new term and the new lender’s penalty or portability rules are worse, or when your income or credit has changed enough that a new approval is risky — your existing lender’s renewal requires no re-qualification, and that safety has real value on some files. That honest comparison is exactly what a Mortgage Renewal Check is for: we review your lender’s offer against live alternatives and switch only when the full picture — not the headline rate — says so. As the stay-put alternative, see blend-and-extend as the stay-put alternative. And if a move is also on the table, see porting instead of switching, if you’re also moving.

Renewal coming up in the next four months? Call me at (780) 722-5621 and we will time the switch so your current term never needs breaking.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Newcomer Mortgages in Canada: Work Permits, Credit Alternatives and Down Payment Rules

General Travis Bannert 23 Oct

New Canadians can qualify for a mortgage in Canada without a long local credit history — lenders and insurers run dedicated newcomer programs that substitute other proof: immigration status and work authorization, employment and income confirmation, international credit references or documented rent and bill payments, and a verified down payment. The file is built on documentation, so starting the paper trail early is the whole strategy.

Who counts as a newcomer for mortgage purposes?

Programs generally serve permanent residents who arrived recently and, under separate rules, temporary residents holding a valid work permit. Your status determines which programs you can use, the maximum property value and loan-to-value available, and how much down payment is required — so the first step is confirming your exact status category and how long you have been in Canada, because program windows are time-limited from your arrival date.

How do you prove creditworthiness without a Canadian credit file?

Lenders can consider an international credit report from your home country where available, reference letters from a bank you dealt with before moving, and a documented history of paying rent, utilities and other obligations on time — commonly over the most recent 12 months. Open a Canadian bank account early, keep every rent receipt and utility record, and avoid missed payments on any new Canadian credit you establish: a thin file with a clean recent pattern is workable, while a thin file with a recent late payment is a problem you created after arrival. For the longer credit journey, see building or rebuilding credit for a mortgage.

“She took the time to understand my unique financial situation and offered tailored solutions… I’m now a proud homeowner.” — Ivan, Google review

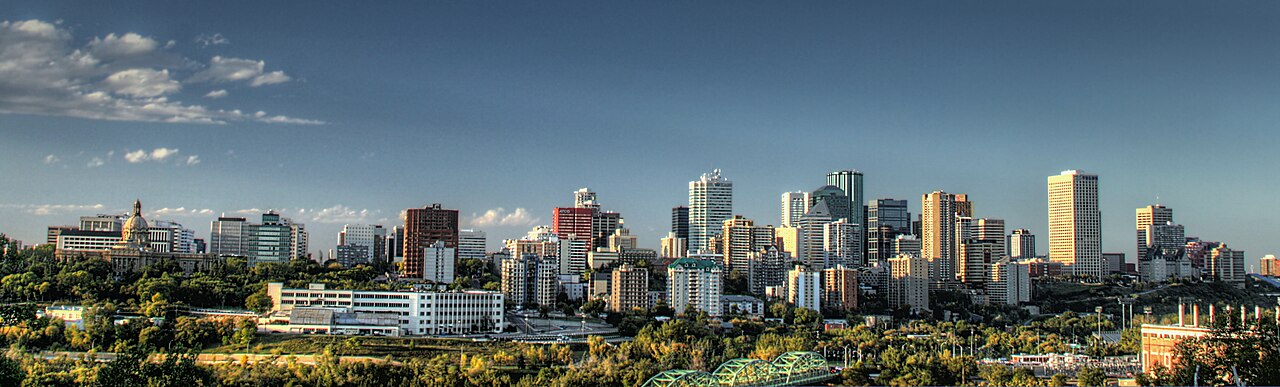
New Canadians buying a home in Edmonton — Walterdale Bridge

Photo via Wikimedia Commons.

What down payment and income rules should newcomers expect?

Your down payment must be verifiable and in Canada with a clear paper trail — large transfers from abroad need documentation of their source and path, arranged well before you write an offer. Insured newcomer purchases are capped by the same $1.5 million insured limit that applies to everyone, and programs set their own minimum down payment by status and property type. Income is verified through Canadian employment where you have it, with program-specific treatment of foreign income history. Edmonton helps newcomers more than most markets: CMHC’s Fall 2026 report found Edmonton is the only large Canadian market with no housing supply gap, which is one reason prices here remain within reach of a first Canadian purchase. Newcomer business owners should also see self-employed documentation for newcomer business owners.

Pair this with the First Home Guide for Edmonton for the purchase sequence, and use a Mortgage Renewal Check only later — your first file is a purchase pre-approval, built early.

New to Canada and planning an Edmonton home purchase? Call me at (780) 722-5621 — the earlier we build your documentation file, the more programs stay open to you. Also follow the first-time buyer journey, newcomer edition, and for settling in, see relocating to Edmonton: the realtor newcomers actually get referred to. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
HELOC vs Home Equity Loan vs Refinance in Canada: Three Ways to Borrow Against Your Home

General Travis Bannert 23 Oct

A HELOC gives you revolving credit you can draw and repay repeatedly, a home equity loan gives you one lump sum at a fixed structure, and a refinance replaces your mortgage with a larger one — all three borrow against your home, but they differ in rate type, flexibility, and what happens if your plans change. Choosing by the shape of your spending, not just the rate, is what keeps the cheapest option from becoming the most expensive one. For the no-payment alternative, see reverse mortgages: the no-payment equity option for 55+.

How does a HELOC work in Canada?

A home equity line of credit is revolving credit secured by your home, usually at a variable rate tied to prime. You draw what you need, pay interest on what you have drawn, and can repay and redraw within the limit during the draw terms your lender sets. Combined HELOC-and-mortgage products have regulatory limits on the total secured borrowing relative to your home’s value, and your lender will confirm your specific limit. A HELOC suits costs that arrive in stages — a renovation with progress payments is the classic example — because you only pay interest on money actually out the door.

How is a home equity loan different?

It is a separate loan for a set amount, with a set payment schedule — closer to a second mortgage in structure. You get certainty of payment and usually a fixed structure in exchange for giving up the redraw flexibility: once repaid, that money is not available again without a new application. It suits one defined cost with a known total.

When does a full refinance beat both?

When your existing mortgage rate is uncompetitive, when you want one payment instead of two or three, or when the amount you need is large enough that mortgage pricing beats line-of-credit pricing by enough to cover the refinance costs — legal fees, appraisal, and any penalty to break your current term early. That penalty check is not optional: breaking a fixed mortgage mid-term can cost far more than the rate saving, which is why I run the full math before recommending it. Start any of the three conversations with a Mortgage Renewal Check if your term is ending soon anyway — timing a refinance to renewal can eliminate the penalty entirely. Also see cash-back mortgages: who pays for the ‘free’ money, and blend-and-extend: borrowing more without breaking your term.

“She got everything done fast and found me a great rate too. Honestly, I felt really taken care of the whole time.” — Vince, Google review

Edmonton homeowner comparing home equity borrowing options

Photo via Wikimedia Commons.

Renovation, debt consolidation, or a major purchase coming up? Call me at (780) 722-5621 and we will compare all three structures on your actual balance, rate and timeline — including the penalty, in writing. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

Hidden Costs of Old Edmonton Homes: How Lenders and Insurers Price Older Systems

General Travis Bannert 23 Oct

An older Edmonton home can pass a buyer’s inspection and still stall at funding if an insurer will not cover its wiring, plumbing, roof or heating on normal terms — because a mortgage requires home insurance in place at closing. The lender-and-insurer questions are predictable, so ask them during your condition period, not in closing week.

Which older systems do insurers ask about most?

Wiring comes first: some older electrical services and wiring types require an electrician’s confirmation, added protection, or a planned upgrade before an insurer will bind a standard policy. Plumbing materials are next — insurers and some lenders pay close attention to aging supply lines with a known failure history. Roofs are judged on age and condition, and older heating systems, including any remaining oil or wood-burning arrangements, draw their own questions and sometimes their own inspections or surcharges. For plumbing in detail, see Poly-B plumbing: insurance and lender questions in detail.

None of this means “do not buy an older home.” It means the insurance quote is part of the purchase math, alongside the mortgage payment — get a real quote on that specific house early.

How do lenders look at an older property?

The lender and, on insured files, the mortgage insurer review the property through the appraisal and the listing details: age, condition, remaining economic life, and whether the home is habitable and marketable as it stands. A home with major systems at end of life can still fund — but a home needing immediate essential work may need that work priced in the plan, handled through a purchase-plus-improvements structure, or addressed before funding depending on the lender’s rules. Condo buildings face the same kind of review — condo buildings get the same lender scrutiny as old systems.

“Mei is very detail-oriented, efficient, and managed to secure me a great rate.” — Kai Lo, Google review

Older Edmonton home systems that affect mortgage funding

Photo via Wikimedia Commons.

What should buyers of older Edmonton homes do, in order?

First, keep your inspection condition and use it to list every aging system with an estimated remaining life. Second, get an insurance indication on the actual property before you waive conditions. Third, tell your broker about any flagged system immediately — the time to match the file to the right lender is before conditions come off, not after. A Mortgage Renewal Check is for renewals; for a purchase, start with a proper pre-approval conversation and bring the property’s age and systems into it from day one. If the fixes need financing, see rolling the fixes into the purchase with purchase plus improvements.

Buying an older Edmonton home and want the insurance and lender questions answered before you waive conditions? Call me at (780) 722-5621. Or start with the Pre-Approval & Refinance Check.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, BFL Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com