New-Build Mortgage Approvals in Edmonton: Deposits, Rate Caps and Possession Delays

General Travis Bannert 21 Oct

New-build mortgage approvals in Edmonton work differently from a resale purchase because you are approved long before the home exists: you sign with a builder, pay deposits in stages, and your full approval and funding happen near possession, which can be many months later. The mortgage work splits in two — a builder cap or rate hold now to protect your ceiling, and a complete re-check of your file close to possession. Set both up at the start and a delayed possession is an inconvenience, not a crisis.
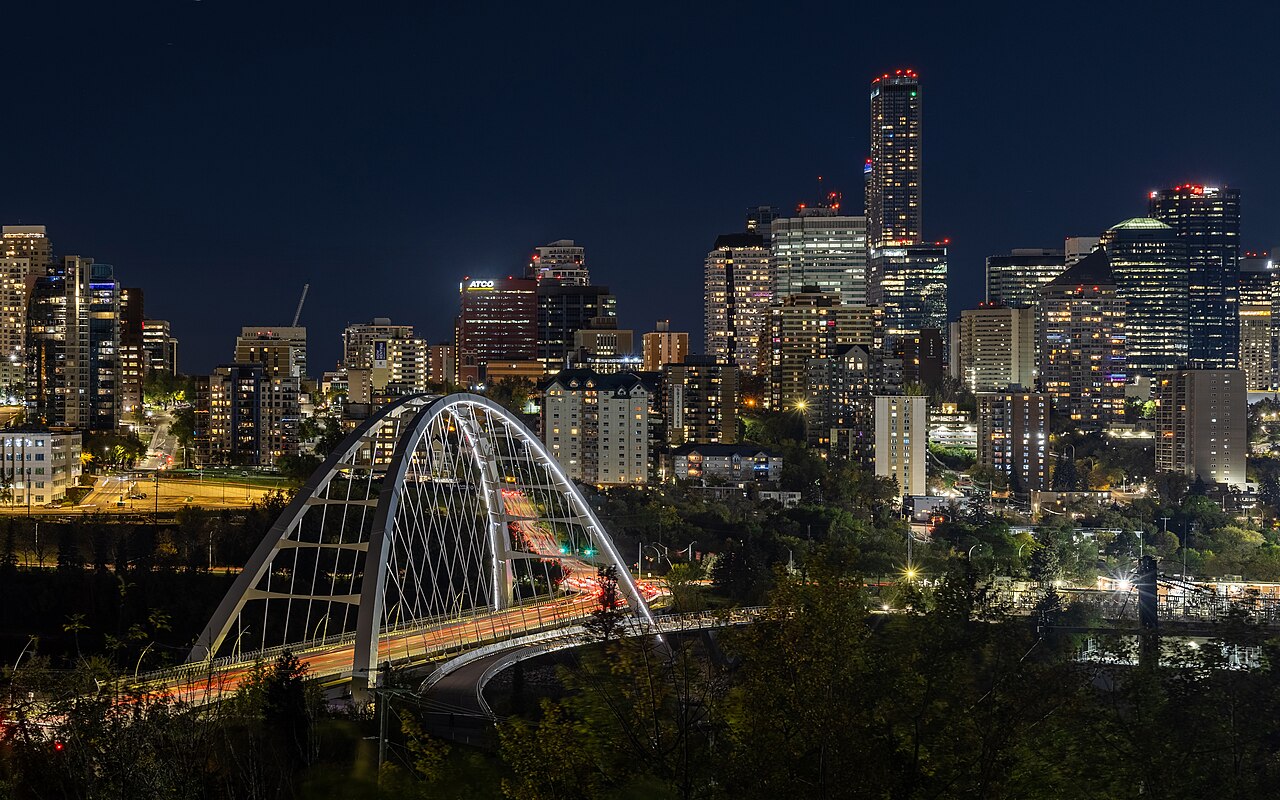
New construction homes in Edmonton — Walterdale Bridge
Photo: Crisco 1492, via Wikimedia Commons (CC BY-SA 4.0).

How do builder deposits and draws work?

Builders typically collect deposits in stages as construction reaches set milestones, rather than one lump sum at the end. Your deposit money is committed early and is not sitting in your account when the lender does its final review — so the down payment you show at possession has to account for every deposit already paid.

Some construction financing advances funds in draws as the build progresses; a conventional purchase from a builder usually funds once, at possession. Either way, keep statements proving where each deposit came from — lenders trace deposit funds as part of source-of-funds checks.

What is a rate cap, and how long can it run?

A builder cap is a long rate hold arranged through the builder’s lender or program — holds of 180 to 360 days are available in the market and vary by builder and lender. It caps the rate you will pay if rates rise during construction, while still letting you take a lower rate at possession if pricing has improved.

A standard pre-approval rate hold runs 90 to 120 days, which is rarely long enough for a full build. If your possession date is a season away, ask specifically about builder-cap options when you sign, not when the home is framed.

What gets re-checked before possession?

Near possession, the lender completes the file: current income and employment confirmation, updated credit, the finished property’s appraisal, and confirmation your down payment funds are in place. If your job, debts or credit changed during the build, the approval can change with them.

That is the quiet risk in new builds. A car loan taken mid-construction, or a job change in the final months, can shrink what you qualify for at exactly the moment you cannot walk away. Keep your financial picture boring from signing to possession.

“Absolutely the best, informative, great communication… and very helpful” — Michelle, Google review

What happens if possession is delayed?

Build timelines slip: weather, trades and inspections all push dates. A delay matters to your mortgage when it runs past your rate hold or cap expiry, or stretches beyond document validity windows — your broker then has to extend or re-apply, and rates are whatever they are that month.

Protect yourself at signing: know your cap’s expiry date, keep documents easy to refresh, and tell your broker about any financial change immediately rather than at final approval. If possession moves, the GST side of a new home moves with it — that piece is covered in GST on a New Home in Canada.

Start the process through my Pre-Approval & Refinance Check before you visit the show home, so deposit structure and rate protection are planned together.

What is the difference between a draw mortgage and a completion mortgage?

A completion mortgage funds once, at possession — the standard structure for a builder purchase. A draw mortgage advances funds in stages as construction reaches set milestones, with inspections at each stage; it is more common when you contract the build yourself and hold the construction risk. The right structure depends on who is building, and the draw schedule is agreed before the first shovel hits the ground.

What if the appraisal comes in below the contract price?

The home is appraised at completion, and the mortgage is based on the lower of the contract price and the appraised value. If the finished home appraises below what you agreed to pay, the difference is additional cash from you at closing — the lender will not fund the gap.

Keep a cushion beyond your deposit schedule, especially if you loaded the home with upgrades that appraisals tend to value conservatively.

Thinking about a new build in Edmonton or a surrounding community? Call me at (780) 722-5621 — I will try to call you this week, and if you reply with a good time, we can line up deposits, rate protection and possession timing before you sign.

By Travis Bannert, Realtor and Mortgage Broker
Travis Bannert, Mortgage Broker | Next Door Mortgages, Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
GST on a New Home in Canada: What Buyers Owe and How It Affects the Mortgage

General Travis Bannert 21 Oct

GST on a new home in Canada is 5% of the purchase price, charged on newly built homes and substantial renovations — and it is usually payable in cash at closing rather than rolled into the mortgage. That last point catches buyers off guard: most plan their down payment down to the dollar, then discover a five-figure tax bill due on possession day. Plan for it from the first budget, not the final week.

New home GST and closing funds in Edmonton — Walterdale Bridge
Photo: Crisco 1492, via Wikimedia Commons (CC BY-SA 4.0).

Which homes actually have GST charged on them?

GST applies to new housing: a newly constructed home, and in some cases a home that has been substantially renovated. Resale homes are generally exempt — no GST when you buy a used home from its owner.

In Alberta there is no provincial sales tax stacked on top, so the federal 5% GST is the full sales-tax picture on a new build here. That is one reason the Alberta new-home math looks different from provinces where a provincial tax is added as well.

Substantial renovation is a technical term with a threshold most casual updates never reach, but if you are buying a comprehensively rebuilt property, confirm its tax status in writing before you rely on it.

Can the GST be added to the mortgage?

Usually not. Lenders and insurers typically require GST on a new home to be paid from the buyer’s own funds at closing, separate from the mortgage advance. Confirm the treatment on your specific file early, because it changes how much cash you truly need.

That is the real planning point: your funds to close are the down payment, plus GST where it applies, plus your other closing costs. A pre-approval that only counts the down payment can leave you short on possession day even when the mortgage itself is approved.

It is also why new-build purchases are planned on two timelines at once. My guide to New-Build Mortgage Approvals covers the approval side, and a Pre-Approval & Refinance Check is where the full cash-to-close number gets worked out before you sign with a builder.

“We always refer our own clients, family and friends to Travis and his team without hesitation.” – Funk Law, Google review

Is there any relief from GST for first-time buyers?

A federal GST relief measure for first-time buyers of new homes was announced in 2025: up to the full GST on a new home priced up to $1 million, phasing out toward $1.5 million. Relief measures like this depend on legislation and program rules that are confirmed at the time you buy, so verify the current status before building it into a budget — never assume it has landed.

Separately, a long-standing GST New Housing Rebate has existed for qualifying new homes within specific price ranges, with its own forms and conditions. Whether either relief route applies to you is a question for your lawyer or tax advisor at the time of purchase.

What I can do as your broker is make sure the mortgage plan does not silently assume money you have not confirmed. If a rebate is coming, we plan for when it arrives — not before.

Is the builder’s price “plus GST” or “GST included”?

Ask this question before you sign, in those exact words. Builder prices are sometimes quoted net of GST, so the 5% lands on top of the number you budgeted around.

Get the answer in writing: the base price, the GST amount, any rebate the price assumes, and the total you will actually pay. Illustration only: on a $500,000 new home, 5% GST equals $25,000. That is arithmetic, not a quote — but it shows why the GST line deserves its own budget.

On rebates, the reference numbers: the long-standing GST New Housing Rebate lets buyers recover 36% of the GST, to a maximum of $6,300, with the full rebate applying at $350,000 or less. The newer federal GST relief for first-time buyers covers up to 100% of the GST on new homes up to $1 million for eligible buyers.

Buying new and want the full cash-to-close picture before you sign? Call me at (780) 722-5621 — I will try to call you this week, and if you reply with a good time, we can map your down payment, GST and closing costs on one page.

By Travis Bannert, Realtor and Mortgage Broker
Travis Bannert, Mortgage Broker | Next Door Mortgages, Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Self-Employed Mortgage Documents in Canada: Notices of Assessment, Financials and Add-Backs

General Travis Bannert 21 Oct

For a self-employed mortgage in Canada, the documents are the application: lenders typically want two years of personal tax returns and Notices of Assessment, plus your business financials, and they usually average your income across those two years. That creates the central tension of self-employed borrowing — the write-offs that lower your tax bill also lower the income a lender can see. The fix is starting your paperwork two years before you plan to buy.

Self-employed mortgage approval in Edmonton — skyline and High Level Bridge
Photo: Crisco 1492, via Wikimedia Commons (CC BY-SA 4.0).

What personal tax documents do lenders ask for?

Expect two years of T1 General tax returns, with the matching Notices of Assessment (NOAs) from the Canada Revenue Agency. The NOAs matter as much as the returns: they prove your taxes are filed as declared, with no tax arrears outstanding.

Income is commonly averaged over the two years. A strong recent year helps, but a declining pattern gets questions — a lender wants a business that is stable or growing. If one year was unusually weak for a clear reason, be ready to explain it with documents.

What extra documents depend on how your business is set up?

If you are a sole proprietor, your business income lives inside your personal return on the T2125 Statement of Business or Professional Activities, part of that T1 package.

If you are incorporated, expect T2 corporate tax returns and business financial statements, plus the T4 or T5 slips showing the salary or dividends you actually drew. Lenders lend to you personally, so how money reaches you matters.

Either way, supporting documents may also be requested: business registration or articles of incorporation, business bank statements, and GST/HST filings. The exact list varies by lender — confirm it for your file before you start gathering.

“Mei is very detail-oriented, efficient, and managed to secure me a great rate.” – Kani Lo, Google review

What are add-backs, and do they really help?

An add-back is an expense you wrote off for tax purposes that some lenders or insurers may add back to your income under certain programs. Portions of business-use-of-home and vehicle expenses, and depreciation or capital cost allowance in some programs, are common examples.

Be careful: add-backs are program-specific, not universal. One lender may recognize an expense another ignores, and stated-income style programs through the insurers exist for self-employed borrowers with strong credit and larger down payments — with rules that vary by insurer. Never build a plan around an add-back until a lender confirms it applies to you.

A broker can test your documents against more than one route. That review starts with my Pre-Approval & Refinance Check, and at renewal time, the Mortgage Renewal Check is the equivalent check on an existing mortgage.

How should self-employed buyers prepare ahead of time?

Work backwards from the purchase. Because lenders average two years, the returns you file this spring shape what you can borrow next year and the year after. Talk to your accountant and a mortgage broker before filing season if a purchase is on your two-year horizon — that conversation is far easier before the return is filed.

Keep clean, separate business records, file on time, and keep your NOAs somewhere you can find them. For a self-employed borrower, tidy paperwork is borrowing power.

Self-employed and thinking about a purchase or refinance in the next two years? Call me at (780) 722-5621 — I will try to call you this week, and if you reply with a good time, we can review your last two returns and map out what to do before the next one is filed.

By Travis Bannert, Realtor and Mortgage Broker
Travis Bannert, Mortgage Broker | Next Door Mortgages, Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
Spousal Buyout Mortgages in Alberta: Buying Out a Partner After Separation

General Travis Bannert 21 Oct

A spousal buyout mortgage in Alberta lets one partner keep the home after separation by treating the buyout like a purchase instead of a refinance – and that distinction is everything. Under the insured spousal buyout program offered through Canada’s mortgage insurers (CMHC, Sagen and Canada Guaranty), the staying spouse can borrow up to 95% of the home’s value, rather than being capped at the 80% limit on a normal refinance. For many separating couples, that extra room is the difference between keeping the home and being forced to sell it.

Buying out a partner's share of an Edmonton home — Edmonton skyline
Photo: Crisco 1492, via Wikimedia Commons (CC BY-SA 4.0) — Edmonton skyline and the High Level Bridge.

Why does the 95% limit matter so much?

On a standard refinance, you can only borrow up to 80% of your home’s value. If most of your equity is locked in the house – which is common early in a mortgage – 80% may not cover both the existing mortgage balance and the departing partner’s share of the equity.

The buyout program exists for exactly that gap. Because the insurers treat the transaction as a purchase, the ceiling rises to 95% of value. The staying spouse takes a new mortgage that pays out the old one and pays the departing spouse their share, and title transfers into one name.

What do you need to qualify for a spousal buyout?

The common requirements are straightforward, though details vary by insurer – confirm how they apply on your file. Both spouses are currently on title to the home. There is a finalized separation agreement or court order that documents the buyout and each partner’s share.

A full appraisal establishes the home’s current value, since every number in the buyout flows from it. The staying spouse must qualify for the new mortgage alone, and the stress test applies just as it would on any new mortgage.

Joint debts named in the separation agreement may be included in the new mortgage under insurer rules – again, that is program-specific, so it needs to be checked against your agreement rather than assumed.

“Great rates, fast closing, and excellent customer service.” – Madhav Dhakal, Google review

How does the buyout math actually work?

The framework is simple: appraised value minus the existing mortgage equals equity. The departing spouse’s share is whatever the separation agreement says – often half. The new mortgage is the old balance plus that buyout amount, and it must fit within the 95% ceiling.

Here is an illustration with round numbers, not a quote: a home appraised at $500,000 with a $300,000 mortgage has $200,000 in equity. A 50/50 share is $100,000, so the new mortgage is $400,000 – 80% of value, which fits comfortably.

Now picture the same home with a larger mortgage or a larger agreed share. The $475,000 ceiling at 95% is what gives the buyout room a refinance cannot. Running these numbers early shows whether keeping the home works before anyone commits to it in writing.

That is why the mortgage math should be run before the separation agreement is finalized, not after. A buyout figure written into an agreement that no lender can fund helps nobody – the agreement and the mortgage have to be built together. A Mortgage Renewal Check is not the tool for this, but a proper review through my Pre-Approval & Refinance Check is where we test whether you qualify alone, and for how much.

This article is mortgage information only, not legal advice – every buyout also needs a family lawyer reviewing the agreement itself.

Going through a separation and trying to keep the home? Call me at (780) 722-5621 – I will try to call you this week, and if you reply with a good time, we can run your buyout numbers privately before anything is finalized.

By Travis Bannert, Realtor and Mortgage Broker
Travis Bannert, Mortgage Broker | Next Door Mortgages, Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com
The First-Time Buyer Mortgage Journey in Edmonton: Saving, Pre-Approval and Funding, Step by Step

General Travis Bannert 21 Oct

The first-time buyer mortgage journey in Edmonton follows a clear order: save using the right accounts, get pre-approved with a rate hold, shop within the number you actually qualified for, then move through final approval, your lawyer, and funding on possession day. Two programs do most of the heavy lifting at the saving stage – the First Home Savings Account and the RRSP Home Buyers’ Plan. Work the steps in order, and each one makes the next one easier.

First-time home buyers in Edmonton — skyline from Saskatchewan Drive in fall
Photo: Crisco 1492, via Wikimedia Commons (CC BY-SA 4.0) — Edmonton skyline from Saskatchewan Drive.

Step 1: How should first-time buyers save the down payment?

Start with the First Home Savings Account (FHSA). You can open one and build up to $8,000 a year in contribution room, to a $40,000 lifetime maximum. Contributions are tax-deductible, and a withdrawal for a qualifying first home is tax-free.

Next, the RRSP Home Buyers’ Plan lets you withdraw up to $60,000 from your RRSP toward a first home, repaid over 15 years. Many Edmonton buyers use both – the FHSA for new saving, and the Home Buyers’ Plan for money already sitting in an RRSP.

Know the minimum down payment tiers before you set your target: 5% on the portion of the price up to $500,000, and 10% on the portion from $500,000 to $1.5 million for an insured purchase. Insured purchases are capped at a $1.5 million purchase price, and putting 20% down avoids mortgage default insurance altogether.

Step 2: What happens at pre-approval?

At pre-approval, a lender or broker reviews your income, debts, credit and documents, and confirms the mortgage amount you qualify for. That qualification uses the stress test: you must qualify at your contract rate plus 2%, or 5.25%, whichever is higher.

A pre-approval typically comes with a rate hold of 90 to 120 days, which protects your rate while you shop. It is not a final approval – the property itself still has to be approved later – but it tells sellers you are serious and tells you exactly where your ceiling is.

You can start that review with my Pre-Approval & Refinance Check, and first-time buyers can see the whole sequence in plain language in the First Home Guide for Edmonton.

“She took the time to understand my unique financial situation and offered tailored solutions… I’m now a proud homeowner.” – Ivan, Google review

Step 3: What happens after your offer is accepted?

With an accepted offer, your file moves to final approval. The lender verifies the property, may order an appraisal, and confirms your documents are current. Insured first-time buyers, and buyers of new builds, may qualify for a 30-year amortization under rules in place since December 2024 – worth asking about, because it changes the payment math.

Once approved, your lawyer takes over: reviewing title, preparing documents, and receiving the mortgage funds. On possession day, the funds flow, the sale registers, and you get your keys.

How much do you need beyond the down payment?

Budget for funds to close on top of the down payment. Those costs fall into predictable categories – legal fees, the appraisal where one is required, and the other closing items your lawyer will itemize for you. Ask for that full picture at pre-approval stage, not on the final week, so your down payment target reflects what you will actually need in the bank.

Saving for your first Edmonton home, or ready to check your number? Call me at (780) 722-5621 – I will try to call you this week, and if you reply with a good time, we can map your saving, pre-approval and shopping steps in one conversation.

By Travis Bannert, Realtor and Mortgage Broker
Travis Bannert, Mortgage Broker | Next Door Mortgages, Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

Fixed vs Variable Mortgages: Payment, Penalty and Flexibility Differences

General Travis Bannert 21 Oct

The real difference between a fixed and a variable mortgage in Canada isn’t today’s rate — it’s what moves your payment, and what it costs to leave. Variable rates follow your lender’s prime rate (driven by the Bank of Canada), while fixed rates are set by the bond market; variable penalties are usually three months’ interest, while fixed penalties use an interest-rate-differential calculation that can be far larger. Choose on payment behaviour and exit cost first, and the rate second.

Fixed vs variable mortgages in Edmonton — skyline from Saskatchewan Drive in fall

What actually moves each rate?

Variable: your rate is prime minus (or plus) a spread. Prime is currently 4.45%, because the Bank of Canada’s policy rate is 2.25% — and the Bank’s next decision is October 28. If the Bank moves, most variable rates move within days. Some variable mortgages have payments that rise and fall with prime; others hold the payment steady and change how much of it goes to interest — know which kind you’re being offered. See how a Bank of Canada move hits variable borrowers first.

Fixed: your rate is locked for the term, but it’s priced off Government of Canada bond yields, not the Bank of Canada. That’s why fixed rates climbed through September 2026 while the policy rate never moved — and why a Bank of Canada hold on October 28 wouldn’t automatically make fixed rates cheaper.

Which one costs more to break?

This is where the two products genuinely separate:

  • Variable (closed): the penalty is typically three months’ interest on the balance — predictable, and usually modest.
  • Fixed (closed): the penalty is the greater of three months’ interest or the interest rate differential (IRD) — a calculation based on the difference between your contract rate and current rates for the remaining term. When rates have fallen since you signed, IRD penalties can reach into five figures on a mid-size mortgage.

Life changes — a move, a sale, a separation, a refinance — break more mortgages than rate predictions do. If there’s a real chance you’ll sell or refinance inside the term, the penalty column matters more than a small rate difference. (Thinking of renewing instead of breaking? Run a Mortgage Renewal Check before signing anything.) See three months’ interest vs IRD: which penalty you’d actually pay.

“The team at NextDoor Mortgages (Mei & Travis) are the absolute best… provided the help I needed in securing my mortgage.” — Yomi Odusanya, Google review

So which suits you — fixed or variable?

Fixed tends to suit borrowers who need a payment that cannot change (tight monthly budget, first purchase, fixed income), and anyone who is confident they’ll stay in the home and the mortgage for the full term.

Variable tends to suit borrowers with payment room to absorb a rise, a shorter expected stay in the mortgage (where the three-months’-interest penalty protects them), and the temperament to ignore rate headlines between Bank of Canada decisions. See open vs closed: the prepayment privileges that decide flexibility.

Either way, the pre-approval stage is where this gets decided properly — with your income, your timeline, and a rate hold protecting you while you shop. My Pre-Approval & Refinance Check covers exactly that review, and first-time buyers can see the full sequence in the First Home Guide for Edmonton.

Renewing or buying before the October 28 decision? Call me and we’ll compare fixed and variable on your actual balance and timeline — payment, penalty, and flexibility — not just the headline rate.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

How Long Does a Mortgage Pre-Approval Last in Canada? (And What Can Change It)

First-Time Buyers & Getting Started Travis Bannert 21 Oct

A mortgage pre-approval in Canada typically lasts 90 to 120 days — that’s the window during which your lender holds your rate and your verified maximum purchase price. It is not a guaranteed approval: if your job, debts, credit, or down payment change during those 90–120 days, or if the home you choose has problems of its own, the lender can change or withdraw it. Here’s exactly how the clock works, and what resets it. See the first-time buyer journey this pre-approval starts.

What does a pre-approval actually lock in?

Two things. First, a rate hold: if rates rise while you shop, you keep the held rate; if they fall before you sign, most lenders let you take the lower one. With the Bank of Canada’s next decision on October 28 and its policy rate at 2.25%, that hold is real protection this fall — prime sits at 4.45%, and variable rates move with it.

Second, a verified budget: a real pre-approval (not a two-minute online pre-qualification) is based on pulled credit, reviewed income documents, and confirmed down payment, tested against the federal stress test. Sellers and their agents treat that letter very differently from a calculator printout. If you haven’t done this step yet, my Pre-Approval & Refinance Check walks through what gets reviewed. See the stress test and the qualifying rate behind your number.

What can change or void a pre-approval?

  • New debt. Financing a car, furniture, or a new credit card between pre-approval and closing changes your debt ratios — this is the single most common way buyers void their own pre-approval.
  • A job change. New employer, new probation period, or a switch to self-employment or commission income can all restart the income review.
  • Credit changes. Missed payments or a dropping score can change the lender’s answer at final approval.
  • The property itself. The lender and insurer still have to approve the home: a low appraisal, condo documents with problems, or property-condition issues can shrink or kill the approval.
  • An expired hold. If your 90–120 days run out before you have an accepted offer, the rate hold ends — even if nothing else changed.

See what can still make an approval fall apart after an accepted offer.

Edmonton home buyers — skyline from the High Level Bridge

What happens when a pre-approval expires?

Usually, nothing dramatic: we refresh the file, re-pull documents if they’ve gone stale, and issue a new pre-approval with a new rate hold at current rates. The risk isn’t the paperwork — it’s that rates may have moved while you were between holds. That’s why timing matters: serious Edmonton buyers start their pre-approval about four months before they want to be in the home, and renew the hold once rather than discovering the expiry during a negotiation. First-time buyers can see where this step fits in the full sequence in my First Home Guide for Edmonton.

“She got everything done fast and found me a great rate too. Honestly, I felt really taken care of the whole time.” — Vince, Google review

How do you keep a pre-approval alive?

Keep your file boring from pre-approval to possession: same job, no new debt, no large unexplained deposits, and tell your broker before — not after — anything changes. Life happens (job offers, family changes), and most changes can be planned around if they’re known early. The ones that kill deals are the surprises discovered at final review, days before the financing condition deadline.

Shopping this fall, or is your current pre-approval about to expire? Call me and I’ll check where your hold stands and renew it before the October 28 rate decision — a hold costs nothing and keeps your budget exactly where you planned it.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

Mortgage Stress Test Explained: The Qualifying Rate and Your Edmonton Budget

General Travis Bannert 21 Oct

Under Canada’s mortgage stress test, you don’t qualify at the rate you’ll actually pay — you qualify at the higher of your contract rate plus 2%, or the federal benchmark rate of 5.25%. The test doesn’t change your real payment; it caps how much a federally regulated lender can approve you for, and on a typical Edmonton purchase it reduces the maximum mortgage by roughly 15–20% compared with qualifying at the contract rate alone.

How does the stress test calculation work?

Take your contract rate, add 2 percentage points, and compare it with 5.25%. Your file is tested at whichever is higher. Your income then has to carry the mortgage at that qualifying rate inside the standard debt-ratio limits (housing costs within the gross debt service ratio, and total debts within the total debt service ratio) that lenders and insurers apply.

A worked example with round numbers — an illustration, not a rate quote:

  • Example contract rate: 4.50% → qualifying rate: 6.50% (4.50% + 2%, which is higher than the 5.25% benchmark)
  • A $400,000 mortgage over 25 years at 4.50% costs about $2,223/month
  • The same payment room tested at 6.50% supports only about $329,000 of mortgage

That’s the whole effect in one line: at a qualifying rate 2 points higher, the same income supports roughly $70,000 less mortgage on a $400,000 example. Your actual numbers move with your real rate, income, debts, property taxes, and heating costs — which is why a proper Pre-Approval & Refinance Check uses your file, not a generic calculator. See the affordability worksheet: running the ratios on your numbers.

Who does the stress test apply to?

  • Insured mortgages (less than 20% down): yes — the test is built into the mortgage insurer’s rules.
  • Uninsured mortgages (20%+ down) at banks and other federally regulated lenders: yes, under the federal B-20 rules.
  • Renewals: if you simply renew with your current lender, you’re generally not re-tested; switching lenders at renewal usually means qualifying again under the rules that apply to a new application. If a renewal is coming up, check your position with a Mortgage Renewal Check before assuming you can move.
  • Some provincially regulated lenders (such as credit unions) may not be required to apply the federal test the same way — one of several reasons broker access to multiple lender types matters on tight files.

Edmonton mortgage budget — Walterdale Bridge into downtown

Does the stress test change what you actually pay?

No. Your payment is always based on your real contract rate. The test is an underwriting cushion: it checks that you could still carry the mortgage if rates were higher at renewal. It’s also why two buyers with the same income can be approved for very different amounts at different times — when contract rates rise, contract-plus-2% rises with them, and maximum approvals fall even before any lender says no.

“Great rates, fast closing, and excellent customer service.” — Madhav Dhakal, Google review

How can Edmonton buyers work with the stress test instead of against it?

Three levers actually move your tested budget: paying down other debts before applying (car payments are the usual culprit), increasing the down payment, and choosing the amortization and property costs (taxes, condo fees, heat) that the ratios actually count. Guessing helps none of them. First-time buyers can see how the test fits into the full buying sequence in my First Home Guide for Edmonton. See how much down payment changes the qualifying picture.

Want your real tested number — not a calculator’s guess? Call me and I’ll run your file through the stress test properly, and show you which lever would raise your budget the most before you start shopping. See how long your pre-approval — and its qualifying rate — lasts.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

Edmonton Mortgage Rate Hold: Why to Lock a Rate Before the Bank of Canada’s October 28 Decision

General Travis Bannert 20 Oct

If your Edmonton mortgage renews in the next four months — or you’re planning to buy this fall — get a rate hold this week, before the Bank of Canada’s October 28 decision. A rate hold costs nothing, locks today’s rate for typically 90 to 120 days, and still lets you take a lower rate if prices fall before you sign. With inflation back above 3%, the October 28 decision is the first one in a year where a hike is genuinely on the table. If your timeline is longer, see what to do when a rate hold expires before possession.

What is the Bank of Canada’s rate right now, and what happens October 28?

The Bank of Canada’s policy rate is 2.25%, where it has sat since October 2025 — held at seven straight decisions, most recently on September 2, 2026. The big banks’ prime rate, which drives variable-rate mortgages, is 4.45%. The next decision lands Wednesday, October 28, 2026, alongside the Bank’s quarterly Monetary Policy Report. For more detail, see what the October 28 decision actually does to your mortgage.

What changed: Statistics Canada reported September inflation at 3.1% — above the Bank’s 2% target and the top of its control range — even though the Bank’s core measures stayed calmer (CPI-median 1.9%, CPI-trim 1.8%). That split is exactly why nobody honest can tell you today whether October 28 brings a hold or a 0.25-point hike. What you can do is make sure either answer costs you nothing. See also when forecasters split: Oxford says hike, C.D. Howe says hold.

How does a mortgage rate hold actually protect you?

If rates go up: your held rate stands. A variable-rate increase moves prime — and variable payments — the day after a Bank of Canada hike. A fixed-rate increase usually arrives even earlier, because fixed rates follow the bond market, not the Bank: fixed pricing climbed through September 2026 while the policy rate never moved. A rate hold freezes your side of both risks.

If rates go down: most lenders will honour the lower rate at signing if you ask before closing. A hold is a ceiling, not a floor — that’s why there’s no downside to getting one early.

Who should hold a rate right now?

  • Your mortgage renews any time in the next 120 days (don’t wait for the renewal letter — by the time it arrives, you’re negotiating late; see my Mortgage Renewal Check).
  • You’re buying this fall and want your budget protected while you shop (a hold pairs with your pre-approval — see the Pre-Approval & Refinance Check).
  • You’re a first-time buyer getting your numbers in order (start with the First Home Guide for Edmonton).

“Mei is very detail-oriented, efficient, and managed to secure me a great rate.” — Kani Lo, Google review

What should Edmonton borrowers do this week?

  1. Check your renewal date — if it’s before the end of February 2027, you’re inside the hold window now.
  2. Get a written rate hold from at least one lender other than your current bank, so you have a real number to compare.
  3. If you’re on an adjustable-payment variable rate, know your number: a 0.25-point hike on a $400,000 mortgage adds roughly $55 a month to the payment — decide in advance whether you’d stay variable or fix.
  4. Don’t sign your bank’s first renewal offer this month of all months — the market may reprice everything on October 28.

Renewing or buying before spring? Call me this week and I’ll set up your rate hold and walk through the hold-vs-hike math on your actual mortgage — no obligation, and the hold itself is free.

By Travis Bannert, Realtor and Mortgage Broker

Travis Bannert, Mortgage Broker | Next Door Mortgages, Dominion Lending Centres | (780) 722-5621 | nextdoormortgages.com

Mortgage Renewal in 2026? Why Your Bank’s First Offer Is Rarely Its Best

General Travis Bannert 20 Oct

If your mortgage term started in 2021, it renews in 2026 — and the renewal letter your bank mails you is an opening offer, not their best one. Signing it without a comparison takes minutes and can cost you for the entire next term. A free renewal check before you sign tells you whether the offer is fair — and if it isn’t, a broker can shop your renewal across dozens of lenders, usually at no cost to you.

Why 2026 renewals deserve a second look: five-year terms taken in 2021 were priced in a very different rate environment. Your payment, your balance, and your options have all changed since then. Lenders know most homeowners sign the first letter out of convenience — which is exactly why that letter is rarely the sharpest rate they can offer.

What to check before you sign:

  • The rate itself — against what other lenders are offering for the same term
  • Prepayment privileges — can you pay extra without penalty if your income rises?
  • Portability — does the mortgage move with you if you sell and buy?
  • Penalties — what does it cost to break this term early if life changes?
  • Term length — does a shorter or longer term fit your actual plans better?

See renewing with a new lender: what a switch involves, step by step. On term length, see blend-and-extend: when averaging your rate helps. On portability, see porting your mortgage if the renewal coincides with a move.

Start early: rate holds run 90 to 120 days, so beginning the conversation about four months before your renewal date protects you if rates move while you decide. There is no downside to checking early — and the check itself is free.

Next Door Mortgages will review your renewal offer honestly: if your bank’s number is genuinely good, we’ll tell you to sign it. If it isn’t, we’ll show you the better option and handle the switch paperwork.

Call Next Door Mortgages at (780) 722-5621, or start with our Mortgage Renewal Check page. For the real estate side, call Travis Bannert at 780-720-8240 or visit bridgerealtygroup.ca.

By Travis Bannert, Realtor and Mortgage Broker